
How to Read Auto Loan Disclosures Before Signing
Reading auto loan disclosures before signing protects your wallet. Spot hidden fees and verify the APR to avoid overpaying by thousands.
By Sarah Mitchell
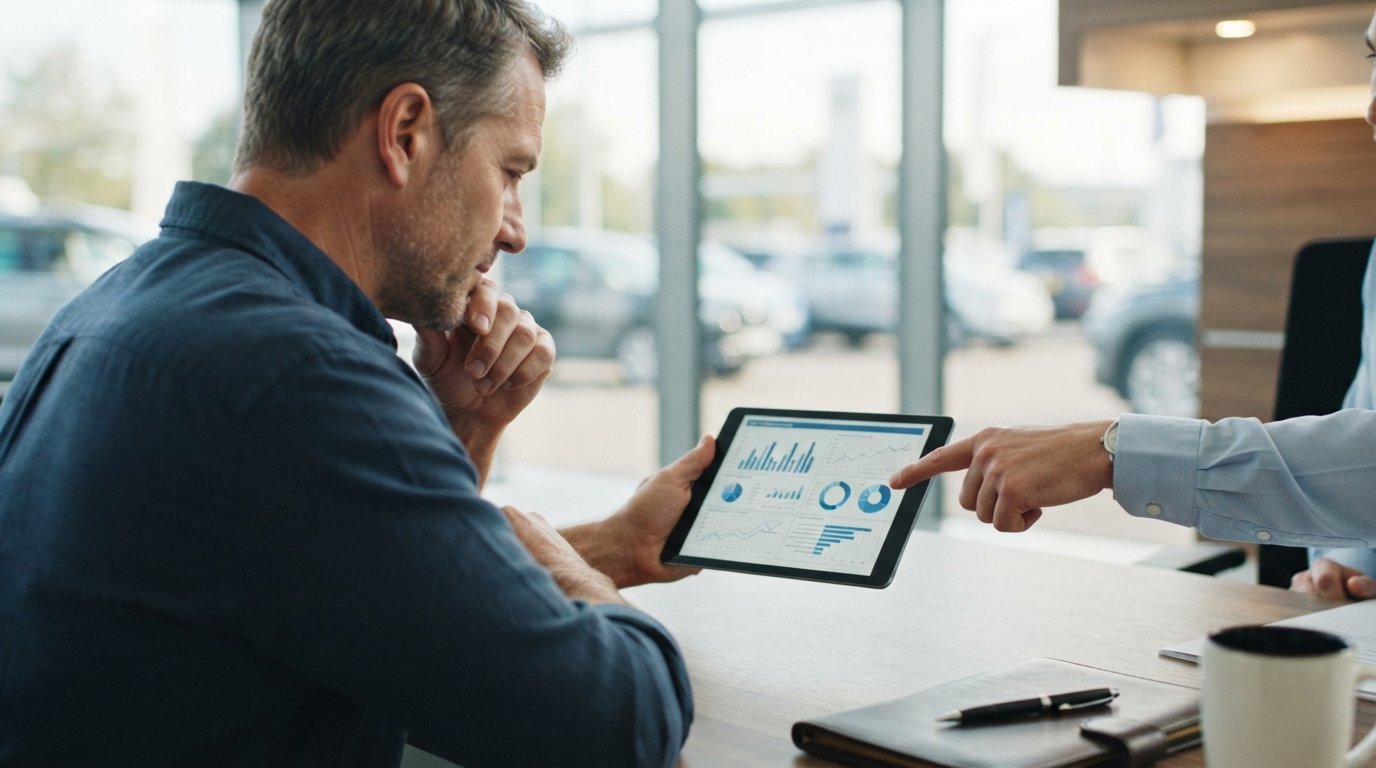
You are sitting at the dealership finance desk, the salesperson slides a tablet toward you, and suddenly you are expected to digest a wall of numbers and legal text before you sign away the next five to seven years of your income. Most buyers focus only on the monthly payment, but that single figure hides the details that actually determine whether you are getting a fair deal or a financial trap. Learning how to read auto loan disclosures before signing is the single most effective way to protect your wallet, your credit, and your peace of mind.
Federal law requires lenders to provide specific disclosures that lay out the true cost of borrowing. These documents are not just bureaucratic formalities, they are your roadmap to understanding exactly what you are agreeing to. Whether you are financing a new car, a used vehicle, or considering a refinance later, the ability to decode these forms gives you leverage to negotiate and the confidence to walk away from bad terms.
The Big Picture: Truth in Lending and Your Rights
Before diving into the specific line items, it helps to understand the framework behind these documents. The Truth in Lending Act (TILA) is a federal law designed to promote the informed use of consumer credit. It mandates that lenders disclose the terms and cost of credit in a standardized format. This standardization exists so you can compare offers from different lenders, such as a bank, a credit union, or a dealership, on an apples-to-apples basis.
When you receive a loan estimate or a final contract, you are seeing the result of these regulations. However, standardized does not mean simple. Lenders use specific terminology that can be confusing if you are not prepared. Understanding the difference between the Annual Percentage Rate (APR) and the interest rate, for example, is crucial because the APR includes fees and costs, while the interest rate only covers the cost of borrowing the principal. If you only look at the interest rate, you might miss thousands of dollars in hidden costs.
Moreover, these disclosures act as a contract. Once you sign, you are legally bound to the terms listed, even if you did not read them carefully. This is why the review process should happen before you enter the finance office, not while you are sitting in it. Taking the time to review these documents at home or in a quiet corner of the dealership allows you to spot errors, question fees, and negotiate terms without feeling rushed.
Anatomy of the Key Documents You Will See
When you finance a vehicle, you will typically encounter two main types of documents: the financing agreement (often called a Retail Installment Sales Contract) or a promissory note, and the Truth in Lending disclosure statement. While they serve different purposes, they work together to outline your obligations. The financing agreement is the contract where you promise to pay back the money borrowed plus interest. The Truth in Lending statement is the summary sheet that highlights the costs.
In many cases, these are combined into a single document, but you should always ask for both if they are separate. The financing agreement will contain the legal jargon regarding default, repossession, and arbitration clauses. The disclosure statement will contain the numbers. Your goal is to ensure the numbers in the disclosure match the promises made during the sales negotiation. If the salesperson promised a 4% rate but the document says 6%, you have a problem that needs immediate correction.
It is also important to distinguish between a loan disclosure and a lease disclosure. If you are leasing, the terminology changes significantly. You will see terms like "money factor" instead of interest rate and "residual value" instead of payoff amount. Leasing disclosures are governed by different rules, so if you are looking at a lease, make sure you are reading the correct type of paperwork. For this guide, we are focusing on purchase financing, but the principle of reading every line remains the same.
Line by Line: Decoding the Numbers That Matter
Once you have the document in hand, you need to know where to look. The layout can be dense, but the most critical information is usually boxed or bolded. You should start with the top section, which outlines the basics of the deal, and then move down to the specific costs and terms. Do not let the sheer volume of text intimidate you; focus on the specific figures that impact your monthly budget and total cost.
Here are the essential elements you must verify before putting pen to paper:
- Amount Financed: This is the total amount you are borrowing. It includes the price of the car, taxes, title fees, and any add-ons (like extended warranties or gap insurance) that you agreed to finance. Verify that this number matches the negotiated price of the vehicle plus the agreed-upon fees. If it is higher than expected, ask why.
- Finance Charge: This is the dollar amount you will pay for the privilege of borrowing the money. It represents the total cost of credit over the life of the loan. A lower finance charge means you are paying less to borrow.
- Annual Percentage Rate (APR): This is the cost of credit expressed as a yearly rate. It is often higher than the advertised interest rate because it includes certain fees. When comparing loans, the APR is the best number to use for an apples-to-apples comparison.
- Total of Payments: This is the sum of the amount financed plus the finance charge. It tells you exactly how much you will have paid by the time the loan is complete. Seeing this total can be a wake-up call regarding how much the car actually costs you.
Beyond these four pillars, look for the payment schedule. This section details how many payments you will make and the amount of each payment. Ensure the first payment date gives you enough time to set up your budget. If you are trading in a vehicle, ensure the trade-in value and payoff amount for your old loan are correctly listed. Negative equity from a previous loan, often called being "upside down," will be rolled into the new loan, increasing the amount financed.
If you find that the numbers do not add up, or if the monthly payment is higher than you discussed, stop the process. Do not let the finance manager tell you that the computer made a mistake or that the numbers will be adjusted later. Once signed, correcting an error becomes a customer service nightmare. If you are considering refinancing later to fix a bad deal, you can review options for lowering your rate, but it is always better to get it right the first time.
Understanding the Fine Print and Clauses
The numbers are only half the story. The fine print on the back of the contract or in the lower sections contains the legal terms that govern the loan. These clauses explain what happens if you miss a payment, what fees are associated with late payments, and how the lender can repossess the vehicle. While it is tempting to skip this section, doing so can leave you vulnerable to unexpected costs.
One of the most important clauses to look for is the prepayment penalty. This is a fee charged if you pay off the loan early. If you plan to refinance or pay off the car quickly to save on interest, a prepayment penalty could wipe out your savings. Most reputable lenders do not charge this fee, but you must verify it is absent. Similarly, check the late fee structure. Some lenders charge a flat fee, while others charge a percentage of the payment. Knowing these costs helps you prioritize payments if money gets tight.
Another critical area is the arbitration clause. This clause often requires you to resolve disputes through arbitration rather than going to court. While this is common in many contracts, you should be aware that it limits your legal options. Additionally, look for any clauses regarding warranties or insurance requirements. Lenders often require you to maintain comprehensive and collision insurance. If you fail to do so, the lender may purchase "force-placed" insurance on your behalf and add the cost to your loan balance, which is usually much more expensive than insuring the car yourself.
If you are working with a lender that specializes in bad credit or unique situations, such as those found through platforms like StartAutoLoan, the terms may be stricter due to the perceived risk. This makes reading the fine print even more critical. Understanding the specific conditions of your loan, such as whether the lender requires a co-signer or specific down payment, ensures you do not violate the terms inadvertently.
Comparing Offers and Negotiating Terms
Reading disclosures is not just about accepting what is offered; it is about using that information to negotiate. When you have the numbers in front of you, you can see where the lender is making their money. For example, if the finance charge is high, you can negotiate a lower interest rate or a shorter loan term to reduce the total cost. If the amount financed includes expensive add-ons, you can ask to remove them or negotiate their price.
You should never accept the first offer without comparing it to at least one other source. Before you go to the dealership, get pre-approved for a loan from a bank or credit union. This gives you a baseline. When the dealer presents their financing, you can compare their APR and terms against your pre-approved offer. If the dealer's offer is better, great. If not, you can either use your pre-approved loan or ask the dealer to match the terms.
Remember that dealers often have the ability to mark up the interest rate above what the lender actually charges them. This is called the dealer reserve. By knowing the market rates for your credit score, you can spot this markup and negotiate it down. If you have already signed a loan with a high rate and are wondering if you can improve it, you might explore decoding auto loan disclosures before you sign, which explains how to spot these markups and refinance them later.
Negotiation is not just about the price of the car; it is about the financing terms. A lower interest rate over the life of a 60-month loan can save you hundreds or even thousands of dollars. Do not be afraid to ask for a better deal. If the finance manager says they cannot change the rate, ask if they can lower the price of the car or remove fees to bring the total cost down. Every dollar you save on the principal or the finance charge is a dollar in your pocket.
Red Flags and Warning Signs
While reviewing your documents, keep an eye out for certain red flags that indicate a predatory loan. One major warning sign is a payment that is too high for your budget. Lenders sometimes push buyers into longer loan terms (72 or 84 months) to lower the monthly payment, but this means you pay much more in interest over time and stay upside down on the car for longer. If you cannot afford the payment on a standard term, you likely cannot afford the car.
Another red flag is a loan term that exceeds the life expectancy of the vehicle. If you are financing a used car with 100,000 miles for 72 months, you may end up paying for a car that has stopped running. Additionally, be wary of "yo-yo" financing, where the dealer lets you take the car home but calls you later to say the financing fell through and you need to sign a new contract with worse terms. This is illegal in many places, but it happens. Do not take the car home until the financing is finalized and you have a copy of the signed contract.
Finally, watch out for add-ons that are tacked onto the loan without your explicit consent. Items like credit insurance, VIN etching, or paint protection are often added by the finance manager to boost profit. These items should be optional. If you see them on the disclosure and you did not ask for them, demand they be removed. You can always purchase insurance or protection products elsewhere for less.
Taking Action Before You Sign
The moment of signing is your last line of defense. Before you sign, ask for a copy of the contract to review. You are entitled to take your time. Do not let anyone rush you. If the finance manager is pressuring you to sign quickly, that is a sign to slow down. Take a photo of the documents with your phone, or take them to a quiet table to read through them.
Verify that all the blanks are filled in and that there are no empty spaces where numbers could be added later. Check that the vehicle identification number (VIN) on the contract matches the car you are buying. Ensure that the trade-in information, if applicable, is correct. If you are unsure about any term, ask for clarification. A reputable lender will explain the terms clearly. If they refuse or give vague answers, walk away.
Once you sign, you are committed. The time you spend reviewing the auto loan disclosures before signing is an investment in your financial future. It gives you the power to say no to bad deals and yes to financing that fits your life and your budget.