
Motorcycle Loan Down Payment Requirements and Credit Score
Motorcycle loan down payment requirements and credit score decide your approval. See typical percentages by credit tier and how to lower your payment.
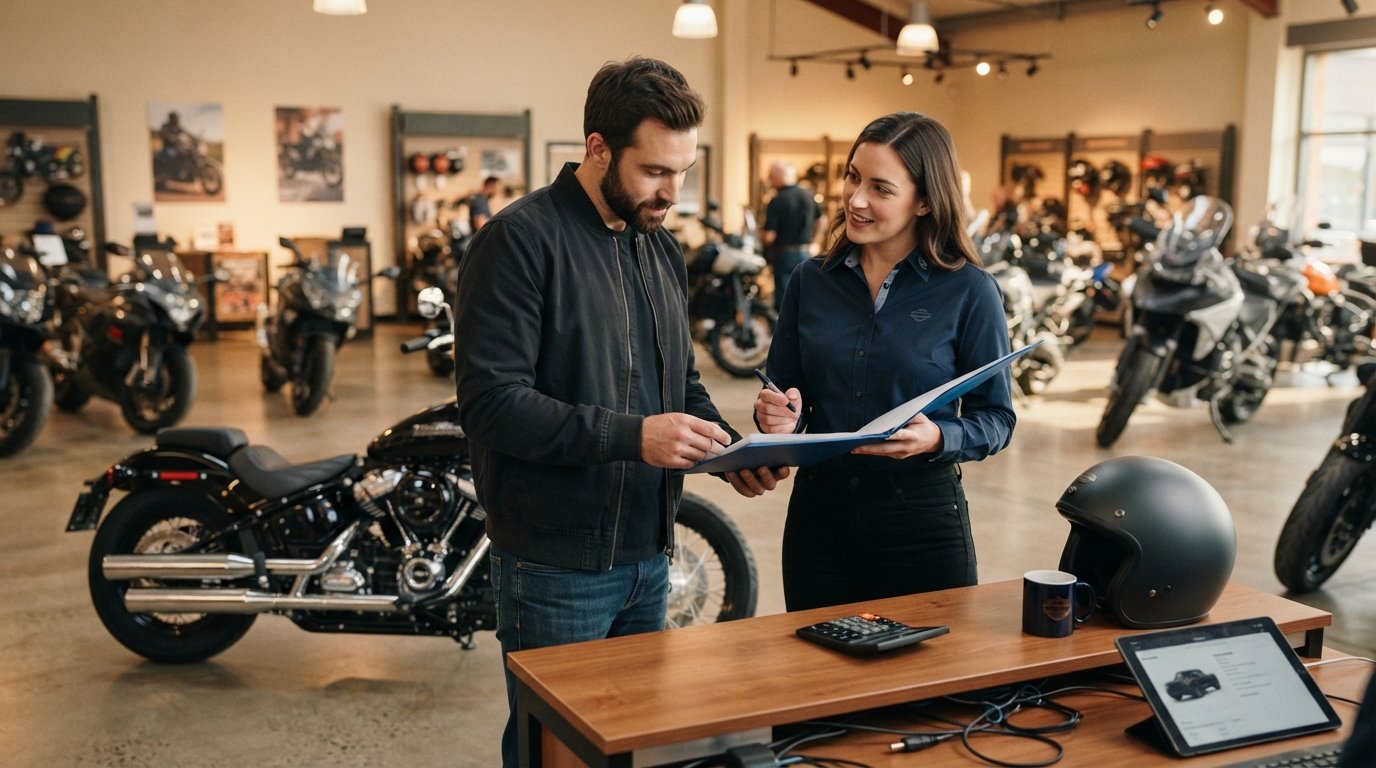
Buying a motorcycle is exciting, but the financing side often catches riders off guard. Unlike car loans, motorcycle loans come with stricter underwriting standards, and the down payment you need depends heavily on your credit score. Whether you are eyeing a cruiser, a sportbike, or a commuter, understanding how lenders view motorcycles and what they require upfront can save you thousands over the life of the loan. This guide breaks down the typical down payment percentages across credit tiers, explains how motorcycle lending differs from auto lending, lists the documents you will need, and shows how refinancing later can lower your payment.
Why Motorcycles Are Underwritten Differently Than Cars
Lenders treat motorcycles as recreational vehicles, not essential transportation. That distinction matters because it changes the risk calculus. Cars are more likely to be used daily for work, and they hold value more predictably. Motorcycles are often seasonal, easier to damage, and more likely to be stolen. As a result, lenders see higher risk and adjust their terms accordingly. You will typically see higher interest rates, shorter loan terms, and larger down payment requirements compared to a car loan of the same amount.
Another key difference is the loan-to-value ratio. For cars, some lenders will finance up to 100% or even 110% of the vehicle value. For motorcycles, most lenders cap financing at 80% to 90% of the purchase price, which means you need to cover the remaining 10% to 20% out of pocket. This is why the down payment question is so central to motorcycle financing: it is not just about your credit; it is about the lender's comfort with the collateral.
Additionally, motorcycle loans often have shorter terms, usually 36 to 60 months, compared to 72 or 84 months for cars. A shorter term means higher monthly payments, but it also reduces the lender's exposure. If you are considering a motorcycle loan, it helps to understand these structural differences before you apply.
Typical Down Payment Percentages by Credit Tier
There is no single down payment requirement for motorcycle loans. Instead, lenders set minimums based on your credit score, income stability, and the age and type of the bike. The table below outlines common ranges, though individual lenders may vary.
- Excellent credit (720+): 0% to 10% down. Some lenders offer zero-down financing for well-qualified buyers, especially on new motorcycles.
- Good credit (660-719): 10% to 15% down. You may still find promotional zero-down offers, but expect tighter approval criteria.
- Fair credit (600-659): 15% to 20% down. Lenders want more skin in the game to offset risk.
- Poor credit (below 600): 20% to 30% down or more. Some lenders may require 30% or decline the application entirely.
These percentages are not set in stone. A larger down payment can sometimes compensate for a lower credit score, and a strong credit score can reduce the down payment requirement. For example, a buyer with a 580 score and 30% down may get approved, while a buyer with a 620 score and 10% down might be denied. The down payment and credit score work together in the lender's risk model.
It is also worth noting that the type of motorcycle matters. Newer, higher-value bikes from established manufacturers are easier to finance with lower down payments. Older, modified, or off-brand motorcycles often require larger down payments because resale value is harder to predict. If you are buying a used motorcycle from a private seller, expect even stricter terms, as lenders have less confidence in the collateral.
What Credit Score Do You Actually Need for a Motorcycle Loan?
There is no official minimum credit score for motorcycle loans, but most lenders have internal cutoffs. In practice, a score of 600 is often the floor for mainstream lenders, while 650 or higher opens up better rates and lower down payment options. Scores below 600 are not automatically disqualifying, but your options shrink and the cost of borrowing rises.
Credit score affects more than just approval. It determines your interest rate, which in turn affects your monthly payment and total cost. A 100-point difference in credit score can mean several percentage points in APR. For example, a borrower with a 720 score might qualify for a 6% APR, while a borrower with a 620 score might see 12% or higher. On a $10,000 loan over 48 months, that difference can add up to hundreds of dollars in interest.
If your credit is not where you want it to be, you have options. Some lenders specialize in bad credit motorcycle financing, though they often require larger down payments and charge higher rates. Alternatively, you can work on improving your credit before applying. Paying down balances, correcting errors on your credit report, and avoiding new credit inquiries can boost your score in a few months. For a deeper dive into improving your credit profile, see our guide on motorcycle loan refinance to lower payments.
It is also important to shop around. Different lenders have different credit score thresholds and down payment requirements. A credit union might be more flexible than a national bank, especially if you have an existing relationship. Online lenders may offer pre-qualification with a soft credit pull, letting you see your estimated terms without affecting your score. Taking the time to compare offers can save you money and help you find a lender that works with your credit situation.
Documents and Income Proof You Will Need
Motorcycle loan applications require documentation similar to car loans, but lenders may scrutinize income and residency more closely because of the higher risk. Being prepared can speed up the process and improve your chances of approval. Here is what you will typically need:
- Proof of identity: A valid driver's license or state-issued ID. Some lenders also require a motorcycle endorsement on your license, though not all do.
- Proof of income: Recent pay stubs (usually the last two or three), W-2s, or tax returns if you are self-employed. Bank statements may also be requested to verify deposits.
- Proof of residence: A utility bill, lease agreement, or mortgage statement showing your current address.
- Insurance information: Lenders often require proof of comprehensive and collision coverage before funding the loan. Motorcycle insurance is mandatory in most states, so have your policy details ready.
- Vehicle information: The make, model, year, VIN, and purchase price of the motorcycle. If buying from a dealer, the purchase agreement will cover this.
In addition to these documents, lenders will pull your credit report and may ask for explanations of any derogatory marks, such as a recent bankruptcy or collection account. Having a written explanation ready can help. If you have a co-buyer or cosigner, their documentation will also be required. A cosigner with strong credit can sometimes reduce the down payment requirement and improve your approval odds.
Income proof is especially important for motorcycle loans because lenders want to see that you can afford the payment alongside other obligations. They will calculate your debt-to-income ratio, which compares your monthly debt payments to your gross monthly income. A DTI below 40% is generally preferred, though some lenders will go higher with a larger down payment. If your DTI is high, paying down other debts before applying can make a difference.
How Down Payment and Credit Score Interact
Down payment and credit score are not independent factors. Lenders use both to assess risk, and a strength in one area can sometimes offset a weakness in the other. For example, a borrower with a 640 credit score and a 25% down payment may be approved at a reasonable rate, while a borrower with the same score and 5% down may be denied or offered a higher rate. The down payment reduces the lender's exposure, so it acts as a cushion against default.
Conversely, a very strong credit score can sometimes unlock zero-down financing, even though the lender's standard policy might require 10% down. This is because the lender trusts that the borrower is low-risk and will repay the loan. If you have excellent credit, ask about promotional offers or special programs for well-qualified buyers. You may be surprised at how much flexibility exists.
It is also worth considering the total cost of the loan, not just the down payment. A larger down payment lowers your monthly payment and reduces the amount you finance, which saves you interest. But if you drain your savings to make a large down payment, you may leave yourself vulnerable to unexpected expenses. A balanced approach is usually best: put down enough to satisfy the lender and keep your payment affordable, but keep some cash in reserve for maintenance, insurance, and emergencies.
Refinancing Your Motorcycle Loan Later
If you already have a motorcycle loan with a high interest rate or a payment that strains your budget, refinancing can help. Refinancing means taking out a new loan to pay off the old one, ideally at a lower rate or with better terms. Many lenders offer motorcycle refinancing, and the process is similar to car refinancing. You apply, provide documentation, and if approved, the new lender pays off the old loan. You then make payments to the new lender.
Refinancing can lower your monthly payment by extending the term or reducing the interest rate. It can also help you pay off the loan faster if you shorten the term, though that usually means a higher monthly payment. The key is to compare offers and calculate the break-even point, including any fees. If you can lower your rate by even a few percentage points, the savings can be significant over the remaining life of the loan.
One caveat: refinancing a motorcycle loan with bad credit can be challenging. Lenders will still look at your credit score and down payment (or equity in the bike). If your credit has improved since you bought the motorcycle, you may qualify for a better rate. If not, you may need to improve your credit first or consider a cosigner. For riders who need financing options despite credit challenges, platforms like AutoTitleLoan connect consumers with lenders who specialize in bad credit and no credit situations. These services can be a useful starting point, though always review the terms carefully.
Before refinancing, check whether your current loan has any prepayment penalties. Most motorcycle loans do not, but it is worth confirming. Also, consider the age of the motorcycle: some lenders will not refinance bikes older than a certain age or with high mileage. If your bike is older, you may have fewer options, but it is still worth exploring.
Strategies to Improve Your Approval Odds
If you are planning to apply for a motorcycle loan, a little preparation can go a long way. Here are some practical steps to improve your chances of approval and secure better terms:
- Check your credit report: Get a free copy from AnnualCreditReport.com and dispute any errors. Even a small error can drag down your score.
- Save for a larger down payment: Aim for at least 10% to 20% of the purchase price. This reduces the lender's risk and can lower your rate.
- Pay down existing debt: Lowering your credit card balances and other debts improves your debt-to-income ratio and credit utilization, both of which matter to lenders.
- Get pre-qualified: Many lenders offer pre-qualification with a soft credit pull, which lets you see estimated rates and terms without affecting your score. This helps you shop around with confidence.
- Consider a cosigner: If your credit is weak, a cosigner with strong credit can boost your application and potentially reduce your down payment requirement.
These steps take time, so start early if you can. Even a few weeks of focused effort can make a noticeable difference in your credit score and your loan offers. And remember, the motorcycle buying process is not a race. Waiting until you are financially prepared can save you money and stress.
Final Thoughts on Motorcycle Financing
Motorcycle loan down payment requirements and credit score go hand in hand. Lenders use both to gauge risk, and the right combination can mean the difference between approval and denial. By understanding how motorcycles are underwritten, what down payment percentages to expect at your credit tier, and what documents you will need, you can approach the process with confidence. And if you already have a loan that is not working for you, refinancing is a powerful tool to lower your payment or pay off the bike faster. Whether you are a first-time rider or a seasoned enthusiast, smart financing decisions help you enjoy the ride without financial strain.