
EV Financing Incentives and Loan Considerations for 2026
Understand how EV incentives, battery health, and lender rules affect your auto loan, plus how to budget for insurance and charging costs.
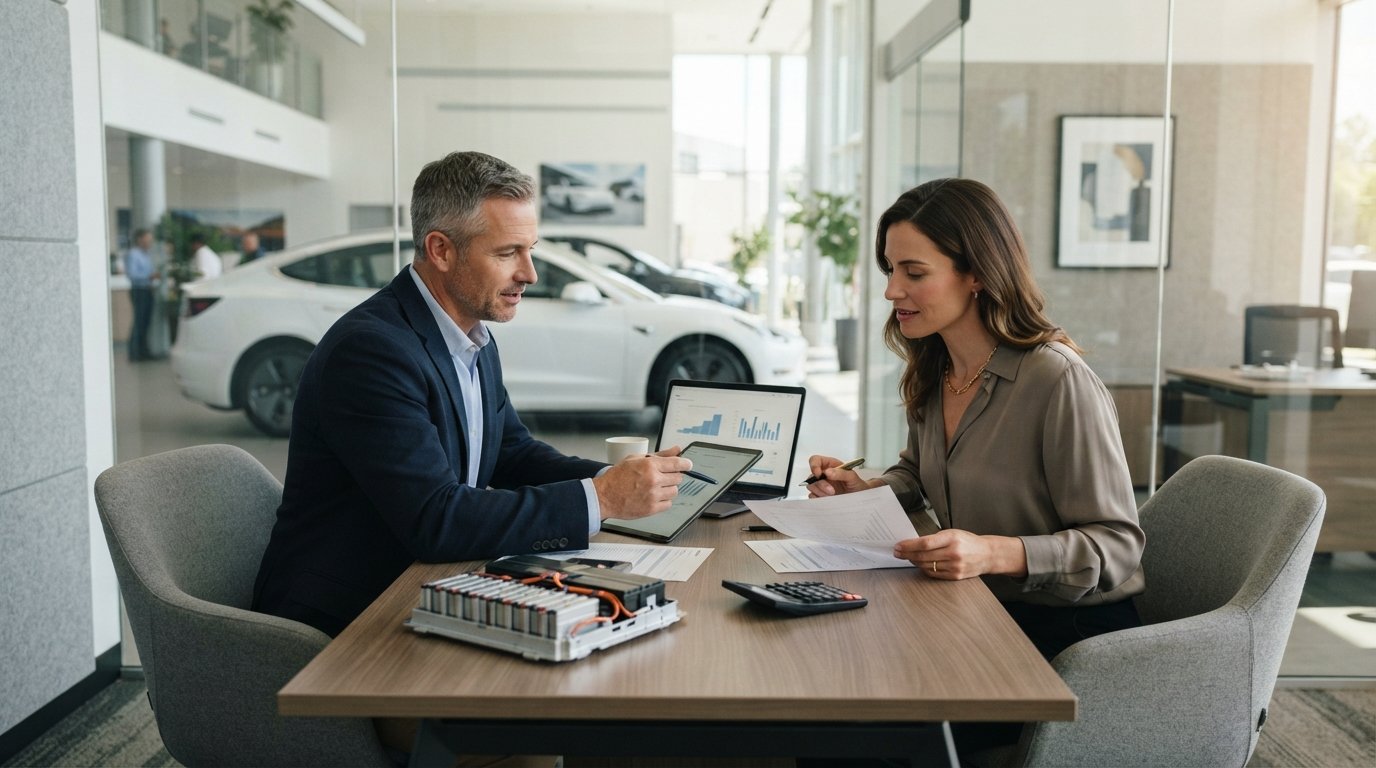
Buying an electric vehicle is not just a different shopping experience; it is a different financing experience. The sticker price, the federal tax credit, the battery warranty, and even the resale value all interact with your auto loan in ways that do not apply to a gas-powered car. Understanding how lenders evaluate EVs, how incentives affect your loan balance, and what costs sit outside the loan can save you hundreds of dollars over the life of the vehicle. This guide breaks down the key moving parts so you can approach an EV loan with the same confidence you would bring to a conventional car loan.
How Lenders Value EVs and Why Battery Age Matters
Lenders price risk based on collateral value, and an electric vehicle's collateral value is heavily influenced by its battery. Unlike an engine, a battery degrades gradually, and its replacement cost can be substantial. Lenders know this, and some adjust loan-to-value (LTV) limits or interest rates for used EVs with older batteries. A three-year-old EV with 80 percent battery health is viewed differently than a three-year-old sedan with a clean service history. Before you apply, check the battery health report if one is available, and be prepared to explain how the battery warranty transfers to you as the new owner.
Loan terms for EVs also vary by lender type. Some credit unions and online lenders have created specific EV loan programs with slightly longer terms or rate discounts, while others treat EVs like any other car. The key is to compare offers from multiple sources rather than assuming your current bank is the best fit. A longer term can lower your monthly payment, but it also increases total interest, so balance the two carefully. If you are considering a used EV, auto loan refinance options for electric vehicles can help you reset a high-rate loan after you have owned the car for a few months and improved your credit profile.
Federal and State EV Incentives: How They Interact with Financing
Federal tax credits are the most well-known incentive, but their timing matters for financing. A federal clean vehicle credit is generally claimed on your tax return, not at the point of sale, although some dealers now offer a point-of-sale transfer that effectively reduces the purchase price. If you take the credit at the dealership, the lender finances a smaller amount, which lowers your monthly payment and total interest. If you claim it later, you will need to carry the full purchase price on the loan and wait for the tax refund. Know which path your dealer supports before you sign.
State incentives add another layer. Some states offer rebates that arrive months after purchase, and those funds can be used to pay down the loan principal. Others provide reduced registration fees or sales tax exemptions that lower the amount you need to finance in the first place. Lenders do not typically count pending rebates as income or collateral, so do not expect them to approve a larger loan based on an expected rebate. Instead, treat any future incentive as a principal reduction opportunity. Here are the main incentive types to track:
- Federal clean vehicle tax credits (new and used, with income and price caps)
- State rebates for EV purchases or charging equipment
- Utility company rebates for home charger installation
- Sales tax exemptions or reduced registration fees in select states
- Point-of-sale dealer credits that reduce the financed amount
Each incentive has eligibility rules, and some require the vehicle to meet domestic assembly or battery sourcing requirements. Verify your specific make and model against current IRS guidance before assuming a credit applies. A lender will not adjust your loan terms based on an incentive you might receive, so build your budget around the actual amount financed rather than the hoped-for rebate.
Can You Refinance an EV Loan Later?
Yes, EV loans can be refinanced just like conventional auto loans. Refinancing replaces your current loan with a new one, ideally at a lower interest rate or with a shorter term. This is especially useful if you bought your EV when rates were higher or if your credit score has improved since the original purchase. Refinancing can also remove a co-borrower or change the payment date to better match your pay cycle. The process typically involves applying with a new lender, providing the vehicle identification number and current loan payoff, and completing the title transfer once approved.
One consideration unique to EVs is the vehicle's current value. If the resale value has dropped faster than your loan balance, you may owe more than the car is worth, which can make refinancing harder. Lenders will check the loan-to-value ratio, and some will not refinance if you are significantly upside down. Making extra principal payments before applying can improve your position. For a deeper walkthrough of the process, see our guide on auto loan refinance for electric vehicles, which covers eligibility, documentation, and timing.
Insurance and Charging Costs to Budget Alongside the Loan
Your monthly loan payment is only one part of EV ownership. Insurance premiums for EVs can be higher than for comparable gas cars because of specialized parts, higher repair costs, and battery replacement risk. Some insurers offer discounts for EVs, but you should compare quotes from multiple carriers to find the best rate. Charging costs also vary widely based on whether you charge at home or rely on public stations. Home charging is usually cheaper per mile, but installation of a Level 2 charger can cost several hundred to over a thousand dollars before incentives.
To keep your overall budget accurate, add these costs to your loan payment and compare the total against your current transportation spending. A useful approach is to list your expected monthly loan payment, insurance premium, home charging cost, and a maintenance reserve (EVs need less routine service, but tires and brakes still wear). If the total is higher than you expected, consider a larger down payment or a shorter loan term to reduce interest, or shop for free auto insurance quotes online to lower the insurance portion. Many drivers find that the fuel savings offset part of the higher insurance and charging costs, but the math depends on your daily mileage and local electricity rates.
Loan Considerations Specific to EV Financing
Before you apply, review these practical points that often trip up EV buyers. First, confirm whether the lender allows the federal tax credit to be applied at the point of sale, and if so, how that affects the loan amount and paperwork. Second, ask about gap insurance or loan protection products, which can be valuable if your EV depreciates quickly. Third, check whether the lender requires a home charging solution or specific warranty coverage. Finally, understand that some lenders may not finance older EVs or those with expired battery warranties, so have a backup lender in mind.
Your credit profile remains the biggest factor in the rate you receive. If your credit is imperfect, consider a credit union or an online lender that specializes in a broad credit spectrum. Getting pre-qualified with multiple lenders within a short window can help you compare offers without hurting your score much. Be cautious with dealer-arranged financing, which can be convenient but may include a higher rate. Always ask for the annual percentage rate (APR) and the total finance charge, not just the monthly payment.
Finally, think about the loan term in relation to battery life. A seven-year loan on an EV with an eight-year battery warranty may leave you with payments after the warranty expires, which is a risk if the battery degrades faster than expected. A shorter term or a larger down payment reduces that risk. If you plan to keep the car long-term, a five-year loan is often a balanced choice. If you prefer lower payments and plan to refinance later, a longer term can work, but you should have a clear plan to refinance before the vehicle value drops too far.
Electric vehicle financing rewards preparation. By understanding how lenders view battery health, timing your incentives correctly, and budgeting for insurance and charging, you can secure a loan that fits your actual cost of ownership. Take the time to compare offers and read the fine print, and you will be in a stronger position to enjoy the savings and driving experience that an EV offers.