
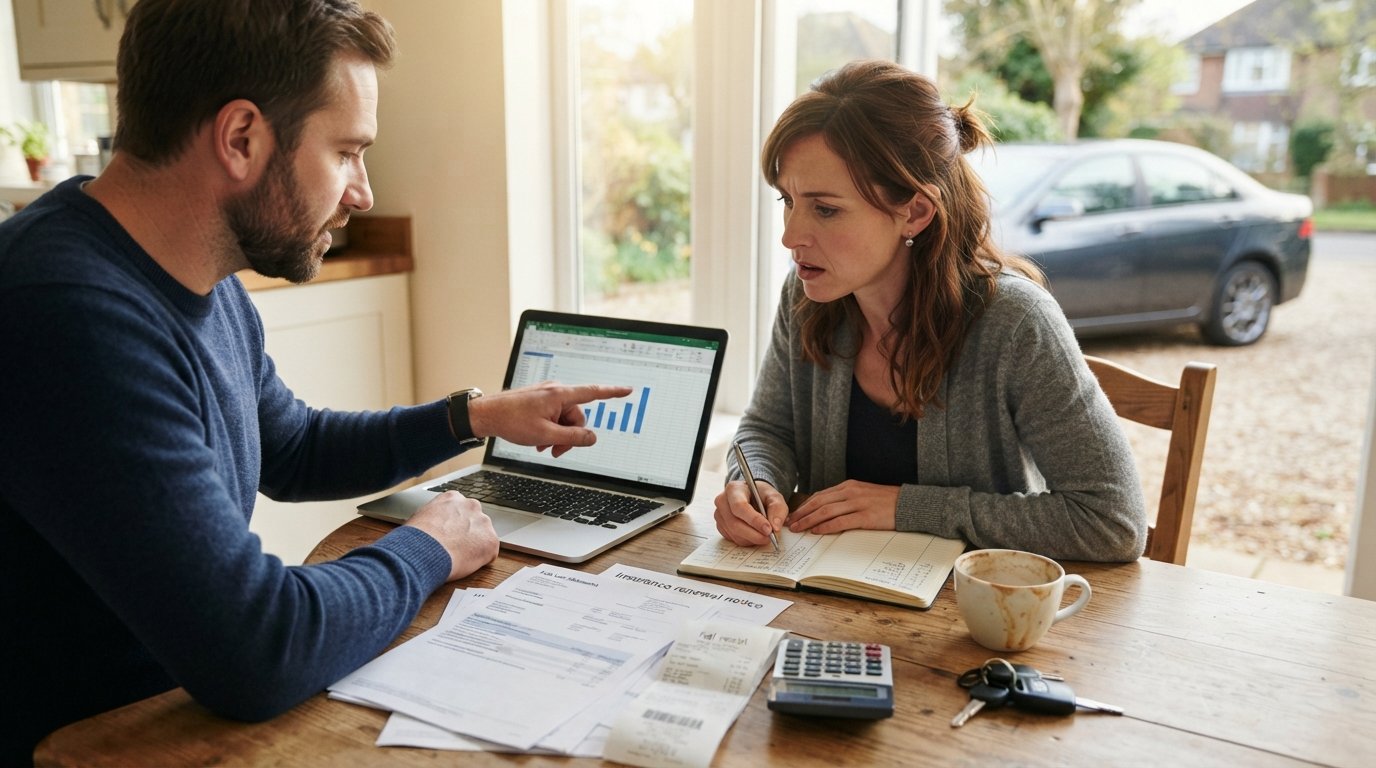
Budgeting for Car Ownership Costs Beyond Payment
Budgeting for car ownership costs beyond payment means planning for insurance, fuel, maintenance, and depreciation so surprise bills never wreck your finances.
By Brandon Walker
The monthly payment is the number most buyers fixate on, and it is the number dealerships and lenders are most willing to negotiate around. Yet the sticker on the window and the figure on the loan contract tell only part of the story. Real car ownership is a bundle of recurring and one-time expenses that quietly accumulate over years, and owners who plan for only the payment often find themselves surprised by insurance renewals, repair invoices, and depreciation they never factored in. The good news is that these costs are predictable. With the right framework, you can estimate them before you sign and build a budget that keeps your total cost of ownership under control instead of letting it control you.
Why the Monthly Payment Is a Misleading Number
Lenders sell monthly payments because they are easy to compare and easy to say yes to. A breakdown of the true cost of car ownership beyond your monthly payment makes clear that the loan itself is often less than half of what a vehicle actually costs to run. The payment covers principal and interest, but it says nothing about fuel, tires, registration, or the fact that a car loses value every single day it sits in your driveway.
Consider two buyers with identical $450 payments. One drives a fuel-efficient sedan with cheap insurance and a strong reliability record. The other drives a larger vehicle with higher fuel consumption, higher premiums, and a reputation for expensive repairs. Over five years, the second buyer could spend tens of thousands of dollars more, even though both signed loans with the same monthly figure. That gap is exactly why budgeting for car ownership costs beyond payment matters: it turns a single line item into a complete financial picture.
The fix is not complicated, but it requires discipline. You need to convert every ownership expense into a monthly equivalent, add them to the loan payment, and compare that total against your take-home income. Once you see the real number, you can decide whether a particular vehicle is genuinely affordable or just looks affordable on the dealer's worksheet.
The Major Cost Categories Every Owner Should Track
Ownership costs fall into a handful of buckets, and each behaves differently. Some are fixed, some scale with how much you drive, and some arrive unpredictably. Understanding the categories is the first step toward building a realistic budget.
- Loan payment: Principal plus interest, paid monthly until the loan is retired.
- Insurance: Premiums for collision, comprehensive, and liability coverage, usually paid monthly or every six months.
- Fuel: Gas or electricity, which scales directly with miles driven and local energy prices.
- Maintenance and repairs: Oil changes, tires, brakes, batteries, and unexpected mechanical failures.
- Taxes, registration, and fees: Annual or biennial charges that vary by state and vehicle value.
- Depreciation: The silent cost of your car losing value over time, which matters most when you sell or trade in.
Each of these deserves its own line in your budget, because lumping them together hides the ones that hurt most. Depreciation, for example, never sends you an invoice, yet it can easily exceed every other cost combined during the first few years of ownership. Insurance and fuel are visible every month, so they tend to get attention. Maintenance is the category people underestimate most often, because a transmission failure or a cracked radiator does not care whether you planned for it.
A useful exercise is to write down every car-related expense you paid over the past twelve months, then divide by twelve. Most owners are shocked by the result. That single number is your real monthly cost of ownership, and it is the figure you should use when comparing vehicles or deciding whether to refinance.
How to Estimate Costs Before You Buy
Estimating ahead of time is far easier than most people assume. Start with the loan itself: use an online calculator to determine the monthly payment for the price, term, and interest rate you expect. Then layer in the other categories using conservative assumptions rather than optimistic ones.
For insurance, get actual quotes for the specific make, model, and trim you are considering. Rates vary dramatically between vehicles, and a sports car can cost two or three times as much to insure as a midsize sedan. For fuel, estimate your annual mileage, divide by the vehicle's combined fuel economy, and multiply by the current price per gallon. For maintenance, a reasonable rule is to set aside a percentage of the vehicle's value each year, plus a separate emergency fund for major repairs. For taxes and registration, check your state's fee schedule, which is often based on vehicle value or weight.
- Calculate the loan payment using the expected rate and term.
- Obtain real insurance quotes for the exact vehicle.
- Estimate annual fuel cost from mileage and fuel economy.
- Set aside a maintenance reserve based on vehicle age and reliability.
- Add registration, taxes, and any parking or toll costs.
Once you have those five numbers, add them together and compare the total to your monthly budget. A common guideline is to keep total transportation costs below 15 to 20 percent of your take-home pay. If the total exceeds that range, either choose a less expensive vehicle, extend your shopping timeline, or plan to refinance later once your credit profile improves.
Building a Monthly Ownership Budget That Actually Works
A budget only works if it reflects reality. The most effective approach is to create a dedicated car account and fund it every payday with the full monthly ownership cost, not just the loan payment. When insurance comes due or a repair pops up, the money is already there. This single habit eliminates most of the financial stress that comes with car ownership.
Divide the budget into predictable and unpredictable categories. Predictable costs include the loan payment, insurance, and registration. Unpredictable costs include repairs, tires, and unexpected breakdowns. Fund the predictable items automatically, and treat the unpredictable ones as a sinking fund that grows a little each month. A reasonable target is to accumulate one to two months of ownership costs in reserve within the first year.
Review the budget annually or whenever a major life change occurs. Insurance rates shift, fuel prices fluctuate, and a car that was cheap to maintain at 40,000 miles may become expensive at 100,000 miles. Adjusting your budget once a year keeps it accurate and prevents small oversights from becoming large problems.
Where Refinancing Fits Into the Ownership Equation
Refinancing does not reduce fuel, insurance, or maintenance costs, but it can free up cash that makes the rest of the budget easier to manage. If your credit has improved since you bought the car, or if interest rates have fallen, replacing your current loan with a lower-rate one can cut your monthly payment and reduce the total interest you pay over the life of the loan. That savings can be redirected into a maintenance fund or used to pay down the principal faster.
Refinancing is especially valuable for owners who accepted a high rate because of past credit challenges. Many people who were rejected by traditional lenders at purchase time qualify for better terms after twelve to eighteen months of on-time payments. Platforms such as StartAutoLoan connect borrowers with financing options even when their credit history is imperfect, which makes it easier to explore whether a refinance makes sense. The key is to run the numbers: compare your current payment and remaining interest against the new offer, and only proceed if the savings clearly outweigh any fees.
It also helps to think of refinancing as part of a broader ownership strategy rather than a one-time event. Every year or two, check whether your current loan still matches your financial situation. If your credit has improved, your income has grown, or rates have dropped, a refinance could reduce your total cost of ownership without requiring you to change vehicles.
Depreciation: The Cost Nobody Talks About
Depreciation is the difference between what you paid for a car and what it is worth when you sell or trade it. New vehicles typically lose a significant portion of their value in the first year, and the decline continues steadily afterward. This cost never appears on a monthly statement, which is precisely why it is so easy to ignore.
You can manage depreciation by choosing vehicles with strong resale values, buying slightly used instead of brand new, and keeping the car long enough to spread the initial loss over many years. A car driven for a decade costs far less per year in depreciation than one traded in every three years. When you compare two vehicles, estimate what each will be worth in five years and factor that difference into your total cost calculation.
Depreciation also affects refinancing decisions. If you owe more than the car is worth, refinancing becomes harder because lenders prefer to finance vehicles with positive equity. Keeping your loan term aligned with the vehicle's useful life, and avoiding extremely long terms, helps you stay ahead of the depreciation curve.
Insurance, Fuel, and Maintenance: The Recurring Trio
These three categories account for most of the day-to-day cost of ownership, and each offers opportunities to save. Insurance premiums depend on your driving record, credit-based insurance score, location, vehicle type, and coverage choices. Raising your deductible, bundling policies, and shopping quotes annually can reduce premiums meaningfully without sacrificing essential coverage.
Fuel costs depend on how you drive as much as what you drive. Smooth acceleration, proper tire inflation, and removing unnecessary weight from the vehicle all improve fuel economy. If you commute long distances, the difference between a vehicle that gets 25 miles per gallon and one that gets 35 can add up to hundreds of dollars a year.
Maintenance is the category where planning pays the highest dividends. Following the manufacturer's service schedule, addressing small issues before they become large ones, and setting aside money for tires and brakes keeps repair bills predictable. A car that receives regular oil changes and timely brake service will almost always cost less to own over its lifetime than one that is neglected until something breaks.
Putting It All Together
Budgeting for car ownership costs beyond payment is ultimately about seeing the whole picture before it sees you. The loan payment is the entry point, not the destination. By estimating insurance, fuel, maintenance, taxes, and depreciation in advance, funding a dedicated car account, and reviewing your budget regularly, you can turn a potentially stressful expense into a manageable one.
Refinancing can play a supporting role by lowering your interest cost and freeing up cash flow, but it works best when it is part of a larger plan. Whether you are shopping for a first car, considering a trade-in, or simply trying to get a better handle on what you already drive, the same principle applies: know your real number, plan for it, and adjust as life changes. Owners who do this consistently are the ones who avoid surprise bills and keep their transportation costs in line with their goals.