
The True Cost of Car Ownership Beyond Monthly Payment
The true cost of car ownership beyond monthly payment can run 60 to 100 percent higher than the loan. See the seven hidden costs and how to shrink them.
By Micheal Thompson
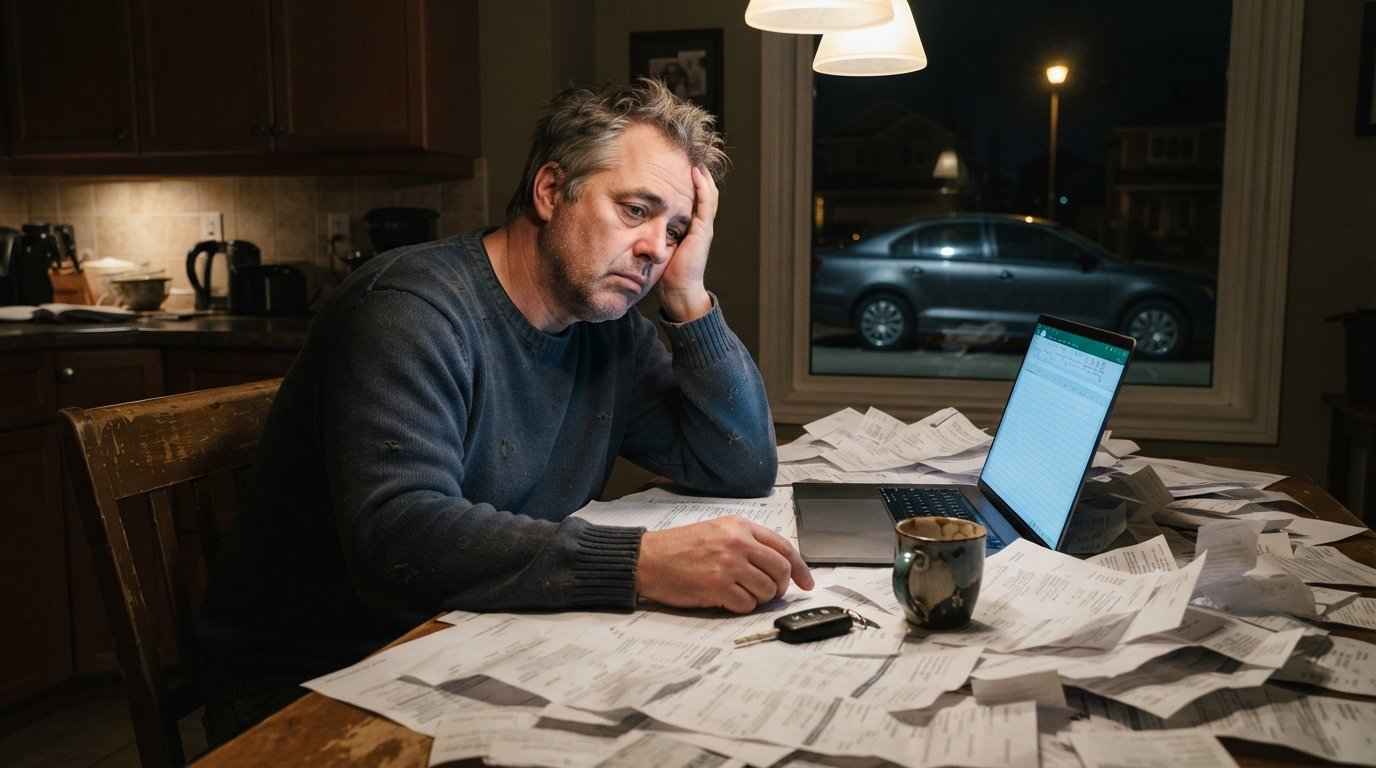
You did the math before you signed. You knew the monthly payment, you knew the term, and you knew it fit your budget. Then the first year passed and your bank account told a different story. The payment was never the whole bill. It was just the most visible line on a much longer receipt, and that receipt keeps growing for as long as you hold the keys.
This gap between the sticker payment and the real outflow is where most car owners lose money without noticing. Fuel, insurance, maintenance, depreciation, taxes, and opportunity costs all stack on top of the loan, and together they can easily add 60 to 100 percent to what the car actually costs you each month. Understanding the true cost of car ownership beyond monthly payment is the difference between owning a vehicle that fits your life and owning one that quietly drains it.
Why the Monthly Payment Is a Marketing Number
Dealerships and lenders know that buyers anchor on the monthly figure. That is why so many sales conversations revolve around "what payment are you comfortable with" instead of "what is the total price." A longer term spreads the same balance across more months, which makes the payment smaller while the interest bill grows larger. A lower trim level, a bigger down payment, or a higher interest rate can all be hidden behind a payment that looks reasonable.
The payment itself is only the loan portion of ownership. It says nothing about what the car will cost to keep alive, insure, register, and eventually replace. Treating the payment as the budget is like pricing a house by the doorknob. It is part of the picture, but it is nowhere near the whole picture.
The Seven Hidden Costs That Follow Every Car
Once you move past the loan, the true cost of car ownership beyond monthly payment becomes a stack of recurring and one-time expenses. Most owners can name two or three. Very few track all seven.
- Depreciation: A new car typically loses 20 percent of its value in the first year and roughly 60 percent over five years. That loss is real money even though no invoice arrives for it.
- Insurance: Full coverage on a financed vehicle can run $1,500 to $2,500 or more per year depending on age, credit, location, and driving record.
- Fuel: At 12,000 miles per year and $3.50 per gallon, a 30 mpg car costs about $1,400 annually, and a 20 mpg car costs over $2,100.
- Maintenance and repairs: Oil changes, tires, brakes, batteries, and unexpected fixes average $500 to $1,200 per year, with spikes after the warranty ends.
- Registration, taxes, and fees: Annual registration, property tax in some states, inspection, and title fees add several hundred dollars per year.
- Financing costs: Interest and fees on the loan itself, which can total thousands over the life of the term.
- Opportunity cost: The money tied up in a depreciating asset that could have been invested, saved, or used to pay down higher-interest debt.
Add those together and a $450 monthly payment can easily represent $850 to $1,000 in real monthly cost. That is the number that should drive your decision, not the one printed on the contract.
How to Calculate Your Real Monthly Cost
The good news is that the math is simple once you know which inputs to gather. Start with your actual monthly payment, then layer in the recurring costs using real numbers from the past twelve months rather than estimates. If you have only owned the car for a few months, use annual averages and adjust upward for the first year of ownership, which tends to carry higher registration and depreciation hits.
Here is a practical framework you can run in about ten minutes:
- Add your monthly loan payment, including any required gap insurance or warranty add-ons.
- Divide your annual insurance premium by 12 and add it.
- Estimate monthly fuel using your average miles and your car's real mpg, not the EPA sticker.
- Set aside a maintenance fund of at least $75 to $100 per month, even on a reliable car.
- Divide annual registration, taxes, and inspection fees by 12 and add them.
- Subtract any expected resale value from the original price, divide by the number of months you plan to keep the car, and treat that as a monthly depreciation cost.
Once you see the total, compare it to your take-home pay. Financial planners often suggest keeping total transportation costs under 15 percent of monthly take-home income. If your real number is closer to 25 or 30 percent, the car is quietly crowding out savings, debt payoff, and emergency funds.
Why Depreciation Deserves Its Own Conversation
Depreciation is the largest single cost of ownership for most new vehicles, and it is also the easiest to ignore because it never appears on a statement. A $35,000 car that is worth $14,000 after five years has cost you $21,000 in value alone, which works out to $350 per month before you have paid a dime of interest, insurance, or fuel.
This is why buying slightly used, or keeping a car longer than the loan term, changes the math so dramatically. The steepest depreciation happens in the first two to three years, which is exactly when many buyers trade in and restart the cycle. Breaking that cycle, even by two extra years, can free up thousands of dollars that would otherwise vanish into the next down payment.
Financing Choices That Change the Total
The loan structure you choose does not just affect the payment. It affects how much of your money goes to interest, how long you are upside down on the vehicle, and how much flexibility you have if your situation changes. A 72 or 84 month term lowers the payment but raises the total interest and stretches the period during which the car is worth less than the loan balance.
If you already have a loan with a rate that no longer matches your credit profile, refinancing is one of the few levers that can reduce the true cost without changing the car. In our guide on how monthly payments are calculated, we break down how rate, term, and principal interact so you can see exactly where the savings come from. Even a two-point rate reduction on a $25,000 balance can save well over $1,000 across a three-year remaining term.
Shopping multiple lenders is the other half of the equation. Credit unions, banks, and online lenders all price risk differently, and the spread between the highest and lowest offer for the same borrower can be several percentage points. An independent platform like StartAutoLoan connects borrowers with a network of financing options, which is especially useful for buyers who have been turned down elsewhere or who are rebuilding credit after bankruptcy.
Insurance, Credit, and the Cost You Do Not See
Insurance pricing is tied to credit-based insurance scores in most states, which means the same driver with the same car can pay wildly different premiums depending on their credit history. That is one more reason the true cost of car ownership beyond monthly payment is not a fixed number. It is a number that moves with your financial behavior.
Raising a deductible, bundling home and auto, and re-shopping coverage every 12 to 18 months are simple ways to pressure insurers without sacrificing protection. On a financed car, though, you will usually be required to carry full coverage, so the leverage is in the shopping, not in dropping coverage.
Maintenance Reserves: The Cost That Bites Late
New cars hide their maintenance costs behind warranties. Used cars do not. The average driver spends $500 to $1,200 per year on maintenance and repairs, and that figure spikes when a car crosses 100,000 miles or when a major component fails without warning. A transmission replacement can run $4,000 or more, which is more than many owners have set aside.
The fix is boring but effective: treat maintenance as a fixed monthly expense, not a surprise. A dedicated savings account funded with $75 to $150 per month turns a $2,000 repair into a planned withdrawal instead of a credit card balance that then accrues interest for years.
Opportunity Cost and the Invisible Bill
Every dollar tied up in a car is a dollar not working somewhere else. If your real ownership cost is $900 per month and $400 of that is depreciation and interest, you are effectively paying $400 monthly for the privilege of holding a declining asset. Invested instead at a modest 7 percent return, that same $400 would grow to roughly $28,000 over five years.
That does not mean cars are bad purchases. Reliable transportation enables income, safety, and quality of life. It means the decision deserves the same scrutiny as any other major financial commitment, and that the cheapest car that meets your needs is often the most expensive one to ignore.
Practical Steps to Bring the True Cost Down
You cannot eliminate ownership costs, but you can compress them. The most effective moves tend to be structural rather than cosmetic: change the loan, change the car, or change how long you keep it. Small habit changes help at the margins, but the big savings live in the financing and the depreciation curve.
- Refinance an existing loan if your credit has improved since you bought, especially if your rate is above 7 percent.
- Shorten the term only if the payment stays comfortably within 15 percent of take-home pay.
- Buy a two to three year old vehicle instead of new to let someone else absorb the steepest depreciation.
- Keep the car two years past the loan payoff and redirect the old payment into savings or debt payoff.
- Re-shop insurance and consider a higher deductible if you have an emergency fund to cover it.
Each of these steps changes the total by hundreds or thousands of dollars over the life of the vehicle. Combined, they can turn a car that costs $1,000 per month into one that costs $650, without giving up reliability or safety.
Building a Real Ownership Budget
The final step is to write the real number down and treat it like any other fixed expense. Add your payment, insurance, fuel, maintenance reserve, and annual fees into a single monthly figure. Compare it to your income, your savings goals, and your other debts. If the number is uncomfortable, you now have the information to act, whether that means refinancing, downsizing, or simply keeping the current car longer.
Awareness alone will not lower the cost, but it changes every future decision. The next time a salesperson asks what monthly payment you want, you will know the real answer, and it will be based on the true cost of car ownership beyond monthly payment rather than the number that fits neatly on a contract.