
Auto Refinance for Gig Workers and Variable Income
Gig workers with variable income can refinance their auto loan. Learn how to verify income, present a stable DTI, and time your application to save money.
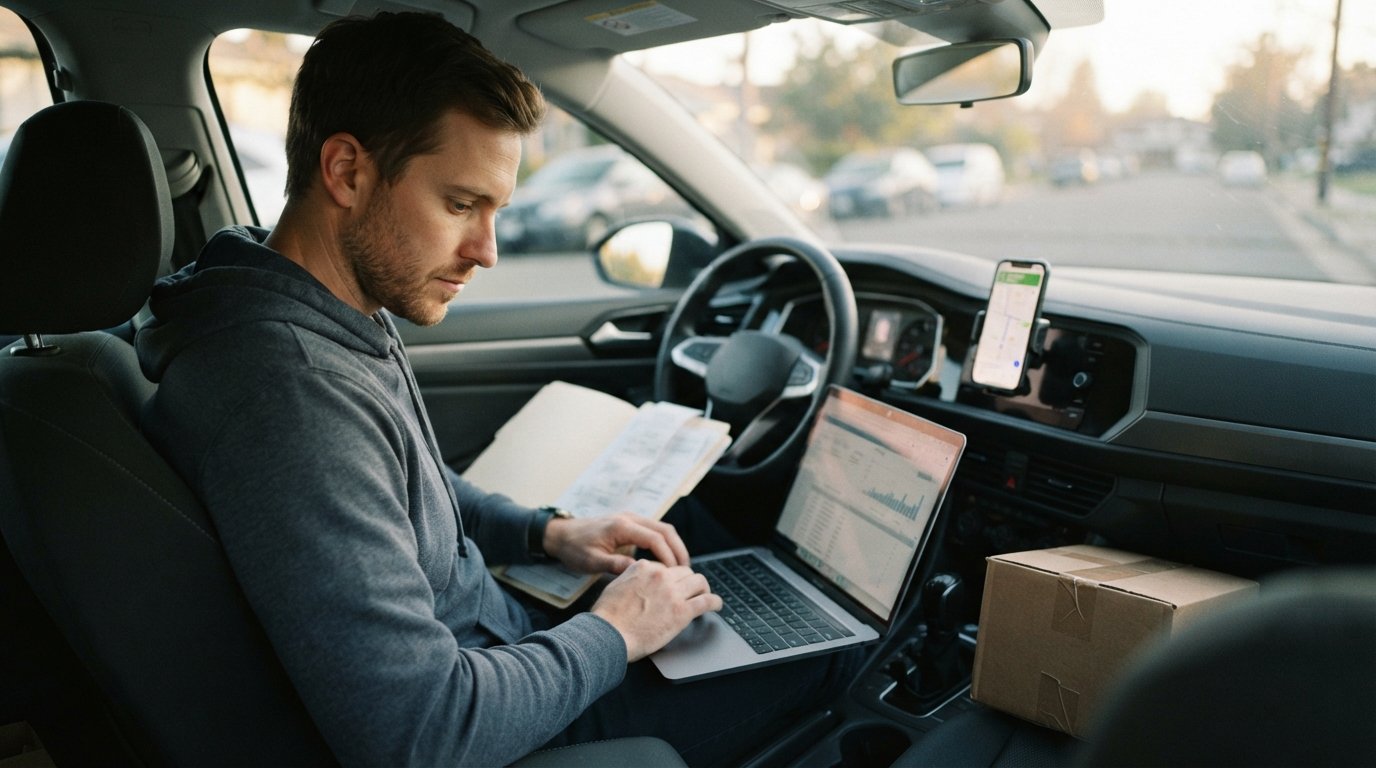
If you drive for a rideshare company, deliver packages, or freelance as a consultant, your income can swing wildly from one month to the next. That unpredictability often makes lenders nervous, especially when you want to refinance your car loan. But here is the good news: auto refinance for gig workers and variable income is not only possible, it is increasingly common. Lenders have adapted to the modern workforce, and with the right documentation and strategy, you can secure a lower rate or a more manageable payment. This guide walks you through exactly how to do it, from proving your income to timing your application around your best months.
Why Lenders Care About Variable Income (And How to Reassure Them)
Traditional lenders built their underwriting models around W-2 employees who earn a predictable salary. When they see gig income, their first concern is consistency: will you be able to make payments if your earnings drop? They also worry about documentation, since gig workers often lack pay stubs. But the rise of the gig economy has forced many lenders to update their policies. According to a 2025 report from the Consumer Financial Protection Bureau, more than one in ten auto loan applicants now report some form of self-employment or gig income. Lenders have responded by developing more flexible verification methods.
To reassure a lender, you need to demonstrate that your income, while variable, is reliable enough to cover your obligations. That means showing a track record (typically 12 to 24 months), maintaining a healthy bank account history, and presenting a clear debt-to-income ratio that accounts for your average earnings. The key is to make your financial life look as stable as possible on paper, even if your day-to-day work is anything but predictable.
One helpful resource is our guide on auto refinance for older cars eligibility, which explains how vehicle age affects approval. But for gig workers, the bigger hurdle is income verification, which we cover next.
How Lenders Verify Gig and Freelance Income for Refinancing
Gone are the days when a simple pay stub was the only proof of income. Lenders now accept a variety of documents to verify gig and freelance earnings. The specific requirements vary by lender, but most will ask for at least two of the following:
- Bank statements: Typically 12 to 24 months of personal or business bank statements showing consistent deposits from gig platforms or clients.
- Tax returns: Your most recent two years of federal tax returns, including Schedule C or Schedule SE if you are self-employed.
- 1099 forms: If you receive 1099s from platforms like Uber, Lyft, DoorDash, or Upwork, these can serve as proof of income.
- Profit and loss statements: A CPA-prepared or self-prepared P&L statement that summarizes your income and expenses over a period.
- Platform earnings summaries: Many gig platforms provide annual or monthly earnings summaries that lenders may accept.
Some lenders use third-party income verification services like Plaid or Yodlee to analyze your bank transactions directly. These tools can automatically categorize gig deposits and calculate an average monthly income, which speeds up the process and reduces paperwork. If your lender offers this option, take it: it often leads to faster approvals and can smooth over irregular deposit patterns.
It is also worth noting that some lenders will average your income over the past 12 to 24 months, rather than looking at your most recent month. This works in your favor if you had a few slow months but a strong overall year. When you apply, ask the loan officer how they calculate variable income, because the method can significantly affect your approved loan amount and rate.
Which Income Documents Strengthen a Variable-Income Application
Not all income documentation is created equal. To put your best foot forward, prioritize documents that show consistency and longevity. Here is a hierarchy of strength, from most to least persuasive:
- Two years of tax returns with steady or growing income: This is the gold standard. It shows the lender that your gig work is not a flash in the pan and that you have a history of earning enough to cover your debts.
- 12 months of bank statements with regular deposits: If you do not have two years of tax returns (perhaps you started gig work recently), bank statements can fill the gap. Lenders look for recurring deposits from known gig platforms or clients.
- Platform earnings summaries plus 1099s: These are helpful, but they are stronger when combined with bank statements that show the money actually hitting your account.
- Profit and loss statement: A P&L is useful for freelancers with multiple clients, but it carries less weight than tax returns because it is self-reported.
If you have a mix of gig income and traditional employment, include both. A part-time W-2 job can bolster your application by showing a stable baseline. Similarly, if you have savings or other assets, mention them: some lenders consider cash reserves as a compensating factor for variable income.
One mistake many gig workers make is submitting too many documents, hoping something will stick. Instead, be selective. Provide the strongest evidence first, and be prepared to supply additional documents if the lender asks. A clean, organized application with clear labeling (for example, "Uber earnings 2024" or "Freelance client invoices Q1 2025") makes the underwriter's job easier and can speed up approval.
Presenting a Stable Debt-to-Income Picture
Your debt-to-income ratio (DTI) is one of the most important numbers in any loan application. It is calculated by dividing your total monthly debt payments by your gross monthly income. Lenders typically prefer a DTI below 36%, though some auto lenders will go up to 50% for borrowers with strong credit or other compensating factors. For gig workers, the challenge is that income varies, so your DTI can fluctuate month to month.
To present a stable DTI, start by calculating your average monthly income over the past 12 to 24 months. Use your tax returns or bank statements to get an accurate figure. Then, list all your monthly debt obligations: rent or mortgage, credit card minimums, student loans, personal loans, and the auto loan you want to refinance. Divide total debt by average income to get your DTI.
If your DTI is higher than you would like, there are several steps you can take before applying:
- Pay down credit card balances: Reducing revolving debt lowers your minimum payments and improves your DTI.
- Avoid new credit inquiries: Do not open new credit cards or take on new loans right before applying for refinancing.
- Increase your income documentation: If you have side gigs that you have not reported on your tax returns, consider filing an amended return or providing additional 1099s to show a higher income.
- Choose a longer loan term: Refinancing to a longer term can lower your monthly payment, which improves your DTI, but be aware that you will pay more interest over the life of the loan.
Another strategy is to apply with a co-borrower who has stable W-2 income. This can dramatically improve your DTI and increase your chances of approval, though it also means sharing responsibility for the loan. If you go this route, make sure both parties understand the terms and that the co-borrower's credit is also strong.
Keep in mind that lenders may calculate your DTI differently. Some use a "back-end" DTI that includes housing costs, while others use a "front-end" DTI that only considers the auto loan and other non-housing debts. Ask the lender which method they use so you can present your finances accordingly.
Timing Your Refinance Around High and Low Income Months
Because your income fluctuates, the timing of your refinance application can make a real difference. Ideally, you want to apply after a period of strong earnings, when your bank statements and tax returns show higher average income. If you had a particularly lucrative quarter, wait until those deposits have seasoned for at least two to three months before applying. This gives lenders a clear picture of your earning potential.
Conversely, avoid applying right after a slow season. If you are a rideshare driver in a tourist town, for example, your income might dip in the off-season. Applying during that dip could result in a lower approved loan amount or a higher interest rate. Plan ahead: if you know a busy season is coming, start gathering documents now and submit your application shortly after the busy period ends.
Another timing consideration is your credit score. If you are working on improving your credit, wait until you have seen a meaningful increase before applying. Even a 20-point bump can translate into a lower rate. You can monitor your credit for free through many apps and services, and some lenders offer pre-qualification with a soft credit pull that does not affect your score.
Finally, think about your current loan's terms. If you are near the end of your loan term, refinancing may not be worth the fees and hassle. But if you still have two or more years left and your credit or income has improved, refinancing could save you hundreds or even thousands of dollars over the remaining term. Use our free calculator to estimate your potential savings, and consider applying when your financial picture looks strongest.
Building a Strong Application Package
When you are ready to apply, treat it like a job interview: preparation is key. Start by pulling together the documents we discussed earlier: tax returns, bank statements, 1099s, and any platform earnings summaries. Organize them in a folder, either digital or physical, so you can upload or submit them quickly. Write a brief cover letter explaining your work situation, especially if your income pattern is unusual. For example, if you took three months off to care for a family member but have since returned to full-time gig work, explain that gap.
Next, get pre-qualified with several lenders. Pre-qualification typically involves a soft credit check and gives you an estimate of the rate and terms you might qualify for. It is a low-risk way to shop around without dinging your credit score. Compare offers side by side, paying attention not just to the interest rate but also to fees, loan terms, and any prepayment penalties. Remember that CarLoanRefinancing.com is not a lender; we connect you with a network of lending partners who may offer competitive rates. You can start your free, no-obligation application on our get-a-quote page.
While you are shopping for a refinance, it is also a good time to review your auto insurance. You might be able to save money by comparing quotes from multiple carriers. One resource is FreeAutoInsuranceQuotesOnline, which provides free, no-obligation quotes from multiple insurers. Lowering your insurance premium can free up cash flow and improve your overall financial picture, which in turn strengthens your refinance application.
Finally, be honest with the lender. If your income is variable, say so, and provide the documentation to back it up. Lenders appreciate transparency, and hiding income fluctuations can lead to denial or, worse, accusations of fraud. If you have a solid explanation for a dip in income and can show a plan for recovery, most underwriters will work with you.
Common Pitfalls to Avoid
Even well-prepared gig workers can stumble during the refinance process. One common mistake is overestimating income on the application. Always use the figures from your tax returns or bank statements, not your best month ever. Another pitfall is neglecting to include all debts. If you have a buy-now-pay-later plan or a personal loan you forgot about, it will show up on your credit report and could throw off your DTI. Be thorough and list everything.
Another issue is applying with too many lenders at once. While shopping around is smart, each hard credit inquiry can ding your score by a few points. To minimize the impact, do all your rate shopping within a two-week window; credit scoring models typically treat multiple inquiries within that period as a single inquiry. Also, avoid applying for new credit cards or car loans during the refinance process, as this can make you look riskier to lenders.
Finally, do not ignore the fine print. Some refinance offers come with origination fees, prepayment penalties, or variable interest rates that can rise over time. Read the loan agreement carefully and ask questions if anything is unclear. A reputable lender will be happy to explain the terms. If an offer seems too good to be true, it probably is.
Refinancing your auto loan as a gig worker with variable income takes some extra effort, but it is well within reach. By understanding how lenders verify income, presenting a stable DTI, and timing your application strategically, you can improve your chances of approval and potentially save money. Start by gathering your documents and checking your credit, then explore offers from multiple lenders. With a little preparation, you can turn your variable income into a strength rather than a hurdle.