
Can You Refinance a Car Loan If You Are Unemployed?
Can you refinance a car loan if you are unemployed? Yes, with the right lender, co-signer, or income proof. Learn how to qualify and save money.
By Amanda Brooks
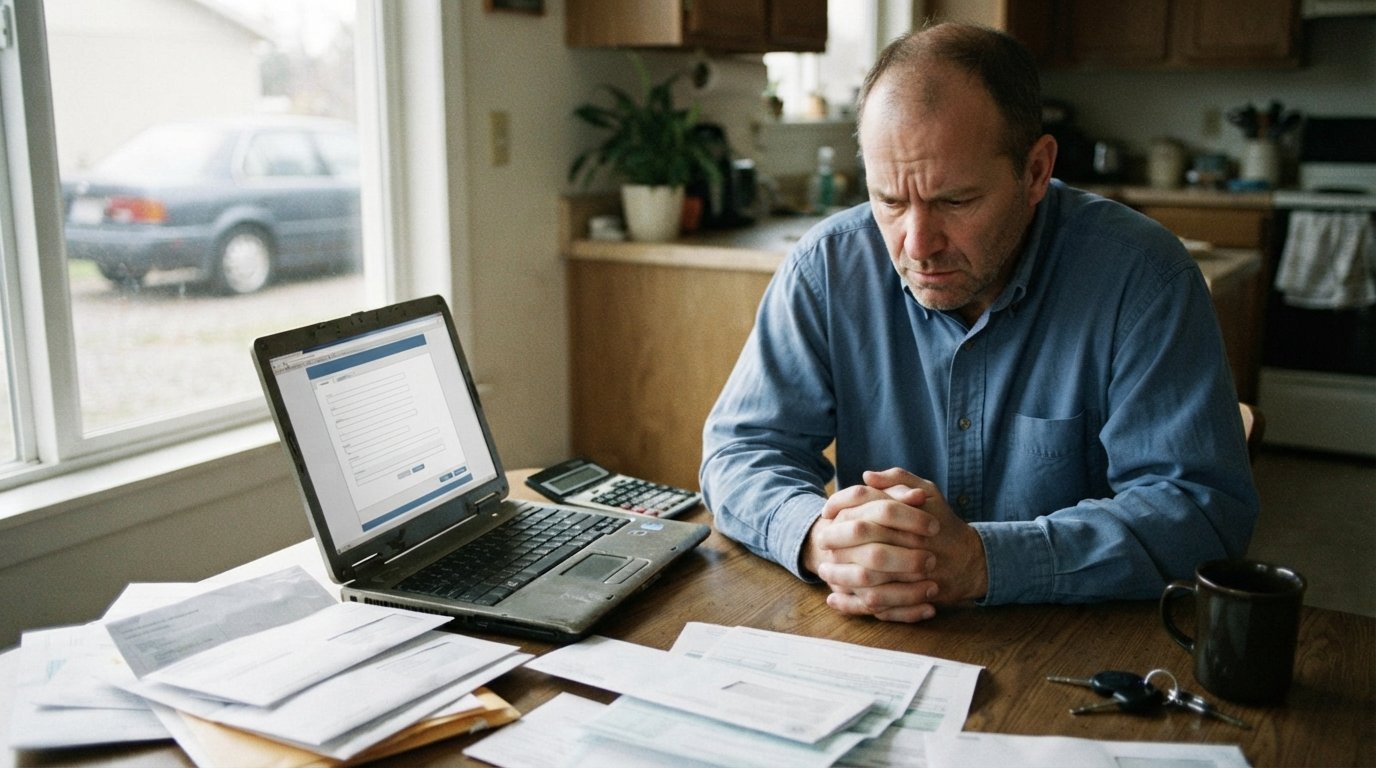
Losing a job can feel like the ground shifting beneath you. Suddenly, every monthly bill looks larger, and the car payment that once felt manageable now competes with groceries, rent, and utilities. If you are in this position, you may be wondering: can you refinance a car loan if you are unemployed? The short answer is that it is possible, but it is far from automatic. Lenders care about one thing above all else when reviewing a refinance application: your ability to repay the new loan. Without a paycheck, proving that ability becomes the central challenge. Still, unemployment does not automatically disqualify you. There are paths forward, and understanding how lenders think is the first step toward finding one that works for your situation.
Why Employment Matters to Refinance Lenders
When you apply to refinance a car loan, you are essentially asking a new lender to pay off your existing loan and replace it with a new one on different terms. The new lender takes on the risk that you might stop paying. To manage that risk, lenders look at two broad categories: your credit profile and your income. Employment sits at the heart of the income question because a steady job is the most common way people demonstrate they can handle monthly payments.
This does not mean lenders are being unreasonable. A refinance is a fresh loan, and the lender has no history with you. They cannot see your good intentions; they can only see documentation. Pay stubs, W-2s, and bank statements showing regular deposits are the standard proof. When those documents are missing, the lender has to rely on other signals, and many simply choose not to move forward. That is why unemployment creates friction, even for borrowers with excellent credit.
However, the picture is more nuanced than a simple yes or no. Some lenders specialize in non-traditional situations. Others may accept a co-signer, alternative income documentation, or a larger down payment to offset risk. Your existing relationship with a credit union or bank can also matter. The key is to understand which lenders are open to your situation before you start applying, because each application typically triggers a credit inquiry.
What Counts as Income When You Are Unemployed
Unemployment does not always mean zero income. Many people who have lost a job still receive money from other sources, and some of those sources can satisfy a lender. The trick is knowing which types of income carry weight and which do not. Lenders generally want to see income that is verifiable, ongoing, and likely to continue at least through the early months of the new loan.
Here are common income sources that some lenders may consider, depending on their internal guidelines:
- Unemployment benefits: These are temporary by definition, so many lenders exclude them, but a few may count them if you can show a consistent deposit history.
- Disability payments: Long-term disability or Social Security Disability Insurance (SSDI) is often treated as stable income because it does not end after a set number of weeks.
- Retirement or pension income: Regular distributions from a 401(k), IRA, or pension can function like a paycheck for qualification purposes.
- Freelance or gig work: Income from driving, delivery, consulting, or online sales can count if you have a track record and can document it through bank deposits or 1099 forms.
- Investment or rental income: Dividends, interest, and rent from a property you own may be accepted, especially if the amounts are steady.
Notice that the common thread is consistency and documentation. A one-time severance payment is unlikely to help, but a monthly pension deposit that has appeared in your account for a year is a different story. If you have any of these income streams, gather at least three to six months of statements before you apply. The stronger your paper trail, the better your chances.
It is also worth noting that some lenders will consider household income rather than just your individual income. If you are married or share finances with a partner who works, their income may be counted, particularly if they are added to the loan or if you live in a community property state. This is not universal, so ask each lender directly.
How Lenders Evaluate Unemployed Refinance Applications
Every lender has its own underwriting playbook, but most follow a similar logic. They start with your credit score and credit history, then layer in income, debt-to-income ratio, loan-to-value ratio, and the age and condition of the vehicle. When income is weak or missing, the other factors have to carry more weight. That means your credit score and the equity in your car become especially important.
Debt-to-income ratio, or DTI, is the percentage of your gross monthly income that goes toward debt payments. If you have no income, DTI is technically infinite, which is why many automated systems decline the application immediately. A human underwriter, however, may look at the full picture and consider compensating factors. A large down payment, a long credit history with no late payments, and a vehicle that is worth more than the loan balance can all help.
Loan-to-value ratio, or LTV, measures how much you owe compared to what the car is worth. If you owe $12,000 on a car worth $18,000, your LTV is about 67 percent, which is favorable. If you owe more than the car is worth, you are upside down, and lenders see higher risk. In an unemployed refinance scenario, being right-side-up on the loan is a major advantage because the lender has collateral to recover if things go wrong.
Credit score thresholds vary widely. Some lenders want a 680 or higher for a refinance, while others work with scores in the 500s. The lower your score, the more likely you are to face higher interest rates or a requirement for a co-signer. If your credit is strong, you have more room to negotiate around the income issue.
Options If You Are Unemployed and Need to Refinance
If a standard refinance application is likely to be declined, you still have options. The goal is to find a lender or structure that addresses the income gap directly. Here are the most realistic paths:
- Add a co-signer. A co-signer with steady income and good credit can make your application much stronger. The lender evaluates both of you, and your combined profile may meet the requirements. Keep in mind that the co-signer is fully responsible if you stop paying, so this is a serious commitment.
- Apply with a credit union. Credit unions are member-owned and often more flexible than large banks. If you already have a relationship with one, or if you are eligible to join through an employer or community group, they may be willing to work with you on alternative income documentation.
- Use a refinance referral service. Platforms that connect borrowers with multiple lenders can save you time and increase your chances of finding one that accepts your situation. Instead of applying to ten lenders individually, you submit one application and get matched with partners who may be open to unemployed or low-income borrowers.
- Wait until you have income. If none of the above works, the most reliable path is to secure a new job, even part-time or gig work, and then apply. Even a few months of consistent deposits can change your eligibility.
- Consider a loan modification instead. Some lenders offer hardship programs that temporarily reduce or defer payments. This is not a refinance, but it can provide breathing room while you search for work.
Each option has trade-offs. A co-signer puts someone else at risk. A credit union may offer better terms but a slower process. A referral service can widen your net but may not guarantee approval. Waiting for a job is the safest but slowest route. The right choice depends on how urgently you need relief and how much risk you are willing to share.
For borrowers who have been turned down by traditional lenders, there are also platforms designed specifically for challenging credit situations. One example is StartAutoLoan, which connects consumers with financing options even after rejections or bankruptcies. It functions as a connection service rather than a direct lender, similar to how CarLoanRefinancing.com operates. If your unemployment has damaged your credit or led to missed payments, a service like this may help you explore lenders who are more forgiving.
Documents You Will Need for an Unemployed Refinance
Preparation is everything when your application is already under scrutiny. Lenders will ask for documentation, and missing paperwork can slow or kill the process. Gathering everything in advance shows that you are organized and serious, which can work in your favor.
Expect to provide the following, though the exact list varies by lender:
- Government-issued photo ID and proof of residence
- Social Security number for a credit check
- Proof of any income you do have (bank statements, benefit letters, 1099s, pension statements)
- Current vehicle registration and insurance
- Existing auto loan statement with the payoff amount
- Vehicle identification number (VIN) and mileage
If you are using a co-signer, that person will need to provide similar documents, including pay stubs and tax returns. If you are self-employed or doing gig work, be ready with profit-and-loss statements or bank deposit histories. The more transparent you are, the easier it is for an underwriter to say yes.
One practical tip: order a copy of your credit report before you apply. Errors are common, and disputing them can raise your score by a few points, which might be enough to offset the income concern. You are entitled to a free report from each of the three major bureaus annually.
Risks and Alternatives to Consider
Refinancing while unemployed is not without risk. If you qualify for a new loan with a longer term, your monthly payment may drop, but you will pay more interest over the life of the loan. If you qualify with a higher interest rate because of your credit or income situation, you might end up paying more overall even if the monthly amount is lower. Run the numbers carefully before you commit.
There is also the risk of default. If you refinance and then cannot make the new payments, you could lose the car and damage your credit further. Be honest with yourself about what you can afford. A temporary hardship program, a payment extension, or even selling the car and buying something cheaper may be better options than a refinance that stretches you too thin.
Another alternative is to focus on finding income first. Even a part-time job or a few weeks of gig work can change your application from borderline to approvable. The trade-off is time, but the result is usually a better loan with better terms. If you can wait, waiting is often the smartest financial move.
Finally, consider the total cost of the refinance, not just the monthly payment. Ask for the APR, the total finance charge, and the payoff timeline. Compare those numbers to your current loan. If the savings are minimal or the terms are worse, it may not be worth the effort. A refinance should improve your situation, not just shuffle it around.
How to Improve Your Chances Before You Apply
If you decide to move forward, there are several steps you can take to strengthen your application. These do not guarantee approval, but they can shift the odds in your favor.
Start by checking your credit score and disputing any errors. Pay down any small balances if you can, because lowering your credit utilization can boost your score quickly. If you have a co-signer in mind, have a frank conversation about expectations and responsibilities before you apply. If you have any income at all, document it thoroughly with bank statements and letters.
You can also research lenders before you apply. Some credit unions and online lenders specialize in borrowers with non-traditional income. If you are working with a referral platform, read the fine print about how they match you with partners. In our guide on refinancing a car loan with Chase, we explain how major banks evaluate applications, which can give you a sense of what to expect from larger institutions.
Timing matters too. If you are expecting a job offer or a severance payment, it may be worth waiting a few weeks. If you are in the middle of a bankruptcy or have recently been discharged, some lenders have waiting periods before they will consider you. Knowing those rules can save you a wasted application.
Above all, be patient. Unemployment is temporary for most people, and the refinance options available to you will improve once you have steady income. If you can make your current payment for now, you may be better off waiting and applying later with a stronger profile.
Refinancing a car loan while unemployed is possible, but it requires strategy, preparation, and realistic expectations. Lenders want to see that you can pay them back, and without a job, you need to show that through other means: a co-signer, alternative income, strong credit, or equity in the vehicle. If none of those apply, the best move may be to wait, find work, and then refinance from a position of strength. Either way, knowing your options puts you in control of the decision rather than letting the decision control you.