
Can You Refinance a Car Loan After a Total Loss Payout?
A total loss payout can leave you owing more than your car was worth. Learn how to refinance car loan after total loss insurance payout and manage the gap.
By Hannah Cooper
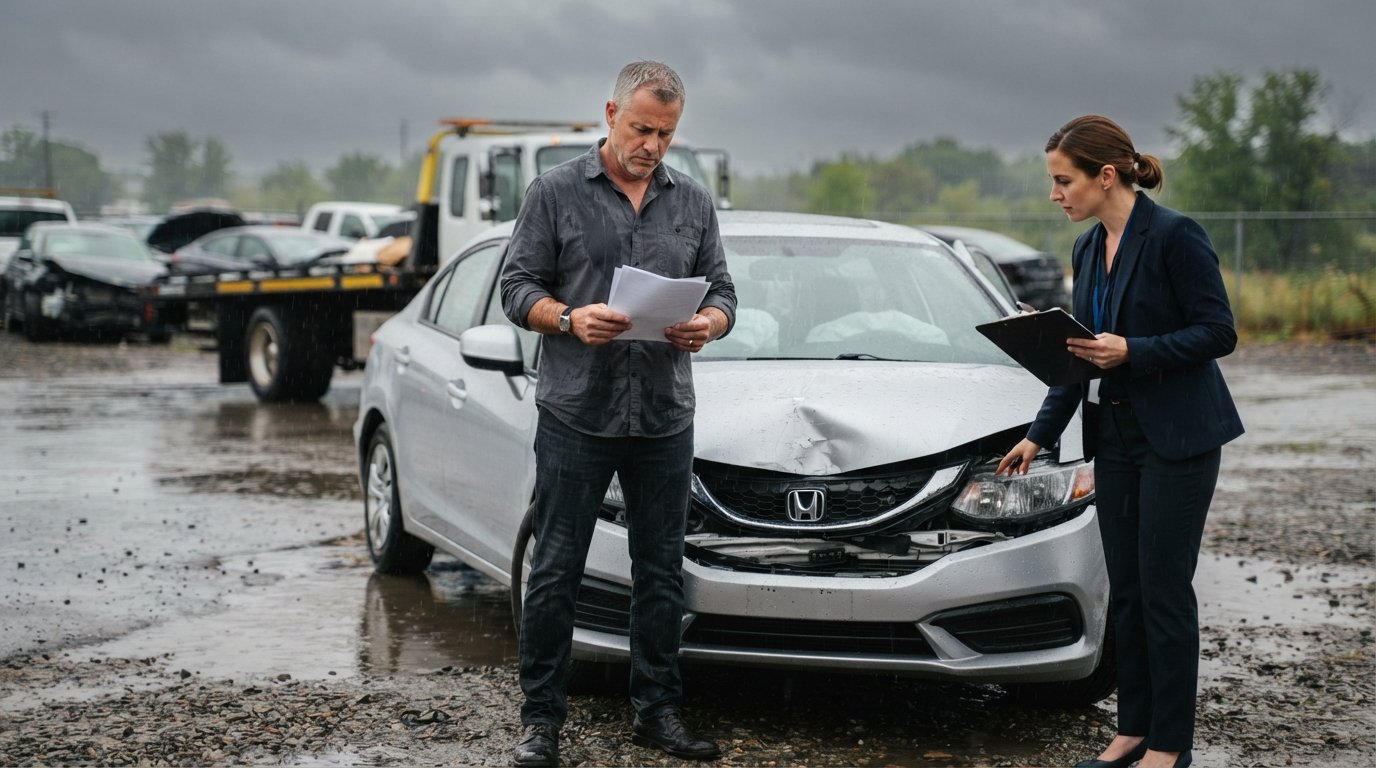
Your car is gone. The insurance company has declared it a total loss, and after weeks of paperwork, they have finally issued a payout. But here is the problem: the check does not cover what you still owe on the loan. You are left with a gap, a damaged credit score, and a nagging question about whether you can refinance car loan after total loss insurance payout to make the remaining balance manageable. This situation is more common than most drivers realize, and the path forward depends on several factors, including your lender, your credit standing, and the type of insurance coverage you carried.
When a vehicle is totaled, the insurance payout typically goes directly to the lienholder, not to you. If the payout exceeds your loan balance, the lender sends you the difference. If it falls short, you are responsible for the remaining deficiency balance unless you purchased gap insurance. Understanding how this process works, and what options exist for refinancing or restructuring the remaining debt, can help you avoid financial pitfalls and protect your credit.
What Happens When Your Car Is Totaled
A total loss occurs when the cost to repair your vehicle exceeds a certain percentage of its actual cash value, usually somewhere between 70 and 80 percent depending on your state and insurer. Once the insurer declares a total loss, they calculate the actual cash value (ACV) of your car at the time of the accident, not what you originally paid for it. This distinction matters because vehicles depreciate quickly, and you may owe significantly more than the ACV.
The insurance payout is sent to your lienholder first because they have a legal claim to the vehicle until the loan is paid off. If the payout satisfies the loan completely, the lender releases the title and you walk away with no further obligation, plus any surplus. However, if the payout is less than your outstanding balance, you face a deficiency balance. This gap can range from a few hundred dollars to several thousand, depending on how much you put down, how long you have been paying, and how rapidly your vehicle depreciated.
Your lender will typically apply the insurance check to your loan balance and then bill you for the remaining amount. Some lenders offer payment plans for deficiency balances, while others expect immediate payment in full. Ignoring this obligation is not an option, as it can lead to collections, wage garnishment, and serious damage to your credit score.
Can You Refinance After a Total Loss?
The short answer is yes, but with important caveats. Refinancing a car loan after a total loss is not the same as refinancing an active loan on a vehicle you still drive. Once the car is totaled, there is no collateral to secure a new loan. Traditional auto refinancing requires a vehicle to serve as collateral, so you cannot simply refinance the deficiency balance into a new auto loan in the usual sense.
However, you may have options to restructure the remaining debt. Some lenders offer unsecured personal loans that can be used to pay off the deficiency balance, effectively converting the auto loan debt into a personal loan with potentially lower interest rates or more manageable terms. This approach is sometimes called refinancing car loan after total loss insurance payout, even though technically it involves a different loan product.
Another possibility is that your lender may agree to modify the terms of your existing loan rather than issuing a new one. This could involve extending the repayment period, reducing the interest rate, or accepting a lump-sum settlement for less than the full balance. These arrangements are not guaranteed, but they are worth discussing with your lender before the account goes into collections.
- Personal loans: Unsecured debt that can cover the deficiency balance
- Loan modification: Your existing lender adjusts terms
- Settlement: Lender accepts less than full balance
- Payment plan: Installment arrangement with the original lender
Each option has different implications for your credit and finances. A personal loan may carry a higher interest rate than a secured auto loan, but it provides a clear payoff timeline. A loan modification keeps the debt with the original lender but may extend how long you are in debt. A settlement can reduce what you owe but may have tax consequences and credit implications.
The Role of Gap Insurance
Gap insurance exists specifically to cover the difference between your loan balance and your vehicle's actual cash value in a total loss. If you purchased gap coverage when you financed your car, the insurer pays the deficiency after your primary insurance settles. This means you would not need to refinance or restructure any remaining debt, as the gap coverage eliminates it.
Many dealerships and lenders offer gap insurance as an add-on at the time of purchase. Some auto insurance policies also include gap coverage as an optional endorsement. If you declined gap insurance and now face a deficiency balance, you may still be able to negotiate with your lender or explore other financing options. For future vehicle purchases, gap insurance is a worthwhile investment, especially if you make a small down payment or finance for a long term.
It is important to note that gap insurance only covers the difference between the ACV and your loan balance. It does not cover deductibles, overdue payments, or any additional fees. Review your policy carefully to understand exactly what is covered and what you remain responsible for.
How Refinancing or Restructuring Affects Your Credit
A total loss and subsequent deficiency balance can have a significant impact on your credit score. The insurance payout itself does not affect your credit, but how you handle the remaining debt does. If you pay the deficiency balance on time and in full, the damage is minimal. If you miss payments or default, the negative marks can linger for years.
Refinancing the deficiency balance through a personal loan can actually help your credit if you make consistent, on-time payments. It shows lenders that you are taking responsibility for the debt and managing it effectively. However, applying for new credit may cause a small, temporary dip in your score due to hard inquiries. Over time, responsible repayment can outweigh that initial impact.
If you choose a loan modification or settlement, the effect on your credit depends on how the lender reports it. Some lenders report modifications as a continuation of the original account, while settlements may be reported as paid for less than the full amount, which can be viewed negatively by future lenders. Always ask your lender how they will report the arrangement to the credit bureaus.
For those considering refinancing an active auto loan, whether after a total loss or simply to save money, working with a platform that connects you to multiple lenders can simplify the process. You can explore options for refinancing a car loan with Chase and other lenders to compare rates and terms that fit your situation.
Steps to Take After a Total Loss Payout
If you find yourself facing a deficiency balance after a total loss, taking the right steps in the right order can make a significant difference in your financial outcome. The process requires patience, communication, and a clear understanding of your rights and obligations.
First, confirm the exact amount of the deficiency. Request a written statement from your lender showing the insurance payout, the remaining balance, and any fees or interest that have accrued. Review your original loan documents to understand the terms and any provisions related to total loss or deficiency balances.
Next, review your insurance policy and any add-ons you purchased. If you have gap insurance, file a claim immediately. If you do not, determine whether you have any other coverage that might apply, such as credit insurance or a waiver addendum. Some lenders offer total loss protection as part of the loan agreement, so check your paperwork carefully.
Then, contact your lender to discuss your options. Be honest about your financial situation and ask what arrangements they are willing to make. Some lenders have hardship programs or are willing to negotiate a settlement. Others may offer a payment plan with reduced interest. The key is to communicate before the account is sent to collections.
- Confirm the deficiency balance in writing
- Review insurance policies and loan documents for coverage
- Contact your lender to discuss options
- Explore personal loans or refinancing alternatives
- Negotiate a settlement or payment plan if possible
Finally, if you cannot pay the deficiency in full and your lender is unwilling to negotiate, consider working with a credit counselor or financial advisor. They can help you evaluate your options, including debt consolidation, and develop a plan to manage the remaining balance without further damaging your credit.
When Refinancing Makes Sense
Refinancing or restructuring the deficiency balance makes sense when you can secure better terms than what your current lender offers. For example, if your lender is charging a high interest rate on the remaining balance or demanding immediate payment, a personal loan with a lower rate and flexible repayment terms could be a better solution. Similarly, if you have improved your credit score since the original loan, you may qualify for more favorable terms.
However, refinancing is not always the best option. If the deficiency balance is small and you can pay it off quickly, doing so may be simpler and less costly than taking on new debt. If your credit is already damaged, you may not qualify for competitive rates, and a new loan could make your financial situation worse. Evaluate your options carefully and consider the total cost of each approach before committing.
It is also worth considering whether you need a new vehicle. If you plan to purchase another car soon, addressing the deficiency balance first is critical. Lenders are often reluctant to approve new auto loans for borrowers with unresolved deficiency balances, as it signals financial risk. Paying off or settling the debt can improve your chances of qualifying for a new loan with reasonable terms.
For those exploring their refinancing options, platforms that connect borrowers with multiple lenders can provide valuable comparison shopping. Whether you are looking to refinance an existing loan or explore financing for a new vehicle, understanding the full range of options available can help you make a more informed decision. If you are considering a new auto loan, resources like StartAutoLoan can connect you with lenders who work with a variety of credit profiles.
Alternative Options to Consider
If refinancing is not feasible, there are other ways to manage a deficiency balance after a total loss. One option is to negotiate a settlement with your lender. Lenders may be willing to accept less than the full balance if you can pay a lump sum, especially if the alternative is sending the account to collections. A settlement typically requires you to pay a percentage of the balance, often between 50 and 80 percent, depending on the lender and your circumstances.
Another option is a payment plan with the original lender. Many lenders offer extended repayment terms for deficiency balances, allowing you to pay over several months or even years. While this may involve interest and fees, it can be more manageable than a lump-sum demand. Be sure to get any payment plan in writing, including the total amount you will pay and the schedule.
Debt consolidation is another strategy. If you have multiple debts, including the deficiency balance, consolidating them into a single loan can simplify your payments and potentially reduce your overall interest rate. However, this approach requires discipline, as you must avoid accumulating new debt while paying off the consolidated loan.
In some cases, bankruptcy may be the only viable option. A deficiency balance from a total loss is typically dischargeable in bankruptcy, meaning you would not be responsible for paying it. However, bankruptcy has severe and long-lasting effects on your credit, so it should be considered only as a last resort after exploring all other options.
Protecting Yourself in the Future
Preventing a deficiency balance in the first place is far easier than dealing with one after a total loss. When you finance a vehicle, consider making a substantial down payment to reduce the amount you borrow. A larger down payment means you are less likely to owe more than the car is worth, even if it depreciates quickly.
Choose a shorter loan term when possible. Longer terms mean lower monthly payments but more time for depreciation to outpace your payments. A shorter term reduces the risk of being upside down on your loan. If you must choose a longer term, consider gap insurance to protect yourself in case of a total loss.
Regularly monitor your loan balance and your vehicle's value. If you notice that you owe significantly more than the car is worth, consider making extra payments to close the gap. You can also explore refinancing to a shorter term or lower rate, which can help you pay off the loan faster and reduce the risk of a deficiency.
Finally, review your insurance coverage annually. Make sure you have adequate coverage, including collision and comprehensive, which are required by most lenders. If you have concerns about a potential deficiency, consider adding gap insurance if you do not already have it. These steps can provide peace of mind and financial protection in the event of a total loss.
Dealing with a total loss and a deficiency balance is stressful, but it is not insurmountable. By understanding your options, communicating with your lender, and taking proactive steps, you can manage the remaining debt and move forward. Whether you choose to refinance, negotiate a settlement, or explore other alternatives, the key is to act quickly and thoughtfully. Your credit and financial future depend on how you handle this challenge, so approach it with the same care you would any other important financial decision.