
What Happens If You Stop Paying a Refinanced Car Loan?
Stopping payments on a refinanced car loan triggers late fees, credit damage, and repossession risk. Learn the timeline and how to protect your car and credit.
By Kevin Brooks
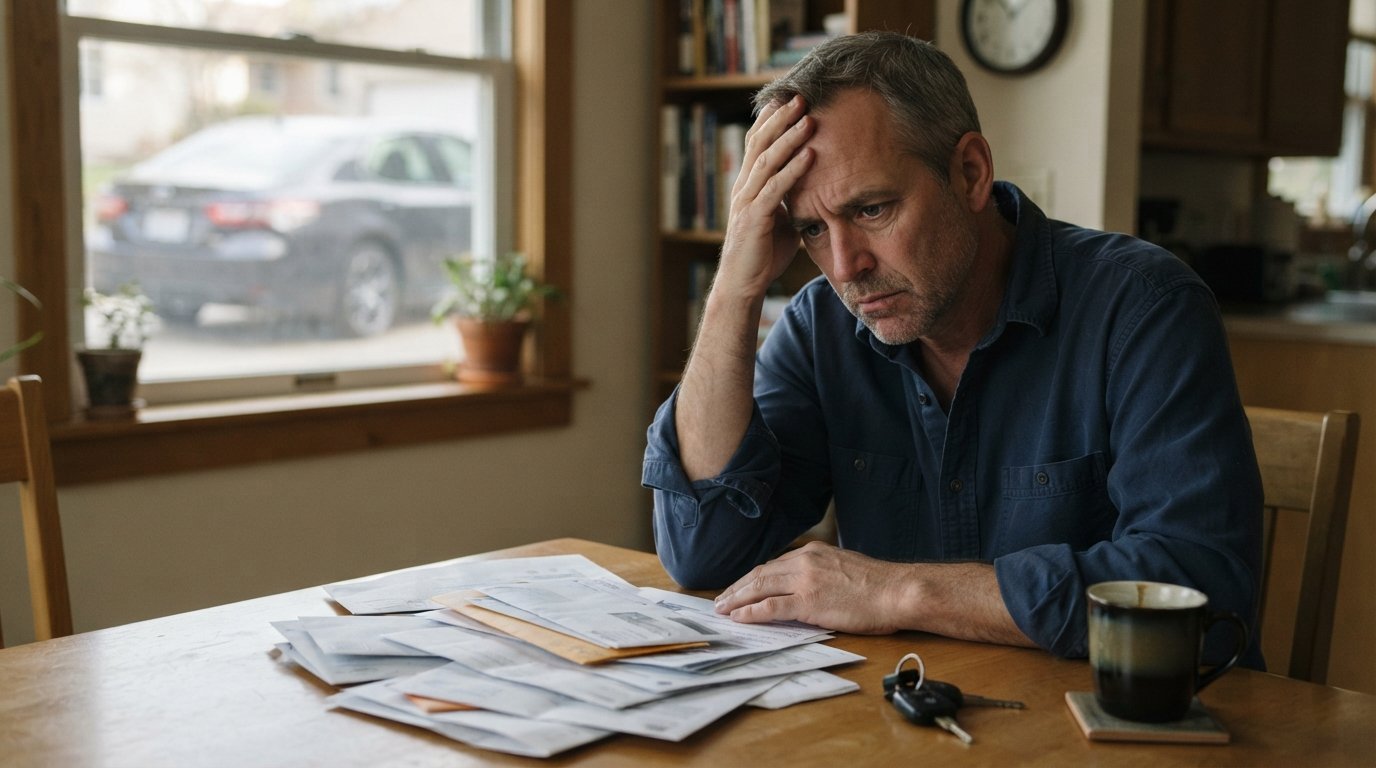
Missing a payment on your refinanced car loan can feel like a small hiccup, but the consequences escalate quickly. Within days, late fees appear. Within weeks, your credit score takes a hit. Within months, the lender can repossess your vehicle. Understanding the full sequence of events is the first step toward protecting your car, your credit, and your financial future.
When you refinance a car loan, you sign a new contract with a new lender. That lender expects payments on a specific schedule. If you stop paying, the lender follows a predictable path: reminders, late fees, delinquency reporting, default, and ultimately repossession. The exact timeline varies by lender and state law, but the direction is always the same. The good news is that you have more options than you might think, especially if you act early. This guide walks you through each stage, explains how to reach out for help, and shows how to minimize damage if the worst happens.
The Domino Effect: From First Missed Payment to Repossession
Most refinanced car loans come with a grace period, typically 10 to 15 days after the due date. During this window, you can pay without a late fee, though some lenders charge a small fee immediately. Once the grace period ends, the clock starts ticking on a series of consequences that can affect your wallet and your credit report.
Here is the typical sequence of events if you stop paying a refinanced car loan:
- Days 1 to 15: Grace period. A late fee may apply after day 10 or 15. Your credit is usually not affected yet.
- Days 30 to 60: Delinquency. The lender reports the late payment to the credit bureaus, which can drop your score by 50 to 100 points or more. You will receive phone calls and letters.
- Days 60 to 90: Serious delinquency. The lender may offer hardship options or demand full payment. Your credit score suffers further, and the lender may begin repossession proceedings.
- Days 90 to 120+: Default and repossession. The lender can repossess the vehicle without prior notice in many states, depending on the loan contract and local laws.
After repossession, the lender sells the car at auction, often for less than the outstanding loan balance. You are responsible for the difference, known as a deficiency balance, plus repossession fees, storage costs, and attorney fees. This can turn a $10,000 loan into a $15,000 debt even after the car is gone.
Each stage gives you a chance to act. The earlier you contact your lender, the more options you have. Waiting until the tow truck arrives limits your choices dramatically.
Why Calling Your Servicer Early Opens More Doors
Lenders do not want to repossess your car. Repossession is expensive and time-consuming for them. They would rather work out a payment plan. But they cannot help you if you ignore their calls and letters. By reaching out before you miss a payment (or immediately after), you demonstrate good faith and open the door to solutions that are not available to borrowers who go silent.
When you call your servicer, be honest about your situation. Explain why you cannot pay (job loss, medical emergency, reduced hours) and ask what options exist. Many lenders have dedicated hardship departments trained to help. They may offer a deferment, a temporary reduction in payments, or a loan modification. These programs are designed to keep you in the car and the loan out of default.
Silence, on the other hand, sends a clear message: you are either unable or unwilling to pay. Lenders escalate faster when they cannot reach you. They may skip the hardship conversation and move straight to repossession. A single phone call can be the difference between keeping your car and losing it.
If you are unsure how to start the conversation, consider using a free tool to compare refinancing options or consult a nonprofit credit counselor. The key is to act before the situation spirals.
Hardship Programs, Deferments, and Payment Modifications
Most lenders offer some form of relief for borrowers facing temporary financial hardship. The specific programs vary, but they generally fall into three categories: deferments, forbearances, and modifications.
A deferment allows you to pause payments for one or more months. Interest may continue to accrue, but you avoid late fees and credit damage. A forbearance is similar but may involve a temporary reduction rather than a full pause. A modification changes the terms of your loan permanently, such as extending the repayment period or lowering the interest rate. Modifications are harder to qualify for but offer long-term relief.
To qualify, you typically need to provide documentation of your hardship, such as a layoff notice, medical bills, or bank statements. The lender will review your income and expenses to determine what you can afford. Be prepared to explain how your situation has changed and when you expect it to improve. If you can show a clear path back to on-time payments, your chances of approval increase.
It is important to note that hardship programs are not automatic. You must ask for them. And they are not guaranteed. But they are almost always better than doing nothing. Even if you are denied, the conversation may reveal other options, such as a temporary payment plan or a due date change.
If you have already missed payments and your credit has suffered, you may wonder if refinancing is still possible. In many cases, it is. Lenders that specialize in bad credit auto loans may work with you to restructure your loan and avoid repossession. The key is to explore every avenue before giving up.
How Repossession Affects Your Credit and Future Refinancing
A repossession is one of the most damaging entries you can have on your credit report. It stays there for seven years and can lower your score by 100 points or more. Even after you pay off the deficiency balance, the repossession remains, making it harder to qualify for new credit, including auto loans, mortgages, and even some jobs.
The impact on future refinancing is significant. Most lenders view a repossession as a major red flag. They may deny your application outright or offer terms with very high interest rates. If you need a car loan after repossession, you may be limited to subprime lenders that charge double-digit APRs. Rebuilding your credit takes time and consistent effort, such as making on-time payments on other debts and keeping credit card balances low.
Beyond credit, a repossession can affect your ability to get to work, care for your family, and manage daily life. The stress of losing a vehicle often compounds the financial strain. That is why it is crucial to explore alternatives before the lender takes the car.
If you are already facing repossession, you may be able to negotiate a voluntary surrender or a repayment plan that stops the process. Some lenders will work with you if you can demonstrate a willingness to pay. But once the car is gone, your options shrink considerably.
Protecting Your Equity If You Must Sell the Vehicle
If you can no longer afford the payments and hardship programs are not enough, selling the car yourself is often better than letting it be repossessed. A private sale typically fetches a higher price than an auction, which means you may avoid a deficiency balance or even walk away with cash.
To sell a car with a lien, you need to pay off the loan first. If the sale price is less than the loan balance, you will need to cover the difference out of pocket. Some lenders allow a short sale, where they agree to accept less than the full balance. This is not guaranteed, but it is worth asking about.
Here are steps to protect your equity if you decide to sell:
- Get a payoff quote from your lender. This tells you exactly how much is owed, including any fees.
- Determine the car's market value using online tools or a professional appraisal. Compare it to the payoff amount to see if you have positive or negative equity.
- Contact your lender to explain your plan. Ask about short sale options if the value is less than the payoff.
- List the car for sale with a clear description and photos. Be transparent about the lien and the payoff process.
- Complete the sale with a bill of sale and arrange for the lender to release the title once the loan is paid.
Selling takes more effort than surrendering the car, but it can save you thousands in deficiency balances and fees. It also gives you more control over the process and may reduce the damage to your credit.
Before you sell, consider whether refinancing again could lower your payment. If your credit has improved since you took out the original refinanced loan, you might qualify for a better rate. Our guide on how to refinance a car loan with Chase explains the process step by step. Even if you are not a Chase customer, the principles apply to any lender.
Rebuilding After a Setback
If you have already missed payments or lost a car to repossession, know that recovery is possible. Start by addressing the immediate financial issues: create a budget, cut unnecessary expenses, and look for ways to increase income. Then focus on rebuilding your credit. Make all payments on time, keep credit card balances low, and avoid new debt. Over time, your score will recover.
When you are ready to finance a car again, be honest about your credit history. Look for lenders that specialize in helping people with past credit issues. Many credit unions and online lenders offer second-chance auto loans with reasonable rates. You can also use our free resources to compare refinancing options and find a lender that fits your situation.
Remember that a refinanced car loan is a contract, but it is not a life sentence. Lenders have procedures to follow, and you have rights. If you are struggling, reach out early, ask for help, and explore every option before the situation escalates. Your car and your credit are worth protecting. FreeAutoInsuranceQuotesOnline