
Refinance Then Sell: What Happens to Your Car Loan
Selling a car after refinancing is common, but the new lender's lien changes the payoff process. Know the steps to avoid title delays and surprise fees.
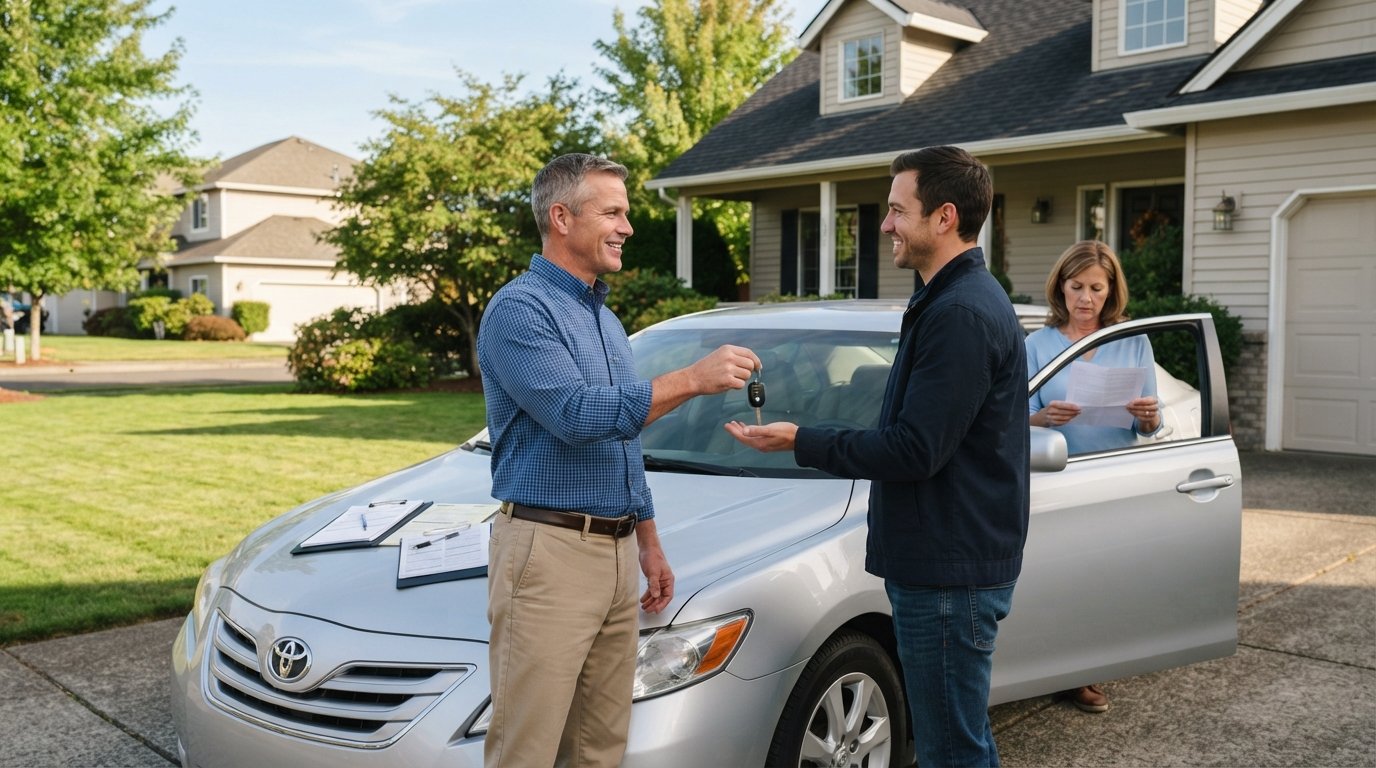
You refinanced your car loan to snag a lower rate or a smaller monthly payment, and now life throws you a curveball: you need to sell the car. Maybe a job relocation, a growing family, or a sudden budget crunch has you wondering whether that refinance decision complicates the sale. The short answer is no, refinancing does not lock you into the vehicle, but it does change who holds the lien and how the payoff process works. Understanding those mechanics before you list the car can save you from surprise fees, title delays, or a deal that falls apart at the last minute.
When you refinance, your original lender is paid off and a new lender takes over the loan, which means the new lender also takes over the lien on your title. Selling a car with a lien is a routine transaction, but the steps differ from selling a vehicle you own free and clear. The proceeds from the sale typically go to the lender first, and anything left over comes to you. If the car sells for less than what you owe, you are still responsible for the gap. Below, we walk through the lien, the payoff process, potential penalties, and what to do when the numbers do not line up.
How the New Lender's Lien Changes the Sale
Refinancing is essentially a new loan that pays off the old one. The new lender files a lien on your vehicle title, and that lien stays in place until the loan is fully repaid. This is not a problem for selling, but it does mean the buyer cannot receive a clean title until the lien is released. In practice, you will be selling a car with an outstanding loan, which is far more common than most people realize. According to industry data, a large share of trade-ins and private-party sales involve vehicles with active liens.
The key difference after refinancing is that the lienholder has changed. Your original lender no longer has any claim on the car, so any payoff quote or lien release must come from the new lender. If you try to sell the car and the buyer's bank or the DMV checks the title, they will see the new lender listed as the lienholder. That is why it is critical to have the new lender's contact information and account number handy before you start negotiating a sale.
Another wrinkle: some states issue electronic titles when a lien is active, meaning you may not have a physical title in hand. In that case, the payoff and lien release process is handled electronically between the lender and the state motor vehicle department. You will need to confirm with your new lender how they handle title release, because the process can vary by state and by lender. This is especially relevant if you refinanced with an online lender or a credit union that operates across multiple states.
If you are considering a refinance and want to understand how a specific lender manages liens and titles, our guide on how to refinance a car loan with Chase walks through the paperwork and title handling for a major bank, which can give you a sense of what to expect from other lenders as well.
The Payoff Process When Selling a Refinanced Vehicle
Selling a car with a lien follows a specific sequence, and refinancing does not change that sequence, but it does change the parties involved. The first step is to obtain a payoff quote from your new lender. A payoff quote is different from your current balance: it includes the remaining principal plus any accrued interest and fees as of a specific date. Most lenders provide quotes that are valid for 10 to 15 days, which gives you a window to close the sale.
Once you have a buyer and agree on a price, the actual money flow depends on whether you are selling to a dealer or a private party. Here is how the process typically unfolds:
- Get a payoff quote from your new lender. Request it in writing and note the expiration date. This tells you exactly how much is needed to clear the lien.
- Collect the sale proceeds. If you sell to a dealer, they may handle the payoff directly with your lender as part of the transaction. If you sell privately, you will collect payment from the buyer.
- Pay off the loan. Send the payoff amount to your lender using a traceable method (wire transfer, cashier's check, or ACH). Keep proof of payment.
- Obtain a lien release. Once the loan is paid in full, the lender must release the lien. This may take a few business days to a few weeks, depending on the lender and state.
- Transfer the title. With the lien released, you can sign the title over to the buyer and complete the DMV paperwork.
Each of these steps has timing implications. If the buyer needs financing, their lender may require a clean title before releasing funds, which can create a chicken-and-egg situation. In those cases, an escrow service or a title company can hold the funds while the payoff and lien release are processed. Dealers are accustomed to this and often manage it in-house, but private-party sales require more coordination.
It is also worth noting that some lenders charge a payoff statement fee or a lien release fee. These are usually small (under $50), but they should be factored into your sale proceeds. Ask your lender for a full breakdown of any fees associated with paying off the loan early.
Are There Penalties for Selling Soon After Refinancing?
One of the most common concerns is whether refinancing and then selling quickly triggers a prepayment penalty. The good news is that most auto loans do not have prepayment penalties. In fact, many states prohibit them for consumer auto loans. However, there are exceptions, and the terms of your refinance agreement govern what applies to you.
When you refinanced, you signed a new loan contract. That contract may include a prepayment penalty clause, especially if you refinanced with a lender that specializes in subprime or bad-credit loans. A prepayment penalty is a fee charged if you pay off the loan before a certain date, often within the first 12 to 24 months. The fee is typically a percentage of the remaining balance or a flat amount, and it can eat into any savings you gained from refinancing.
Beyond prepayment penalties, there are other costs to consider. Refinancing often involves origination fees, title transfer fees, and sometimes a lien filing fee. If you sell soon after refinancing, you may not have enough time to recoup those upfront costs through lower monthly payments. For example, if you paid $300 in refinance fees and saved $25 per month, it would take 12 months to break even. Selling after three months means you effectively lost money on the refinance, even if the rate was lower.
To avoid surprises, review your refinance agreement for any language about early payoff. Look for terms like "prepayment penalty," "early payoff fee," or "minimum finance charge." If you cannot find the information, call your lender and ask directly. It is also wise to request a payoff quote that explicitly states whether any penalties apply.
Another consideration: some lenders offer a "skip a payment" or deferment option shortly after refinancing. If you took advantage of that, the interest may have continued to accrue, and your payoff amount could be higher than expected. Always confirm the exact payoff figure before agreeing to a sale price.
When the Car Is Worth Less Than the Payoff
Being upside down on a car loan (owing more than the car is worth) is common, especially if you refinanced recently or put little money down. Selling a car in this situation is not impossible, but it requires bringing cash to the table or finding a buyer willing to work with the lender.
The first step is to determine the actual cash value of your car. You can use online tools like Kelley Blue Book or Edmunds, or get a written offer from a dealer or CarMax. Compare that to your payoff quote. The difference is the amount you will need to cover out of pocket.
If you have the cash, the process is straightforward: you pay the difference to the lender, they release the lien, and you can sell the car for its market value. The buyer pays you the sale price, and you use that money plus your own funds to clear the loan. This is often the cleanest path, but not everyone has the cash on hand.
If you do not have the cash, consider these options:
- Roll the negative equity into a new loan. Some dealers will allow you to trade in the car and add the negative equity to the financing of a new vehicle. This increases your new loan balance, but it gets you out of the current car.
- Negotiate with the lender. In some cases, lenders may agree to a short sale or a reduced payoff if you can demonstrate financial hardship. This is more common with credit unions than with large banks, but it is worth asking.
- Borrow the difference. A personal loan or a loan from a family member can cover the gap. Just be sure you can afford the payments on both the personal loan and any new car loan.
- Wait and pay down the loan. If you can delay the sale, making extra payments can reduce the gap. This is often the least risky option if you are not under time pressure.
Each of these options has trade-offs. Rolling negative equity into a new loan is convenient but can leave you further upside down on the next vehicle. Borrowing the difference adds debt but preserves your ability to sell now. Waiting requires patience but avoids extra costs. The right choice depends on your urgency and your overall financial picture.
It is also important to communicate with your lender if you are struggling. Many lenders have hardship programs that can temporarily reduce or defer payments, which may give you time to sell the car or save the cash to cover the gap. Ignoring the problem can lead to repossession, which damages your credit and makes it harder to sell the car on your terms.
Practical Steps to Sell a Refinanced Car Smoothly
To minimize friction, treat the sale as a project with clear milestones. Start by gathering the key documents: your refinance agreement, the most recent statement from your new lender, and the vehicle title (or a statement that the title is held electronically). Then follow a sequence that keeps the buyer, the lender, and the DMV in sync.
First, request a payoff quote and confirm the per-diem interest (the amount that accrues each day). This helps you time the payoff so you do not overpay. Second, decide on the sale channel: dealer, private party, or online buyer. Each has different paperwork requirements. Dealers often handle the payoff and lien release for you, while private sales require you to manage the process. Third, set a realistic price based on the car's condition and the payoff amount. If you are upside down, be upfront with potential buyers about the lien situation.
Fourth, use a bill of sale that includes the sale price, the vehicle identification number, and a statement that the lien will be satisfied. Fifth, pay off the loan and obtain the lien release before transferring the title. Do not hand over the keys until the lien release is in hand or the buyer's lender has confirmed the payoff. Finally, complete the DMV transfer and keep copies of all documents for your records.
One more tip: if you are selling privately, consider meeting the buyer at your lender's branch. This allows the lender to confirm the payoff and release the lien on the spot, which builds trust and reduces the risk of fraud. Not all lenders offer this, but it is worth asking.
For additional guidance on protecting yourself during the sale, including how insurance coverage works during a transition, resources like NewAutoInsurance provide educational articles on coverage options and savings that can help you make informed decisions about your vehicle insurance before and after the sale.
How Refinancing Affects Your Credit and Future Loans
Refinancing itself does not hurt your credit in the long run, but it does create a hard inquiry and a new account, which can cause a small, temporary dip. If you sell the car and pay off the refinanced loan, that payoff is reported to the credit bureaus as a satisfied account. Paying on time and closing the loan in good standing can actually help your credit history, as it demonstrates responsible borrowing.
However, if you sell the car and the payoff is late or the loan goes into default before the sale closes, that negative information can stay on your credit report for up to seven years. This is why it is critical to keep making payments until the loan is fully paid off, even if you have a buyer lined up. Do not cancel automatic payments until you have confirmation that the payoff has been processed and the lien released.
Looking ahead, if you plan to finance another vehicle, lenders will look at your debt-to-income ratio and payment history. A successfully paid-off auto loan can be a positive factor, but if you rolled negative equity into a new loan, your new balance will be higher and your monthly payment may increase. It is worth running the numbers before you commit to a new loan to ensure you are not repeating the same cycle.
Refinancing and then selling is a normal part of car ownership for many people. The key is to understand the lien, get a payoff quote early, and plan for any gap between the sale price and the loan balance. With the right preparation, you can sell your car, satisfy the loan, and move on to your next vehicle without unnecessary stress or cost.