
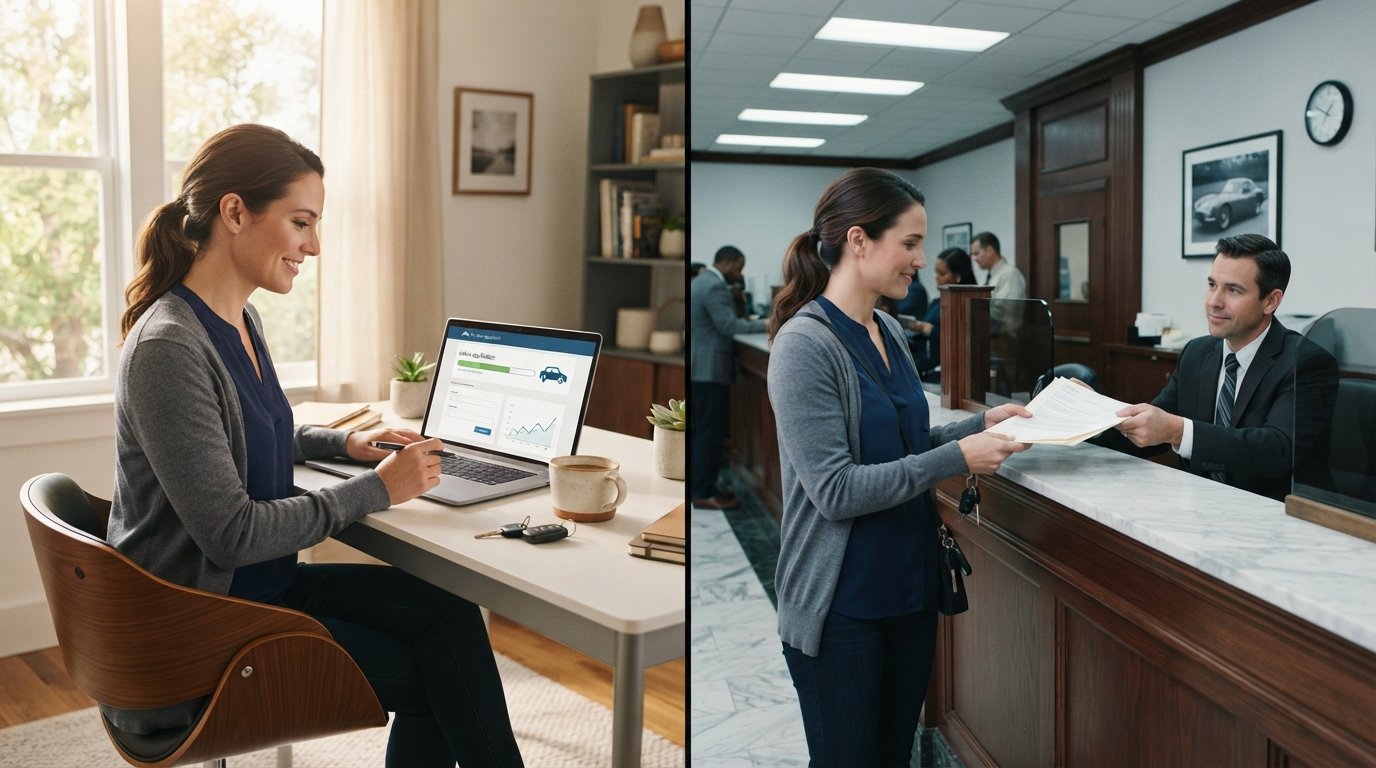
Online Auto Loan Lenders vs Traditional Banks: 2026 Guide
Compare online auto loan lenders vs traditional banks on rates, approval odds, and speed. See which option fits your credit and saves you money.
By Tyler Bennett
Picture this: you need a car loan, and you have two paths in front of you. One is a sleek online process that promises an answer in minutes. The other is the familiar branch on the corner where you have cashed checks for years. The decision between online auto loan lenders vs traditional banks can shape your interest rate, your monthly payment, and how much time you spend chasing paperwork.
This comparison is not about declaring one side the universal winner. It is about matching your credit profile, your schedule, and your financial goals to the lender type that serves you best. Whether you are buying your first car, refinancing an expensive loan, or rebuilding credit after a setback, understanding how each option works will help you negotiate from a position of knowledge rather than hope.
Below, we break down the application experience, rate structures, approval odds, and hidden tradeoffs on both sides. We also show where an online referral platform can widen your options without adding pressure.
How Online Auto Loan Lenders Operate
Online auto loan lenders are financial companies that conduct most or all of the lending process through a website or mobile app. Some are direct lenders with their own capital, while others are marketplaces that connect your application to a network of lending partners. The defining feature is speed and convenience: you submit information digitally, receive a decision or pre-qualified offer quickly, and often e-sign documents without visiting an office.
These lenders tend to specialize. You will find platforms focused on prime credit, others built for bad credit or no credit history, and some that cater to refinancing only. Because they operate with lower overhead than a branch network, many can pass savings along in the form of lower rates or reduced fees. That said, not every online offer is a bargain, and the fastest approval is not always the cheapest.
One important distinction is between direct online lenders and connection services. A direct lender funds your loan itself. A connection service, like the platform at StartAutoLoan, collects your information and routes it to participating lenders who may compete for your business. This model can be helpful if you have been turned down before, because one application reaches multiple financing sources instead of just one.
Here are the typical traits of online auto loan lenders:
- Digital application with instant or same-day pre-qualification decisions
- Specialized programs for bad credit, no credit, or post-bankruptcy borrowers
- Rate quotes and loan terms displayed before you commit
- Limited or no physical branches, which can mean lower operating costs
- Variable customer service quality, ranging from excellent to hard to reach
That last point matters. When everything happens online, you cannot sit across a desk from a loan officer. For some borrowers that is a relief. For others, the lack of a human touch creates uncertainty, especially when documents are complex or something goes wrong during funding.
How Traditional Banks Approach Auto Loans
Traditional banks have been in the auto lending business for decades. They typically offer new and used car loans, refinancing, and sometimes lease buyouts. If you already have a checking account, savings account, or mortgage with the bank, you may qualify for relationship discounts or faster verification because the institution already knows your deposit history.
The bank experience is built around branches and loan officers. You can walk in, ask questions face to face, and get help assembling your paperwork. For borrowers who value hand-holding or who have complicated financial situations, that personal guidance can be worth a slightly higher rate. Banks also tend to have established fraud protections and clear regulatory oversight, which can add a layer of confidence.
On the other hand, banks are often stricter about credit. A history of late payments, a recent bankruptcy, or a thin credit file can lead to a quick rejection. Their rates for excellent credit can be very competitive, sometimes matching or beating online offers, but their rates for subprime borrowers are frequently higher, if they lend at all.
Consider these common bank characteristics:
- Branch access for in-person questions and document review
- Relationship pricing for existing customers
- Stricter credit score and income requirements
- Slower application and funding timelines, sometimes several business days
- Limited options if you have bad credit or no credit history
If your credit is strong and you prefer a familiar institution, a bank can be an excellent choice. If your credit is damaged or nonexistent, the bank may not be the door that opens.
Rates, Fees, and the Real Cost of Convenience
Interest rates are where the online auto loan lenders vs traditional banks comparison gets interesting. Online lenders often advertise lower starting rates because they compete nationally and carry less overhead. Banks may match those rates for their best customers but rarely lead the market for subprime borrowers. The gap can be several percentage points, which translates into hundreds or thousands of dollars over the life of a loan.
Fees also differ. Some online lenders charge origination fees, while others do not. Banks may waive fees for existing customers or impose them for out-of-state applicants. Always ask for the annual percentage rate, not just the interest rate, because the APR includes fees and gives you a truer cost of borrowing. A loan with a low rate and a high origination fee can cost more than a slightly higher rate with no fees.
One practical strategy is to get pre-qualified with at least three sources: one bank, one credit union, and one online lender or connection service. Pre-qualification usually involves a soft credit pull that does not affect your score, so you can compare offers without penalty. When you are ready to proceed, the lender will perform a hard pull, which may temporarily lower your score by a few points. Rate shopping within a short window, typically 14 to 45 days depending on the scoring model, usually counts as a single inquiry.
To keep the comparison fair, request the same loan amount, term, and vehicle information from each lender. Then compare:
- The APR, not just the advertised interest rate
- Total fees, including origination, documentation, and prepayment penalties
- Monthly payment and total interest paid over the life of the loan
- Whether the rate is fixed or variable
- Customer service availability and how disputes are handled
That last item is easy to overlook until you need help. A lender with a slightly higher rate but responsive support may be the better long-term partner.
Approval Odds and Credit Requirements
Banks generally reserve their best rates for borrowers with credit scores in the mid-700s or higher. Below that, you may still be approved, but the rate climbs quickly. Below 600, many banks will decline outright. Credit unions are often more flexible than banks, but they still have minimum standards.
Online lenders fill the gap. Some specialize in bad credit auto loans, no credit first-time buyer programs, and financing after bankruptcy. These lenders may approve borrowers with scores in the 500s, though they often require a larger down payment or charge higher rates to offset risk. The tradeoff is access: an online lender may say yes when a bank says no, but the cost of that yes can be steep.
If you are recovering from bankruptcy, timing matters. Many lenders require a waiting period after discharge, often one to two years, before they will consider an auto loan. Online lenders that focus on this niche may have shorter waiting periods than traditional banks, but they will scrutinize your post-bankruptcy payment history closely.
The table below summarizes the general approval landscape, though individual lenders vary:
- Excellent credit (720+): Both banks and online lenders offer competitive rates. Compare carefully.
- Good credit (660 to 719): Banks may offer decent rates; online lenders are often more flexible.
- Fair credit (600 to 659): Online lenders become more attractive; bank approvals are possible but pricier.
- Poor credit (below 600): Online lenders and specialty finance companies dominate.
- No credit or post-bankruptcy: Mostly online lenders and niche programs, sometimes with higher down payments.
Knowing where you fall helps you target the right lenders and avoid wasting hard inquiries on applications that are unlikely to succeed.
The Application Process: Speed vs Support
Online applications typically take 10 to 15 minutes. You enter your personal information, vehicle details, income, and consent to a credit check. Pre-qualification results may appear instantly. If you accept an offer, you upload documents, e-sign, and wait for funding, which can happen in as little as one business day.
Bank applications may also start online, but the process often includes a branch visit or a phone call with a loan officer. Document review can take longer, and funding may take several business days. The upside is that you have a named contact who can explain terms and troubleshoot problems.
If your situation is straightforward (steady income, decent credit, standard vehicle), the online path is hard to beat for speed. If your situation is complex (self-employment income, recent job change, co-signer issues), the bank's human support can prevent costly mistakes.
For refinancing specifically, the process is similar on both sides, but online platforms often make it easier to compare multiple refinance offers at once. You can read more about the mechanics in our guide on how online auto refinance works, which walks through each step from pre-qualification to funding.
Customer Service and Problem Resolution
Customer service is where the online vs traditional bank debate becomes personal. Banks offer branch hours, phone support, and sometimes dedicated loan officers. If a payment posts incorrectly or you need a payoff letter urgently, you can walk in and speak to a person.
Online lenders vary widely. Some have 24/7 chat and phone support with short wait times. Others are difficult to reach and slow to resolve issues. Before you sign, test the lender's support: call the number, start a chat, and see how long it takes to get a real answer. A lender that is unresponsive before funding is unlikely to improve after.
Connection services add another layer. When a platform routes your application to a partner lender, your ongoing relationship is with that lender, not the platform. That is fine as long as you understand it. Keep records of every offer, disclosure, and communication. If a dispute arises, you will need documentation.
When an Online Referral Platform Makes Sense
Sometimes the best move is not choosing between a single online lender and a single bank, but expanding your options through a referral platform. These services collect your information once and share it with a network of lending partners who may compete for your business. For borrowers with bad credit, no credit history, or a past bankruptcy, this can be the difference between a rejection and a workable offer.
The site you are reading, CarLoanRefinancing.com, operates as an educational and referral platform rather than a direct lender. It provides guides, calculators, and rate comparisons, then connects users with a nationwide network of lending partners. The application is free, there is no obligation to accept an offer, and you can see what you qualify for before committing. That structure is designed for borrowers across the credit spectrum, including those who have been turned away by traditional banks.
If you are weighing online auto loan lenders vs traditional banks and you are not sure where you fit, a referral platform can serve as a low-risk starting point. You get a sense of your options without applying to each lender individually. Just remember that the platform is not the lender; the terms that matter come from the partner who funds your loan.
Making the Right Choice for Your Situation
There is no single answer that fits every borrower. The right choice depends on your credit, your timeline, and how much support you want. Use this decision framework:
- Check your credit score and report to understand your starting position.
- Decide whether speed or personal support matters more to you.
- Get pre-qualified with at least three lenders across categories (bank, credit union, online).
- Compare APRs, fees, and total cost, not just monthly payments.
- Read the fine print on prepayment penalties, late fees, and variable rates.
- Choose the offer that minimizes total cost while meeting your cash flow needs.
If you have excellent credit and value a relationship, a bank may win. If you have damaged credit and need options quickly, an online lender or referral platform is likely the better path. If you are refinancing an existing loan, the math is often the same regardless of lender type: lower rate, lower payment, or shorter term.
One final note on timing. Interest rates move with the broader economy, and the difference between a good offer and a great one can be a few weeks. If you are ready to act, gather your documents now: proof of income, vehicle information, current loan statement (if refinancing), and identification. Having these ready speeds up every application, whether you go online or walk into a branch.
The choice between online auto loan lenders and traditional banks is not permanent. You can start with one, refinance later with another, and adjust as your credit and finances evolve. What matters is that you compare before you commit, understand the full cost, and pick the option that keeps your budget healthy and your car on the road.