
No Credit History Car Loan With a Cosigner: 2026 Rules
A cosigner can turn a blank credit file into an auto loan approval. See the credit and income thresholds, legal differences, and exit plan.
By Matthew Collins
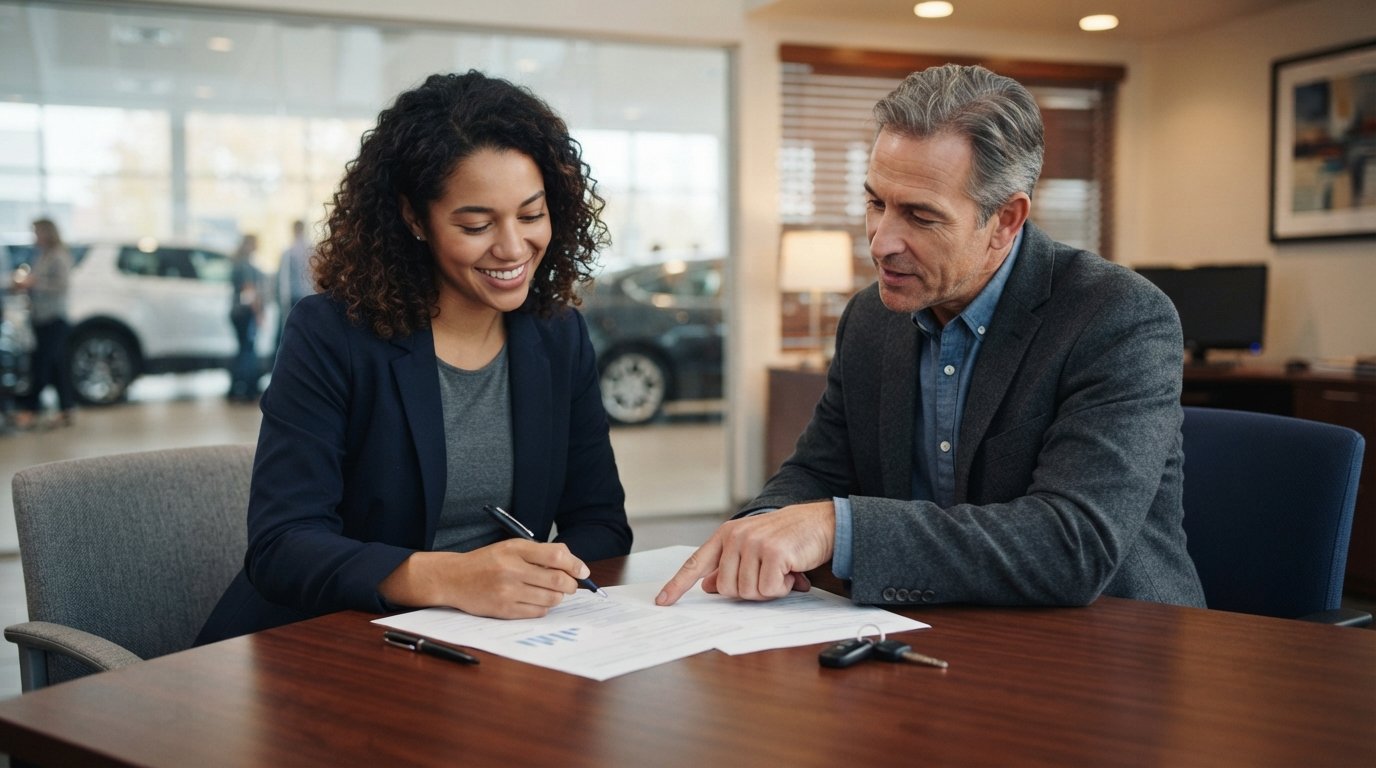
You have found the car you want, the dealer is ready to talk numbers, and then the finance manager asks about your credit. You have never carried a credit card, never had a student loan, and your only bills are a phone plan and rent. In the eyes of most auto lenders, you are a ghost. A no credit history car loan with a cosigner requirements checklist is the tool that can turn that blank file into an approval, but only if you understand exactly what the cosigner must bring to the table and what you are both signing up for.
This guide walks through the real thresholds lenders use, the legal difference between a cosigner and a co-borrower, how the account appears on both credit reports, and how to plan an exit strategy before you ever sign. The goal is not just to get approved. It is to protect the person helping you and to build a credit file that eventually stands on its own.
Why Lenders Want a Cosigner When You Have No Credit
Auto lending is collateral-based, which sounds reassuring until you realize that a repossession is expensive and slow. Lenders price risk by looking at how a borrower has handled borrowed money in the past. A thin file, meaning fewer than three to five accounts with at least a year of history, gives an underwriter almost nothing to model. A cosigner solves that problem by adding a second person whose credit history and income can be evaluated. The lender is not just betting on you. It is betting on the pair of you.
That is why a cosigner often moves an application from a subprime tier with double-digit rates into a near-prime or prime tier. The interest rate difference on a $25,000 loan over five years can easily exceed $3,000, which is the concrete reason this arrangement is worth understanding rather than treating as a formality. To see how those tiers are set and why a cosigner shifts them, read this breakdown of typical APR for car loans and how rates are determined.
Cosigner Requirements: Credit and Income Thresholds
There is no federal standard for cosigner approval, so each lender sets its own bar. Still, patterns show up across banks, credit unions, and online lenders. Most want a cosigner who already qualifies for the loan on their own, which means the cosigner's credit profile becomes the effective floor for the deal. A cosigner with a 580 score will not rescue an application that the same lender would decline on its own terms.
In practice, the requirements cluster around a few measurable items. Use this list as a pre-check before you ask anyone for help, because it saves everyone time and awkwardness:
- Credit score: commonly 640 or higher, with 680 or above opening better pricing tiers; some credit unions accept 620 with compensating factors.
- Income: enough to cover the new car payment plus existing debts at a debt-to-income ratio the lender accepts, often 40 to 45 percent including the new loan.
- Employment: stable history, typically one to two years with the same employer or in the same field.
- Debt load: no recent delinquencies, collections, or charge-offs, and no active bankruptcy.
- Residency and identity: valid government ID, US residency, and a verifiable address and phone history.
Notice that none of these requirements are about you. That is the uncomfortable truth of a no credit history car loan with a cosigner requirements structure: the lender is underwriting your helper. Your income still matters because lenders want to see that you can carry the payment, but the cosigner's file does the heavy lifting on risk. Some lenders also require the cosigner to be a US citizen or permanent resident and to live in the same state, though that varies by institution.
One more threshold matters and is often missed: the cosigner's existing debts. If your cosigner is already carrying a mortgage, a second car payment, and credit card balances near their limits, adding your loan may push their total debt-to-income ratio past the lender's cutoff. A cosigner with a perfect score but a heavy debt load can still be declined. Ask about that before you apply, not after.
Cosigner Versus Co-Borrower: The Legal Difference Matters
People use the two terms interchangeably, but the paperwork does not. A cosigner signs the note and is fully liable for the debt if the primary borrower stops paying, yet in most states the cosigner has no ownership interest in the vehicle and no right to possess it. A co-borrower is a joint owner of the car as well as a joint obligor on the loan. Both names appear on the title, and both parties have a legal stake in the asset.
That distinction drives several practical consequences. A cosigner may struggle to get the car released from the loan without the primary borrower's cooperation, because the cosigner cannot sell or trade a vehicle they do not own. A co-borrower can typically sign off on a sale or refinance. On the other hand, a co-borrower's name on the title can complicate insurance, registration, and future disputes. Lenders sometimes push first-time buyers toward co-borrower arrangements because it aligns ownership with liability, but many cosigner arrangements still use a simple cosigner structure.
Before signing, confirm in writing which structure the lender is using. Ask directly whether the second signer will appear on the title. If the answer is yes, you are dealing with a co-borrower, and the exit conversation later becomes different because a refinance will require both parties to agree.
How the Loan Reports on Both Credit Files
Both a cosigner and a co-borrower appear on the loan's tradeline, and the account reports to all three major credit bureaus for both people. For you, this is the entire point: a car loan with a cosigner is often the fastest way to generate a real installment tradeline with a payment history. Twelve to twenty-four months of on-time payments can give you a score and a file that stands on its own.
For your cosigner, the reporting cuts both ways. On-time payments add a positive account and may slightly help their profile, though the effect is usually small for someone with established credit. A single 30-day late payment hurts them as much as it hurts you, and a repossession lands on both files. If you default, the lender can pursue the cosigner for the full balance, and the cosigner's credit absorbs the damage alongside yours. That is the core risk of the arrangement, and it should be discussed in plain language before anyone signs.
There is also a utilization effect to watch. The new auto loan raises the cosigner's total debt, which can affect their debt-to-income ratio if they apply for a mortgage or another loan during the term. A cosigner who is planning a home purchase in the next year or two should think carefully before adding your car payment to their profile.
The Conversation Checklist Before You Ask Someone to Cosign
Asking a parent, relative, or close friend to cosign is a financial request wrapped in a personal one, and vague promises damage relationships. Go into the conversation with specifics. Bring a one-page summary of the car, the loan amount, the expected monthly payment, the term, and your plan for paying it. Then work through the items below together, because each one is a question the cosigner will eventually ask or wish they had asked.
- What exactly are you asking them to sign? Confirm cosigner versus co-borrower, the loan term, the interest rate, and whether the rate is fixed or variable.
- What happens if you miss a payment? Explain that the lender will call them, that late payments hit their credit, and that you will tell them immediately if you are ever short.
- How will the loan be paid? Show your budget, your income, and whether you will set up automatic payments. Consider a written agreement between the two of you, even if it is not legally binding in every state.
- What is the exit plan? Put a target date on the calendar for refinancing into your own name, typically after 12 to 24 months of on-time payments, and agree that you will pursue it.
- What if the car is totaled or stolen? Confirm that the insurance policy carries gap coverage or that you understand the shortfall risk, because the loan survives the vehicle.
That last point is the one people skip. If the car is totaled and insurance pays less than the loan balance, the remaining deficiency is still owed by both signers. Gap insurance or a loan with no negative equity at the start protects the cosigner as much as it protects you. If you are shopping for financing and have already been turned down elsewhere, services such as AutoTitleLoan.com connect borrowers with bad credit or no credit history to lenders who work with thin files, which can be a useful comparison point before you finalize a cosigned deal.
Building Your Own Credit So You Can Refinance Out
The cosigned loan is a bridge, not a destination. The exit path is a refinance into your own name once you have a score and a payment history, and the timing matters. Most lenders want to see 12 months of on-time payments on the current loan before they will approve a refinance in your name alone, and some want 24. During that window, your job is to build a file that stands without help.
Three moves do most of the work. First, never miss a payment on the car, because that tradeline is your best asset. Second, open a secured credit card or a credit-builder loan and keep utilization under 30 percent. Third, keep your income and address stable, since underwriters weight stability heavily for thin-file borrowers. After a year of clean history, get pre-qualified for a refinance and compare offers before you tell the cosigner anything is final.
When you are ready, the refinance process itself is straightforward. You apply with your own income and credit, the new lender pays off the old loan, and the cosigner is released from the note. This platform's auto refinance resources explain how to compare offers from a nationwide network of lending partners without obligation, which is the right way to shop once your file is strong enough to stand alone. Until then, protect the cosigner's credit as if it were your own, because for the length of the loan, it effectively is.
Common Mistakes That Sink Cosigned Car Loans
The failures in cosigned auto loans are predictable. The primary borrower treats the approval as permission to buy more car than the budget supports, and the payment becomes unmanageable within six months. Or the cosigner assumes the primary borrower will handle everything and never checks the account, so a missed payment goes unnoticed until it is 60 days late and reported. Or neither party discusses the exit plan, and five years later the cosigner is still on a loan for a car they have never driven.
Avoid those outcomes by keeping the loan visible to both parties. The cosigner should have online access to the account and should confirm the first payment posts correctly. The primary borrower should send a short update after each payment for the first year. None of this is dramatic. It is simply the maintenance that keeps a favor from turning into a fracture.
If you are still deciding whether a cosigner is the right route, weigh the alternatives honestly. Waiting three to six months while you build a thin credit file with a secured card is slower but avoids the personal risk entirely. Putting more money down reduces the amount financed and can sometimes get an approval without a cosigner. A cosigner is a powerful tool, but it is not the only one, and the right choice depends on how much time you have and how much risk you are asking someone else to accept.
The path from a blank credit file to an approved auto loan runs through a cosigner who meets the lender's thresholds, a clear understanding of whether that person is a cosigner or a co-borrower, and a written plan for paying on time and refinancing out. Handle those three pieces with care, and the loan becomes a credit-building milestone rather than a five-year favor that strains a relationship.