
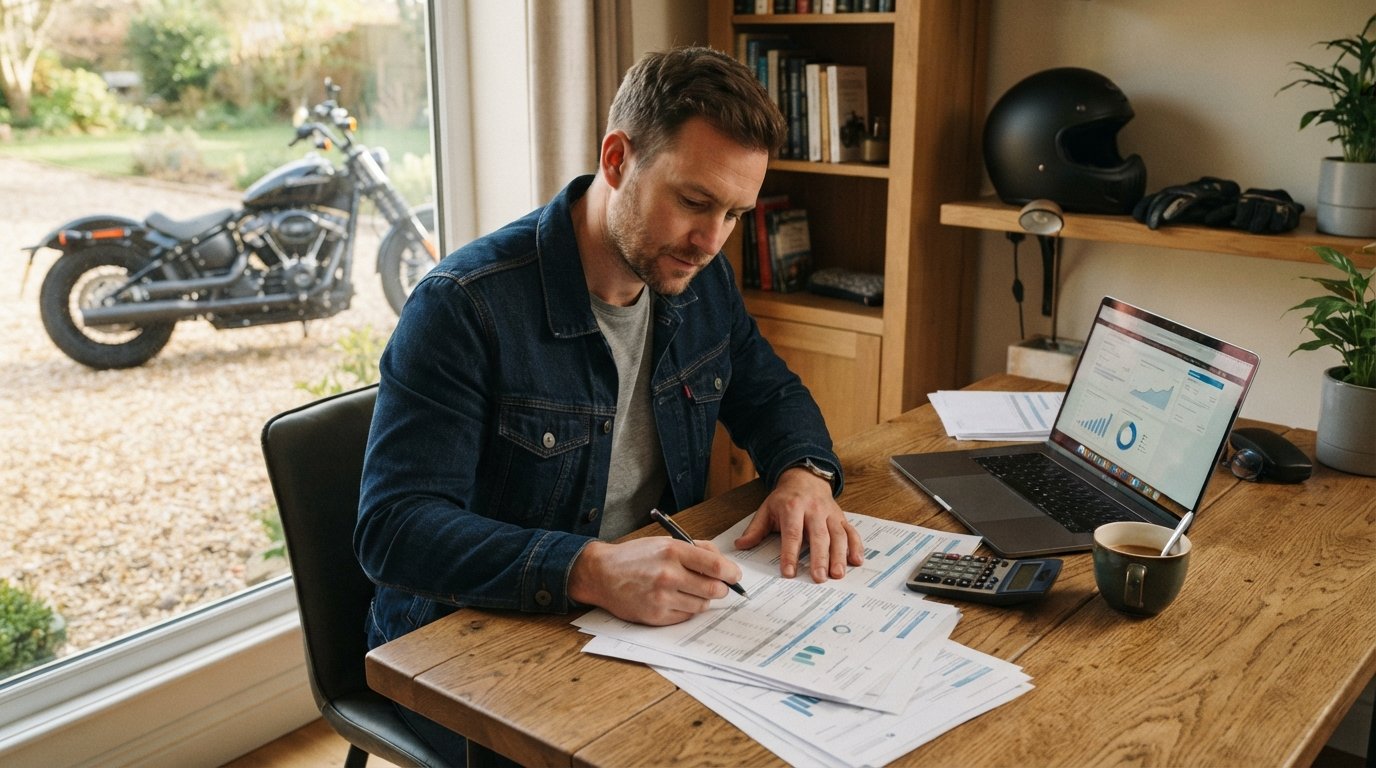
Motorcycle Loan Refinancing Options and Requirements
Motorcycle loan refinancing options and requirements explained, from rate-and-term loans to credit minimums, plus how to cut your monthly payment.
By Rachel Simmons
Your motorcycle loan payment clears your account every month, and every month you wonder whether you signed up for the best possible deal. Maybe the dealer arranged financing on the spot, maybe your credit profile has improved since then, or maybe rates have simply fallen. Whatever the reason, refinancing lets you replace your current loan with a new one that carries better terms, and the savings can be substantial: a lower interest rate, a smaller monthly payment, or a payoff date that arrives years sooner. Understanding motorcycle loan refinancing options and requirements before you apply puts you in a much stronger negotiating position and helps you avoid the paperwork headaches that trip up unprepared borrowers.
Why Refinance a Motorcycle Loan
The core math behind refinancing is simple: you take out a new loan that pays off the old one, then make payments on the new loan instead. What changes is the cost structure. A refinance can reduce your interest rate, stretch out your repayment term to shrink monthly payments, or shorten the term so you own the bike free and clear sooner. Some riders pursue all three goals at once, though lenders usually force a trade-off: a longer term lowers the payment but increases total interest.
The savings potential is real for the right borrower. Motorcycle loans often carry higher rates than auto loans because lenders view bikes as recreational collateral, and dealer-arranged financing sometimes includes markup that inflates your rate. If you bought your motorcycle when your credit was thin, damaged, or recovering from a bankruptcy, your original rate may sit several percentage points above what you qualify for today. Refinancing at a lower rate on a $15,000 balance can save well over a thousand dollars across the life of the loan.
Refinancing also offers flexibility beyond the rate itself. You might want to remove a cosigner, switch from a variable rate to a fixed rate, or add a payment protection feature. Some lenders even let you skip a payment during the transition. In our guide on how to lower your payments, we walk through the timing and payoff mechanics that make these transitions smooth.
Motorcycle Refinancing Options to Consider
Refinancing is not a single product; it is a category that includes several distinct approaches. The option you choose depends on your goals, your credit profile, and how much equity you have in the bike. Before comparing lenders, it helps to know which structure fits your situation.
- Rate-and-term refinance: The standard option. You replace your existing loan with a new one at a lower rate, a different term, or both.
- Cash-out refinance: You borrow more than you owe and take the difference in cash. Useful if you have equity and want funds for gear, repairs, or other expenses.
- Term extension: You stretch the remaining balance over more months to reduce the monthly payment. Total interest rises, so treat this as a cash-flow tool rather than a savings strategy.
- Term reduction: You shorten the payoff window, often at a slightly higher monthly payment, to eliminate the loan faster and pay less interest overall.
- Cosigner removal or addition: Some lenders allow you to restructure the loan without a cosigner once your credit improves, or to add one to secure a better rate.
Each option carries trade-offs. A cash-out refinance increases your balance and may push your loan-to-value ratio into territory that triggers a higher rate. A term extension eases monthly pressure but can leave you upside down on the bike longer. The right choice depends on whether your priority is monthly breathing room, total interest savings, or access to equity.
Lender type matters too. Banks, credit unions, and online lenders all offer motorcycle refinancing, and each brings a different appetite for risk and a different rate range. Credit unions frequently beat banks on rate for members with average credit, while online lenders tend to move faster and accept a wider credit spectrum. Comparing at least three offers gives you a realistic picture of where you stand.
Requirements You Need to Meet
Motorcycle loan refinancing requirements vary by lender, but most share a common checklist. Meeting these criteria before you apply speeds up approval and reduces the chance of a hard credit inquiry that goes nowhere.
Start with the loan itself. Most lenders refinance balances between $1,500 and $50,000, though some cap motorcycle loans lower than auto loans. The bike generally must be a street-legal, titled vehicle, and some lenders exclude older models, custom builds, or bikes with salvage titles. You will also need to show that the motorcycle is insured with comprehensive and collision coverage, since it serves as collateral.
Your personal profile matters just as much. Lenders typically look for:
- Credit score: Many programs start around 600, while the best rates go to borrowers above 720. Bad-credit motorcycle refinancing exists, but expect a higher rate.
- Income and employment: Proof of steady income, usually through pay stubs, bank statements, or tax returns.
- Debt-to-income ratio: Most lenders prefer total monthly debts below 45 to 50 percent of gross income.
- Payment history: A clean record on the current motorcycle loan strengthens your case considerably.
- Loan-to-value: Lenders rarely refinance more than 100 to 125 percent of the bike's value, so negative equity can be a hurdle.
Documentation requirements are straightforward but easy to underestimate. Gather your driver's license, proof of insurance, current loan statement, vehicle title information, and recent pay stubs before you apply. Self-employed riders should prepare two years of tax returns. If you have a cosigner, their information and credit history enter the review as well. Missing documents are the most common reason applications stall, so assemble everything in one folder first.
How to Compare Refinancing Offers
Comparing offers is where most of your savings get won or lost. The advertised rate is only one number; the annual percentage rate, or APR, bundles in fees and gives you a truer cost of borrowing. Always compare APRs, not just interest rates, and read the fine print for origination fees, prepayment penalties, and late-payment charges.
A practical comparison method is to request quotes from at least three lenders within a short window, ideally two weeks, so the credit inquiries count as a single shopping event. For each offer, note the APR, the monthly payment, the total interest you would pay, and the payoff date. A loan with a slightly higher rate but no fees can beat a lower-rate offer loaded with closing costs.
Pre-qualification tools make this easier. Many lenders let you see estimated rates with a soft credit pull that does not affect your score, so you can screen options without risk. If traditional lenders turn you down because of credit challenges, an independent connection service like StartAutoLoan can match you with financing partners who work with a broader range of credit profiles, including riders rebuilding after bankruptcy or with no established credit history.
Do not overlook the current lender. Sometimes a simple phone call produces a rate reduction or a modified payment schedule without a full refinance. It costs nothing to ask, and a retention offer can save you the entire application process. If the current lender will not budge, that is your signal to shop the market in earnest.
Step-by-Step Refinancing Process
Once you have chosen a direction, the process typically unfolds in a predictable sequence. Knowing the steps in advance keeps you from getting surprised by timing or paperwork.
- Review your current loan: Find your payoff amount, current rate, remaining term, and any prepayment penalty. This baseline tells you what a refinance must beat.
- Check your credit and gather documents: Pull your reports, correct errors, and assemble pay stubs, insurance proof, and title information.
- Shop and pre-qualify: Request quotes from multiple lenders and compare APRs, payments, and total costs side by side.
- Submit a full application: Choose your best offer, complete the application, and provide any additional documentation the lender requests.
- Close and confirm payoff: Sign the new loan agreement, confirm the old loan is paid off, and update your insurance and payment details.
Timing matters throughout. A refinance usually takes three to seven business days from application to funding, though title processing can stretch it longer in some states. Continue making payments on the old loan until you receive written confirmation that it is paid in full. Overpaying slightly and receiving a small refund is far better than missing a payment and damaging the credit you worked to improve.
Mistakes to Avoid and Tips for Approval
The most common refinancing mistake is focusing only on the monthly payment. Stretching a loan from 48 to 72 months can cut your payment by a third while adding hundreds or thousands in interest, leaving you owing more than the bike is worth for years. If cash flow is the goal, accept the longer term knowingly, and plan to make extra principal payments when you can.
Other pitfalls include applying with outdated income information, ignoring fees that erase the rate savings, and refinancing so soon after purchase that the loan-to-value ratio blocks approval. As a rule, wait until you have made at least three to six on-time payments and the bike's value has stabilized before refinancing.
To strengthen your approval odds, pay down other debts to lower your debt-to-income ratio, avoid opening new credit lines in the months before you apply, and consider adding a creditworthy cosigner if your profile is borderline. A small down payment toward the principal can also push your loan-to-value into a lender's comfort zone. Riders who prepare carefully often find that the refinancing process rewards patience and comparison shopping far more than speed.
Motorcycle loan refinancing is one of the few financial moves that can lower your payment, cut your total interest, and shorten your payoff timeline, sometimes all at once. Start by reviewing your current loan terms, check where your credit stands today, and gather quotes from several lenders before committing. The paperwork takes an afternoon; the savings can last for the life of the loan.