
Is Gap Insurance Worth It on a Car Loan? 2026 Guide
Is gap insurance worth it on a car loan? It depends on your equity position. Compare premium costs against the potential gap before you decide.
By Rachel Simmons
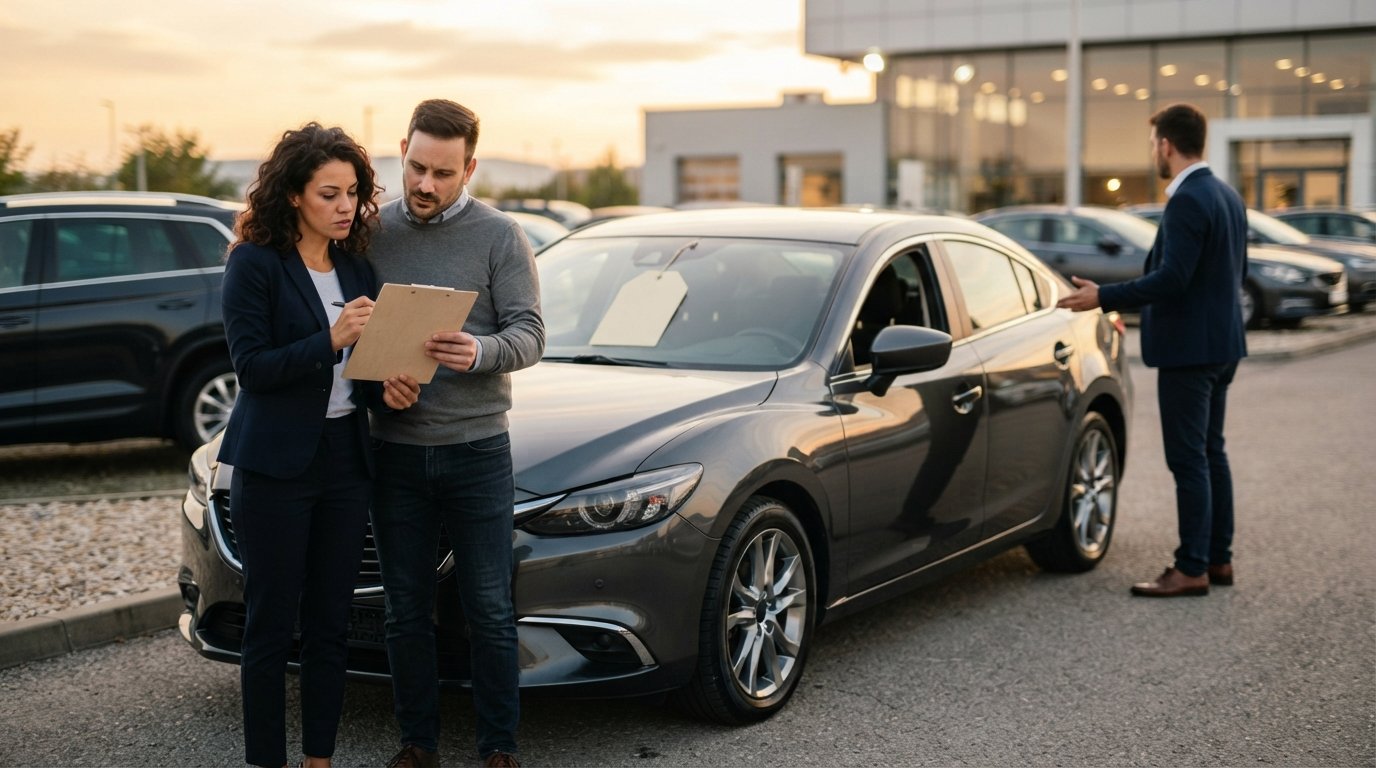
You drive a new car off the lot, and it loses thousands of dollars in value before you make the first payment. That is depreciation, and it creates a quiet financial trap that many borrowers do not see coming. If the car is totaled or stolen soon after purchase, your standard auto insurance pays only what the vehicle is worth at that moment, not what you still owe on the loan. The difference can be thousands of dollars, and you are still legally responsible for paying it. Gap insurance exists to cover that difference, but it comes at a cost, and not every borrower needs it. Understanding when it helps, when it does not, and how to evaluate the price is the key to answering the question honestly: is gap insurance worth it on a car loan?
What Gap Insurance Actually Covers
Gap insurance, sometimes called loan/lease coverage, pays the difference between your auto insurance settlement and your remaining loan balance when a vehicle is declared a total loss. Standard collision and comprehensive coverage reimburse you for the actual cash value (ACV) of the car at the time of the loss. Because new vehicles depreciate fastest in the first year, the ACV often falls well below what you owe, especially if you made a small down payment, financed for a long term, or rolled negative equity from a previous loan into the new one.
Consider a practical example. You buy a $35,000 car with $2,000 down and finance $33,000 for 72 months. Six months later, the car is stolen and never recovered. Your insurer values it at $27,000, leaving a $6,000 gap between the payout and your loan balance. Without gap coverage, you write a check for $6,000 or keep making payments on a car you no longer have. With gap coverage, the policy pays that $6,000, minus any deductible or coverage limits spelled out in the contract.
It helps to understand what gap insurance is not. It is not the same as collision or comprehensive coverage, which pay for the vehicle itself. It is not a replacement for emergency savings. And it does not cover missed payments, late fees, or carryover balances from add-ons like extended warranties. Read the contract carefully, because some policies exclude certain fees and others cap payouts at a percentage of the vehicle value.
When Gap Insurance Makes Financial Sense
Gap coverage tends to earn its keep in situations where the loan balance stays above the vehicle value for a meaningful stretch of time. The wider that gap and the longer it lasts, the more protection you get for the premium. Borrowers who put little or nothing down, stretch payments over 60 or 72 months, or finance a brand-new vehicle fall into this category most often.
These borrower profiles are the strongest candidates for gap insurance:
- Buyers who financed more than 80 percent of the vehicle price with a small down payment
- Borrowers with 60-month, 72-month, or 84-month loan terms that delay equity buildup
- Drivers who rolled negative equity from a prior trade-in into the new loan
- Lessees and buyers of new vehicles that depreciate sharply in year one
- Owners of high-theft or high-repair-cost models with expensive replacement parts
If you recognize yourself in two or more of those bullets, the math usually favors some form of gap protection. The risk is not that your car will be totaled; the risk is that it will be totaled while you are still upside down, and that is exactly when the coverage pays off.
On the other side of the ledger, gap insurance rarely makes sense once you owe less than the car is worth. If you made a 20 percent down payment, chose a 36-month term, or have been paying for two or three years, your loan balance may already sit below the ACV. In that case, the coverage protects against a risk that no longer exists, and you can redirect the premium toward the loan itself or an emergency fund. This is also a good moment to review whether your overall financing still fits your budget, and our 2026 car loan guide on interest rate trends explains how today's rates compare with what you locked in.
How Much Gap Insurance Costs and Where to Buy It
Price varies widely depending on the seller, the vehicle, and the loan amount. Dealerships often charge $500 to $900 for a gap policy, sometimes more when it is bundled with other add-ons. Auto insurers frequently offer the same protection for $20 to $60 per year, or roughly $5 to $10 added to a monthly premium. Credit unions and some lenders sell gap coverage for a one-time fee of $200 to $400. The coverage itself is similar in most cases, so the seller matters as much as the product.
That spread is why comparison shopping pays off. A policy priced at $700 through the finance office can sometimes be matched for under $100 annually through an existing auto insurer. Before you sign anything at the dealership, ask three questions:
- What is the exact premium, and is it charged upfront or added to the loan balance?
- Does the policy cover the deductible, and is there a payout cap?
- Can I cancel for a refund if I refinance or pay the loan down early?
That last question matters more than most buyers realize. If you refinance the loan a year later, the original gap policy may no longer apply, and you may be entitled to a prorated refund. Some lenders and insurers let you transfer coverage; others do not. Always get the cancellation and refund terms in writing before you pay.
The Refinance Angle Most Borrowers Miss
Refinancing changes the gap insurance calculation in two ways. First, a new loan with a lower interest rate or shorter term can help you build equity faster, which shrinks the window when you are upside down. Second, the refinance itself may reset your equity position if you stretch the term or finance fees into the new balance. If you are weighing a refinance, it helps to know how the numbers work before you commit, and our independent auto loan connection service can connect you with lenders who work with a range of credit profiles, including borrowers who have been turned down elsewhere.
Here is a simple framework for deciding whether to keep, buy, or drop gap coverage after a refinance:
- Compare your new loan balance to the current ACV of the vehicle using a valuation tool
- Estimate how many months it will take for the balance to fall below the ACV
- Multiply the monthly gap premium by that number of months to get the total cost
- Compare that total to the size of the potential gap if the car is totaled tomorrow
- Decide whether the protection is worth the price for that specific window
Run that exercise honestly, and the answer usually becomes clear. If the potential gap is $5,000 and the coverage costs $300 over the risky period, the math favors buying it. If the potential gap is $800 and the coverage costs $600, you are better off self-insuring.
Alternatives to Traditional Gap Insurance
Gap coverage is not the only way to manage the upside-down risk. Some borrowers prefer to build a small emergency fund instead, setting aside the equivalent of a few months of gap premiums until the loan balance drops below the vehicle value. Others choose a larger down payment or a shorter loan term at purchase, which reduces or eliminates the gap from day one. A few lenders offer loan products with built-in gap protection at no extra cost, though those are less common.
Each approach has trade-offs. Self-insuring keeps the money in your pocket if nothing goes wrong, but it leaves you exposed if the car is totaled early. Buying gap coverage transfers the risk for a known price, but you may pay for protection you never use. The right choice depends on your cash flow, your tolerance for risk, and how long you expect to stay upside down. There is no single correct answer, only the one that fits your situation.
A Decision Checklist You Can Use Today
Before you accept or decline gap insurance at the dealership or through your insurer, run through a short checklist. It takes ten minutes and can save you hundreds of dollars, either by avoiding an unnecessary policy or by catching a gap you did not know you had.
- Look up the current actual cash value of your vehicle using a reputable valuation tool
- Subtract that value from your current loan payoff amount to estimate your equity position
- Project how many months it will take for the balance to drop below the ACV
- Get at least two quotes for gap coverage, one from your insurer and one from the dealer or lender
- Compare total premium cost against the potential gap, then decide
If you are not sure how to read your loan payoff or amortization schedule, your lender can provide both. Many lenders also offer an online portal that shows the current payoff amount and the remaining term. Having those numbers in hand turns a vague worry into a concrete decision.
One more consideration: gap insurance is most valuable in the first 12 to 24 months of a long loan. After that, the coverage often becomes redundant. If you bought gap coverage at the dealership and your loan is now three years old, it is worth checking whether you are still paying for it and whether you can cancel for a refund. Many borrowers never revisit the decision, and the premium quietly rides along with the loan.
For borrowers who are already upside down and want to improve their position faster, refinancing to a lower rate or shorter term can be a practical first step. That is where an educational platform like CarLoanRefinancing.com fits in: it helps vehicle owners compare options, estimate savings, and connect with lending partners without pretending to be a direct lender. The goal is not to sell you a product but to give you the numbers you need to make a confident choice about gap insurance, refinancing, and everything in between.
At the end of the day, gap insurance is worth it when the cost of protection is small relative to the gap it covers, and it is a waste of money when that gap has already closed. Check your numbers, compare quotes, and let the math, not the finance office, make the call.