
How Vehicle Depreciation Affects Refinancing in 2026
Vehicle depreciation shapes your loan-to-value ratio and refinance options. Learn how to time your refi and protect your equity position.
By Daniel Harris
A car is not just a machine that gets you from point A to point B. It is also a depreciating asset, and that single fact shapes nearly every financing decision you will ever make about it. If you have ever wondered why a refinance offer looks different six months after you bought the car, or why a lender seems fixated on what your vehicle is worth rather than what you owe, depreciation is the answer. Understanding how vehicle depreciation affects refinancing is the difference between walking into a lender conversation informed and walking in blind.
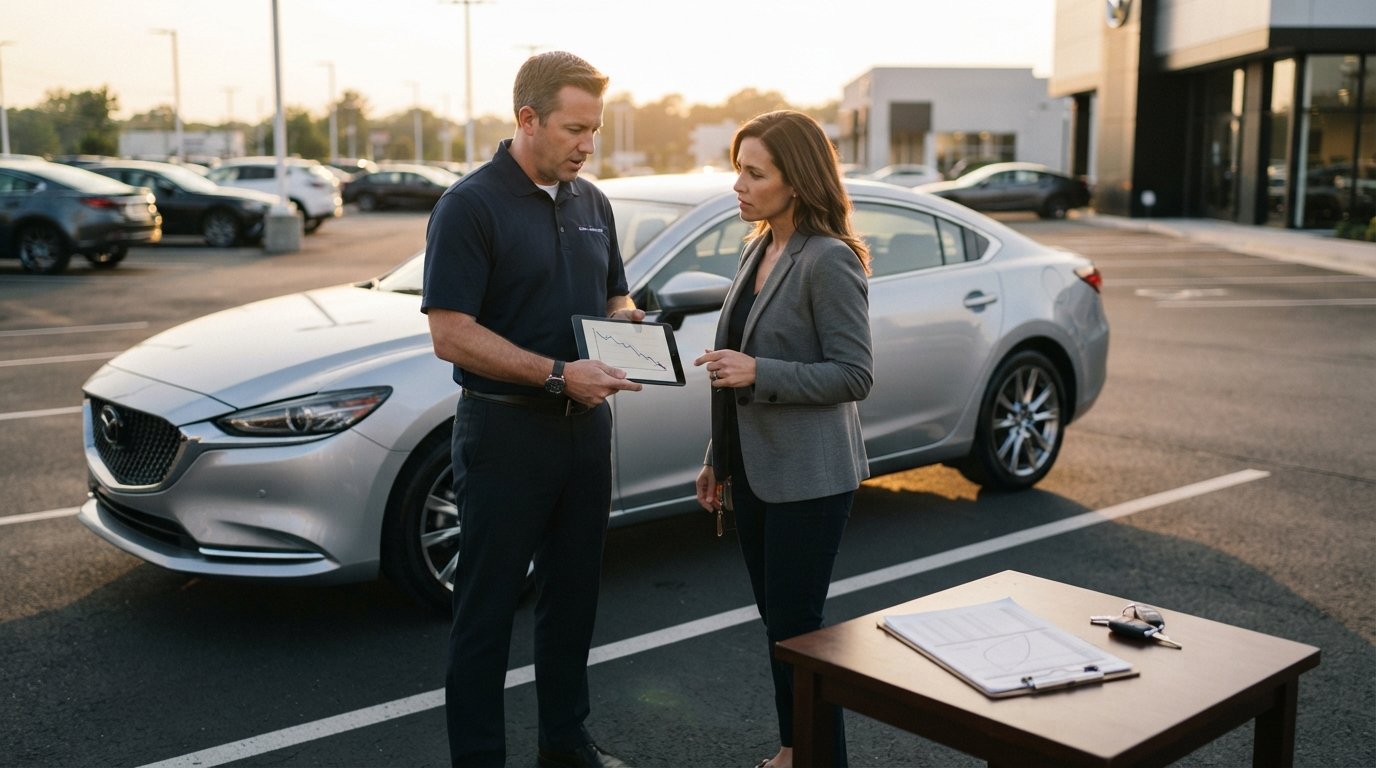
Depreciation is the steady decline in your vehicle's market value over time. A new car can lose 20 percent or more of its value in the first year alone, and roughly 60 percent within five years, according to widely cited industry estimates. That decline does not care about your credit score, your payment history, or how carefully you drive. It happens on a schedule, and it directly influences how much money a lender is willing to put at risk on your loan.
Refinancing, at its core, means replacing your current auto loan with a new one, ideally with a lower interest rate, a different term, or a more manageable monthly payment. The catch is that a refinance is a new loan, and the new lender evaluates it from scratch. That evaluation includes your credit profile, your income, and, critically, the relationship between what you owe and what the car is currently worth. When depreciation outpaces your payoff progress, that relationship becomes strained.
Why Depreciation Sits at the Center of Every Refinance Decision
When you finance a vehicle, the lender uses the car itself as collateral. If you stop paying, the lender can repossess and sell the vehicle to recover some of its money. That is why the loan-to-value ratio, or LTV, matters so much. LTV is simply your outstanding loan balance divided by the vehicle's current market value. A $25,000 balance on a car worth $25,000 is a 100 percent LTV. A $25,000 balance on a car worth $18,000 is a 139 percent LTV, which lenders call being upside down or underwater.
Depreciation pushes that ratio in the wrong direction every single month. Your balance declines slowly as you make payments, but your vehicle's value can decline much faster, especially in the first two or three years of ownership. This is the core tension of auto financing: you are paying down a debt on an asset that is shrinking in value at the same time. For refinancing purposes, this means the window in which a refinance makes strong financial sense is often narrower than borrowers expect.
Lenders respond to this risk in predictable ways. When your LTV is high, they may charge a higher interest rate to compensate for the added risk, require you to pay down part of the balance before approving the loan, or decline the application outright. Some lenders cap refinancing at 100 or 110 percent LTV, while others go higher but at a cost. Understanding where your LTV sits before you apply can save you from wasted applications and unnecessary credit inquiries.
How Depreciation Changes Your Loan-to-Value Over Time
The depreciation curve is not a straight line. It is steepest in the first year and gradually flattens out as the vehicle ages. A car that loses 20 percent of its value in year one might lose 10 to 12 percent in year two and single digits in later years. Meanwhile, your loan balance declines according to your amortization schedule, which is typically slow at the beginning because most of your early payments go toward interest rather than principal.
This mismatch creates a period, often lasting 12 to 24 months, where being upside down is almost unavoidable on a new car with little or no down payment. During this period, refinancing is difficult because no new lender wants to take on a loan that exceeds the collateral value. As time passes, the two curves eventually cross, and you build equity. That crossover point is when refinancing becomes far more achievable.
Several factors influence how quickly you reach that crossover:
- Your down payment at purchase: a larger down payment means you start with immediate equity and absorb depreciation more comfortably.
- Your loan term: shorter terms pay down principal faster, narrowing the gap between balance and value.
- Your interest rate: a lower rate means more of each payment goes to principal, accelerating your equity position.
- The vehicle itself: some models, particularly certain trucks and SUVs, hold value better than average, while luxury sedans and electric vehicles have historically depreciated faster.
- Market conditions: supply shortages, fuel prices, and shifting consumer preferences can temporarily slow or accelerate depreciation.
Each of these factors is within your influence to some degree. Choosing a shorter term, making extra principal payments, and selecting a vehicle with a strong resale record all shorten the upside-down period. When you eventually refinance, that equity position gives you leverage to negotiate better terms.
The Real Consequences of Being Upside Down When You Refinance
Being upside down does not automatically disqualify you from refinancing, but it changes the terms you can expect. The most common outcome is a higher interest rate than you might have qualified for with equity. Lenders price risk, and a high LTV is a risk factor. You may also encounter lenders who will only refinance up to a certain percentage of the vehicle's value, leaving you to cover the gap in cash.
Another consequence is that some refinance offers become less attractive than they first appear. A lower monthly payment might come from stretching the loan term rather than reducing the rate, which means you pay more interest over time and stay upside down longer. This is especially common when depreciation has eroded your equity and the only way to make the numbers work is to extend the term. Borrowers should look at the total cost of the loan, not just the monthly figure.
There is also the matter of gap insurance and negative equity carryover. If you trade in an upside-down vehicle, the negative equity does not vanish. It typically gets rolled into the new loan, which starts you off even deeper underwater. Refinancing an existing loan does not create this problem in the same way, but it does mean you are refinancing a balance that exceeds the car's value, which limits your options.
For borrowers with challenged credit, these dynamics compound. A lower credit score already means a higher base rate, and adding a high LTV on top can push offers into territory that does not justify refinancing. Platforms such as StartAutoLoan exist to connect consumers with lenders who specialize in these situations, including bad credit, no credit, and post-bankruptcy financing, which can be a useful starting point for understanding what is available before committing to a refinance.
Timing Your Refinance Around the Depreciation Curve
Timing is one of the most underrated parts of a successful refinance. Because depreciation is front-loaded, the worst time to refinance a new car is usually within the first year. You have paid down very little principal, the vehicle has lost a substantial chunk of its value, and your LTV is at its highest. Waiting even six to twelve months can meaningfully improve your position.
A practical approach is to check your vehicle's current market value every few months using a reputable valuation tool. Compare that figure to your remaining loan balance. When your LTV drops below 100 percent, you are in positive equity territory and refinancing becomes much more viable. When it drops below 80 percent, you are in the strongest position and may qualify for the best available rates.
There is also a strategic case for refinancing before depreciation accelerates further. If you have a high interest rate on your current loan and your LTV is still manageable, locking in a lower rate early can save you money even if you are slightly upside down. The savings from a rate reduction can offset the cost of a modest LTV premium. Run the numbers both ways before deciding to wait or act.
Here is a simple framework to evaluate your timing:
- Find your current payoff balance by checking your lender portal or most recent statement.
- Look up your vehicle's current market value using a trusted valuation source.
- Divide the payoff by the value to get your LTV percentage.
- Compare your current interest rate to rates you are being offered for refinancing.
- Calculate the monthly and total savings over the remaining life of the loan.
If the savings are meaningful and your LTV is at or below 100 percent, refinancing is likely worth pursuing. If your LTV is well above 100 percent, focus on paying down the balance faster or wait for depreciation to slow before applying.
Strategies to Counteract Depreciation Before You Refinance
You cannot stop depreciation, but you can manage its impact. The most direct strategy is to pay more than your minimum each month. Every extra dollar goes to principal, which lowers your balance and improves your LTV faster. Even modest additional payments can shave months off your loan and bring your equity crossover point forward.
Choosing the right vehicle in the first place is another powerful lever. Vehicles with strong resale values, such as certain Toyota, Honda, and Subaru models, depreciate more slowly than the segment average. If you are early in your ownership and considering a refinance, the vehicle you drive matters as much as the loan terms you are chasing. A car that holds value keeps your LTV healthier for longer.
Maintaining your vehicle also protects its value. A well-documented service history, clean interior, and timely repairs all support a higher resale or trade-in figure. While this does not change the depreciation curve dramatically, it can make a difference of hundreds or thousands of dollars at valuation time, which directly affects your LTV and refinance eligibility.
Refinancing itself can be part of the solution. If you can secure a lower interest rate, more of each payment goes toward principal, which slows the growth of negative equity. A shorter term has the same effect. The key is to avoid refinancing into a longer term just to lower the monthly payment, because that keeps you upside down longer and increases the total interest you pay.
What Lenders Actually Look At When Depreciation Erodes Equity
Lenders do not evaluate depreciation in isolation. They look at the full picture: your credit score, income stability, payment history, the age and mileage of the vehicle, and the current market conditions for that model. Depreciation feeds into the vehicle valuation component, but it interacts with everything else.
A borrower with excellent credit and stable income may still get approved at a high LTV, though possibly at a slightly higher rate. A borrower with marginal credit and a high LTV is a much harder case. This is why the same car and the same balance can produce very different refinance outcomes for two different people.
Vehicle age and mileage also matter independently. Lenders often have maximum age and mileage limits for refinancing, regardless of the LTV. A car that is older or has high mileage may be ineligible even if you have equity. Depreciation and eligibility rules work together to define your options, so it helps to know both before you apply.
If you are unsure where you stand, pre-qualification is a low-risk way to find out. Many lenders offer soft-pull pre-qualification that does not affect your credit score. This gives you a realistic picture of your rate range and LTV tolerance without committing to anything.
Frequently Asked Questions About Depreciation and Refinancing
Can I refinance a car that is upside down?
Yes, in some cases. Some lenders specialize in high-LTV refinancing, though the rates and terms may be less favorable. You may also need to pay down part of the balance or provide a larger down payment to bring the LTV into an acceptable range. It is worth exploring, but be realistic about the trade-offs.
How soon after buying a car can I refinance?
Most lenders prefer that you wait at least three to six months after purchase. This gives the loan time to season and allows the initial depreciation hit to settle. Refinancing too soon can also raise red flags with lenders who want to see a payment history on the current loan.
Does depreciation affect my interest rate on a refinance?
Indirectly, yes. Depreciation affects your LTV, and LTV is one of the factors lenders use to set your rate. A lower LTV generally means a lower rate because the lender has more collateral cushion. A higher LTV means more risk and typically a higher rate.
Will refinancing a depreciated car save me money?
It depends on the rate reduction and the term. If you can lower your rate meaningfully without extending the term too much, you can save money even on a depreciated vehicle. If the only way to lower your payment is to stretch the term, you may end up paying more overall.
Making Depreciation Work in Your Favor
Depreciation is often framed as a problem, but it can also be a planning tool. If you understand the curve, you can time your refinance to coincide with the point where your equity position is strongest. You can choose vehicles that depreciate slowly, structure your original loan to pay down principal faster, and avoid the trap of extending terms just to chase a lower payment.
The most important takeaway is that depreciation and refinancing are linked through the LTV ratio, and that ratio is something you can influence. By monitoring your balance and your vehicle's value, you put yourself in a position to act when the numbers make sense rather than when a lender happens to send you an offer.
Whether you are refinancing to lower your rate, reduce your payment, or simply shorten your term, the depreciation factor deserves a place in your decision. Check your numbers, understand your equity position, and compare offers from multiple lenders before you commit. A refinance that accounts for depreciation is a refinance that is more likely to deliver the savings you are looking for.