
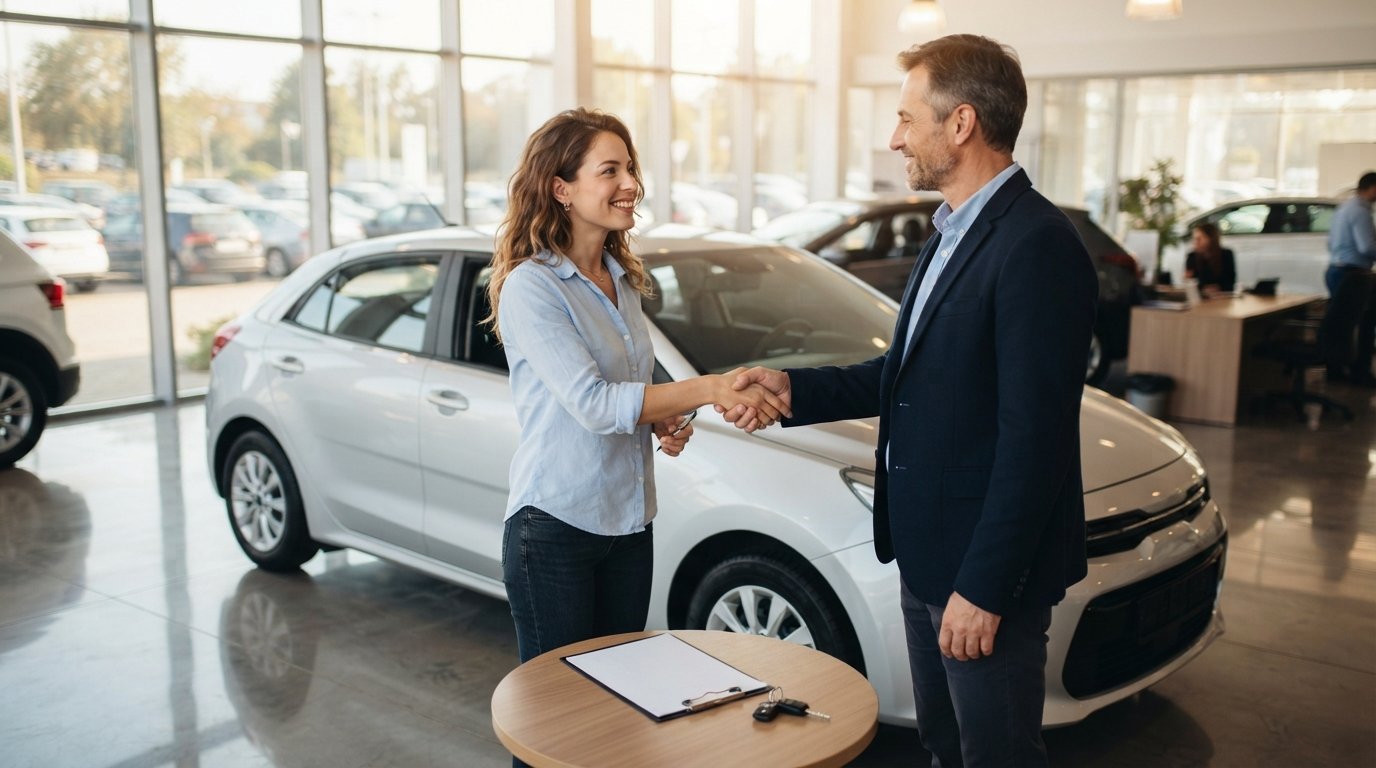
First Time Car Buyer With No Credit: Financing Options
First time car buyer with no credit financing options exist through dealer programs, credit unions, and online lenders. Learn how to qualify and build credit.
By Jonathan Hayes
Buying your first car is exciting, but it can also feel overwhelming when you have no credit history. Lenders use credit scores to predict how reliably you will repay a loan, so having no score at all can feel like a locked door. The good news is that plenty of lenders specialize in first time car buyer with no credit financing options, and they evaluate you on more than just a three digit number. With the right approach, you can drive off the lot in a vehicle you can afford while building a stronger financial foundation for the future.
Why No Credit Is Not the Same as Bad Credit
Many people assume that having no credit history is worse than having poor credit. In reality, the two situations are treated differently by lenders. A bad credit score signals past problems with repayment, such as late payments or defaults. No credit simply means you have never borrowed money in a way that gets reported to the major credit bureaus. There is no negative history to overcome, only a blank slate.
That distinction matters because some lenders view a thin file as an opportunity rather than a red flag. A first time car buyer with no credit can often qualify for financing through programs designed specifically for people who are new to credit. These programs may charge higher interest rates than what a seasoned borrower would pay, but they open the door to vehicle ownership and give you a chance to establish a positive payment history.
Understanding this difference also helps you set realistic expectations. You may not get the lowest advertised rate, but you can still find terms that fit your budget. The key is knowing where to look and how to present yourself as a responsible borrower, even without a traditional credit score.
Financing Options for First Time Buyers With No Credit
Several paths exist for first time buyers who need a loan but lack a credit history. Each option comes with its own requirements, advantages, and trade offs. Exploring multiple avenues before you commit to one can save you money and reduce stress during the car buying process.
Here are the most common financing options available to you:
- Dealer financing: Many dealerships work with lenders who specialize in first time buyer programs. They can often arrange financing on the spot, though rates may be higher than what you would find elsewhere.
- Credit unions: Credit unions frequently offer first time buyer loans with more favorable terms than traditional banks. Membership requirements are usually simple, such as living in a certain area or working for a specific employer.
- Online connection services: Platforms like StartAutoLoan connect borrowers with a network of lenders who work with no credit and bad credit situations. This can be a fast way to compare offers without visiting multiple banks.
- Co-signer loans: If you have a family member or friend with good credit who is willing to co-sign, you may qualify for better rates and terms.
- Secured loans: Some lenders allow you to use a savings account or certificate of deposit as collateral, reducing their risk and potentially lowering your rate.
Each of these options has trade offs. Dealer financing is convenient but may come with a higher rate. Credit unions often provide better customer service and lower rates, but approval can take longer. Online services give you access to multiple offers quickly, which is ideal when you want to compare without pressure. A co-signer can help you get approved at a lower rate, but it puts that person's credit at risk if you miss payments.
Before you apply anywhere, gather your documents. Most lenders will ask for proof of income, a valid driver's license, proof of residence, and possibly references. Having these ready speeds up the process and shows lenders you are organized and serious.
How to Improve Your Chances of Approval
Even without a credit score, you can take steps to make yourself a more attractive borrower. Lenders look at several factors beyond credit history, including your income, employment stability, down payment, and the type of vehicle you want to buy. Strengthening these areas can offset the lack of a credit file.
A larger down payment is one of the most effective ways to improve your odds. When you put more money down, you reduce the amount the lender has to risk. A down payment of 20 percent or more signals that you are committed and financially responsible. It also lowers your monthly payment and the total interest you will pay over the life of the loan.
Choosing a less expensive vehicle also helps. Lenders are more willing to approve a loan for a reliable used car than for a brand new luxury model. They want to know that the vehicle's value roughly matches the loan amount, so they can recover their money if you default. A practical, fuel efficient car with a strong reliability record is a smart choice for a first time buyer.
Proof of stable income is another key factor. If you have been at your job for at least six months to a year, gather pay stubs or bank statements that show consistent deposits. Self employed buyers may need to provide tax returns or profit and loss statements. The more evidence you can provide that you can afford the payments, the better your chances.
Understanding Interest Rates and Loan Terms
Interest rates for first time buyers with no credit tend to be higher than rates for borrowers with established credit. This is because lenders see you as a higher risk. However, the rate you are offered is not set in stone. You can negotiate, especially if you have a large down payment or a co-signer.
Loan term length also matters. A longer term, such as 72 or 84 months, lowers your monthly payment but increases the total interest you pay. A shorter term, such as 36 or 48 months, means higher monthly payments but less interest overall. For a first time buyer, a term of 60 months or less is often a good balance between affordability and total cost.
Be wary of add ons that dealers may try to include, such as extended warranties, gap insurance, or paint protection. These can increase the amount you finance and the interest you pay. Some add ons are valuable, but you should understand what you are paying for and decide whether you truly need them. You can often purchase similar coverage elsewhere for less.
Before you sign anything, read the loan agreement carefully. Look for the annual percentage rate (APR), the total amount financed, the monthly payment, and any prepayment penalties. If you plan to refinance later or pay off the loan early, a prepayment penalty could cost you money. Ask questions about anything you do not understand. A reputable lender will take the time to explain.
Building Credit While You Pay Off Your Car Loan
Your car loan is an opportunity to build credit from scratch. Every on time payment you make is reported to the credit bureaus, gradually establishing a positive payment history. After six to twelve months of consistent payments, you may see your credit score start to appear and rise. This can open doors to better financial products in the future, such as credit cards with rewards or lower interest rates on future loans.
To make the most of this opportunity, set up automatic payments from your bank account so you never miss a due date. Keep your other debts low and avoid applying for multiple new credit accounts at once. If you can, make payments more frequently than required, such as biweekly instead of monthly, to reduce the principal faster and pay less interest.
After a year or two of on time payments, you may be able to refinance your auto loan at a lower rate. Refinancing replaces your current loan with a new one that has better terms. This can lower your monthly payment, reduce your interest rate, or shorten your loan term. Many lenders, including the network partners at CarLoanRefinancing.com, specialize in helping people refinance auto loans even with limited credit history.
When you are ready to refinance, gather your current loan statement, proof of income, and vehicle information. Applying through a connection service can help you compare offers from multiple lenders quickly. Just like your initial loan, a refinance is a chance to improve your credit and save money.
Common Mistakes to Avoid
First time buyers often make avoidable mistakes that cost them money or limit their options. One common error is focusing only on the monthly payment and ignoring the total cost of the loan. A low monthly payment over a long term can mean thousands of dollars in extra interest. Always look at the total amount you will pay, not just what you owe each month.
Another mistake is buying more car than you can afford. Lenders may approve you for a larger loan than you should comfortably take on. A general rule is to keep your total vehicle expenses, including loan payment, insurance, fuel, and maintenance, below 15 to 20 percent of your monthly take home pay. Sticking to this guideline helps you avoid financial strain.
Some buyers also skip the pre approval step. Getting pre approved by a lender before you shop gives you a clear budget and shows dealers you are a serious buyer. It also helps you avoid the pressure of dealer financing, which may not offer the best terms. Pre approval is not a guarantee, but it is a strong indicator of what you can afford.
Finally, do not ignore your credit report. Even if you have no score, you may have errors or accounts you forgot about. You are entitled to a free copy of your credit report from each of the three major bureaus every year. Review it for accuracy and dispute any errors. A clean report, even with no score, makes a better impression on lenders.
Where to Start Your Search
When you are ready to pursue financing, start by checking your credit report and gathering your documents. Then decide which type of lender you want to approach first. Credit unions are a good option if you qualify for membership and can wait a few days for a decision. Online connection services are ideal if you want to compare multiple offers quickly and apply from home.
If you enjoy outdoor adventures and need a loan for a recreational vehicle, you can also explore RVing financing options for motorhomes and travel trailers to see how lenders evaluate these larger purchases. The same principles of income proof, down payment, and vehicle choice apply, though loan amounts and terms may differ.
No matter which path you choose, remember that your first auto loan is a stepping stone. It is not just about getting a car today; it is about building a credit history that will serve you for years. By making on time payments and managing your loan responsibly, you set yourself up for better rates and more options in the future.
With patience and preparation, a first time car buyer with no credit can find financing that works. Explore your options, ask questions, and take your time. The right loan is out there, and the effort you put in now will pay off down the road.