
Co-Signer vs Co-Borrower Auto Loan Difference Explained
Understand the co-signer vs co-borrower auto loan difference: one shares ownership, the other only liability. Choose right to protect credit and relationships.
By Christopher Reed
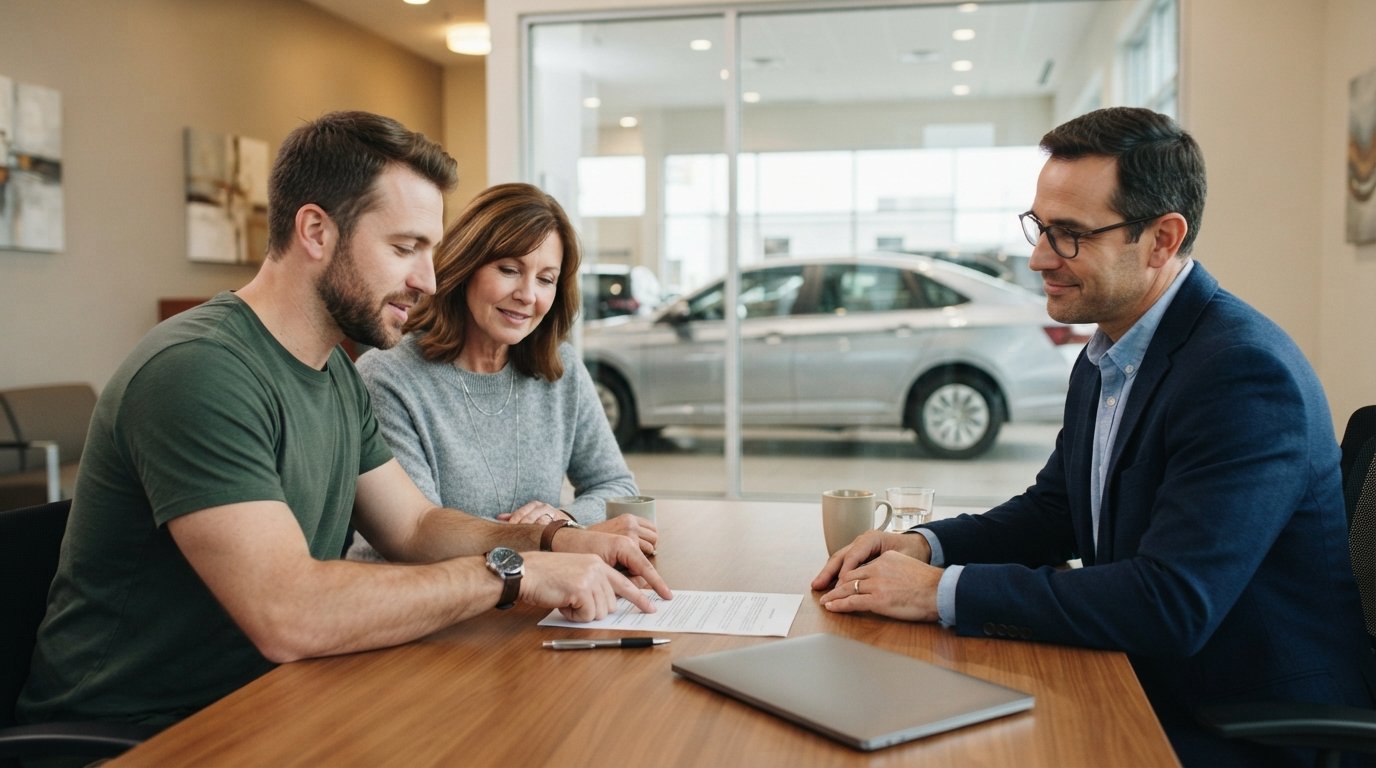
When you need help qualifying for a car loan, two terms get tossed around constantly: co-signer and co-borrower. Many people use them interchangeably, but the co-signer vs co-borrower auto loan difference can mean thousands of dollars in liability, credit impact, and legal responsibility. Choosing the wrong role for a family member or friend can damage relationships and finances. Understanding exactly how each arrangement works, who owns the car, and who is on the hook if payments stop is essential before you sign anything. This guide breaks down the distinctions, the risks, and the situations where each option makes sense.
What Is a Co-Signer on an Auto Loan?
A co-signer is someone who agrees to be responsible for a loan if the primary borrower defaults. The co-signer does not own the vehicle, does not have driving rights, and typically does not make payments. Their role is purely supportive: they lend their credit profile to help the primary borrower qualify for better terms or qualify at all. Lenders view the co-signer as a safety net, which reduces their risk and can lead to lower interest rates or higher approval odds.
The critical point is that a co-signer is still legally liable. If the primary borrower stops paying, the lender can pursue the co-signer for the full remaining balance, late fees, and collection costs. This liability appears on the co-signer's credit report as an active account, which can affect their debt-to-income ratio when they apply for their own loans. Many co-signers do not realize that this obligation can last for the entire loan term, often five to seven years.
Co-signers also have no legal right to the car. They cannot take possession of the vehicle if the borrower defaults, nor can they sell it. Their only recourse is to pay the loan and then try to recover money from the borrower through civil action, which is often impractical. This lack of control is a major reason financial experts urge caution before agreeing to co-sign.
What Is a Co-Borrower on an Auto Loan?
A co-borrower is a joint owner of the vehicle and the loan. Both parties are equally responsible for repayment, and both names appear on the title. This means the co-borrower has full rights to use the car, sell it (with the other borrower's consent), and build credit through on-time payments. Lenders consider both incomes and credit scores when evaluating the application, which can lead to larger loan amounts or better rates than a single borrower could obtain alone.
Because the co-borrower is on the title, they share ownership. This is a crucial distinction from a co-signer. If the relationship sours or the primary borrower wants to sell the car, the co-borrower must agree. Conversely, if the co-borrower wants out, they cannot simply walk away; they must refinance the loan or have the other party buy out their interest. This shared ownership creates both rights and complications.
In terms of credit impact, both parties' credit reports show the loan, and payment history affects both scores equally. A missed payment hurts both, while consistent on-time payments help both. Co-borrowers can also use the vehicle as collateral for other loans only with mutual agreement, since the title lists both names.
Key Differences Between Co-Signer and Co-Borrower
The co-signer vs co-borrower auto loan difference boils down to ownership, liability, and control. A co-signer guarantees the loan but has no ownership stake; a co-borrower owns the car jointly and shares full responsibility. This distinction affects everything from insurance requirements to tax deductions to bankruptcy proceedings.
Here is a quick comparison of the main differences:
- Ownership: Co-signer has no ownership; co-borrower is a joint owner on the title.
- Liability: Both are legally liable, but co-borrower liability is equal and immediate; co-signer liability is secondary and triggered by default.
- Credit reporting: Both appear on credit reports, but co-borrower accounts often carry more weight because of joint ownership.
- Rights to the vehicle: Co-signer cannot drive or sell the car; co-borrower can use and sell with consent.
- Exit strategy: Co-signer can be removed only by refinancing in the primary borrower's name; co-borrower must refinance or be bought out.
Another practical difference involves insurance. Lenders typically require the co-borrower to be listed on the insurance policy since they have an ownership interest. Co-signers usually do not need to be on the policy because they have no ownership stake. This can affect premiums and coverage decisions.
From a lender's perspective, a co-borrower strengthens the application more than a co-signer because both incomes and both credit histories are considered for repayment capacity. A co-signer mainly adds credit strength, not income. If the primary borrower has sufficient income but poor credit, a co-signer may suffice. If income is the problem, a co-borrower is often the better solution.
When Should You Use a Co-Signer?
A co-signer makes sense when the primary borrower has a thin or damaged credit file but can afford the payments on their own. For example, a young adult with no credit history might need a parent to co-sign to get approved for a first car loan. The parent is not contributing to payments but is lending their credit score to secure a lower rate.
This arrangement works best when the relationship is strong and the primary borrower is financially responsible. It is also useful for someone rebuilding credit after bankruptcy or divorce. The co-signer should be fully aware that the loan appears on their credit report and that they are liable for the entire balance if things go wrong.
Before agreeing to co-sign, consider these protective steps:
- Review the primary borrower's budget and payment history to confirm they can afford the loan.
- Set up automatic payments from the borrower's account to avoid missed due dates.
- Request access to the loan account so you can monitor payment status.
- Agree in writing on what happens if the borrower falls behind, including a plan for you to take over payments temporarily.
Even with these safeguards, co-signing carries risk. Lenders are not required to notify you before sending the account to collections, and a default can tank your credit score. If you are not comfortable with that possibility, a co-borrower arrangement or a different financing path may be better.
When Should You Use a Co-Borrower?
A co-borrower is ideal when two people will share the car and the payments. For instance, a married couple buying a family vehicle will often apply as co-borrowers to combine incomes for a larger loan or better rate. Since both will drive the car and contribute to payments, joint ownership makes practical sense.
Co-borrowing is also common when one person has strong credit and the other has strong income, but neither qualifies alone. By combining profiles, they present a lower risk to the lender. However, this arrangement requires trust and clear communication because both parties are equally responsible for the debt and both have a legal right to the vehicle.
If you are considering a co-borrower arrangement, ask these questions first:
- Who will drive the car most of the time, and who will pay for insurance, maintenance, and fuel?
- What happens if one person wants to sell the car or move out of state?
- How will you handle a missed payment or a financial emergency?
- Are you both prepared for the credit impact, positive or negative?
These conversations can prevent conflicts later. Unlike a co-signer, a co-borrower cannot simply be removed from the loan without refinancing. The joint ownership and liability are permanent until the loan is paid off or refinanced.
Impact on Credit Scores and Future Borrowing
Both co-signing and co-borrowing affect your credit. The account appears on your credit report, and payment history is reported for both parties. On-time payments can boost your score by adding a positive tradeline and demonstrating responsible credit management. Late payments, defaults, and collections can cause significant damage, dropping scores by 100 points or more.
The co-signer vs co-borrower auto loan difference also matters for debt-to-income ratio. Lenders calculate DTI by dividing monthly debt payments by gross monthly income. A co-signed or co-borrowed auto loan counts toward your DTI, which can make it harder to qualify for a mortgage or another car loan. In some cases, you may need to provide proof that the primary borrower has been making payments for 12 months to exclude the loan from your DTI, but this is not guaranteed.
If you are already struggling with high car payments, refinancing could be a smarter path than adding a co-signer or co-borrower. Our guide on vehicle loan vs auto loan differences explained covers how different loan structures affect your options. Refinancing allows you to change terms, lower rates, or remove a co-signer after building credit.
For those with bad credit or no credit history, finding a lender willing to approve a refinance can be challenging. Platforms like StartAutoLoan connect borrowers with lenders who specialize in challenging credit situations, offering a way to explore options without damaging your credit further.
Legal and Financial Risks to Consider
Both roles carry legal and financial risks. As a co-signer, you can be sued for the remaining balance, and the lender can garnish your wages or place a lien on your assets. Your credit score can suffer, and you may have difficulty getting approved for your own loans. As a co-borrower, you share ownership, which means you are responsible for insurance, maintenance, and any accidents or tickets associated with the vehicle. If the other borrower files for bankruptcy, you may be held responsible for the entire debt.
There is also the risk of relationship damage. Money disputes are a leading cause of family and friend conflicts. Before entering either arrangement, have an honest conversation about expectations, worst-case scenarios, and exit plans. Put your agreement in writing, even if it is not legally binding, to clarify intentions and reduce misunderstandings.
In community property states, a co-borrower arrangement can complicate divorce proceedings. The car and loan may be considered marital property, requiring division or refinancing. A co-signer arrangement is less entangled but still creates financial ties that can be difficult to sever.
How to Choose the Right Option
Choosing between a co-signer and co-borrower depends on your goals and the primary borrower's situation. If the goal is to help someone qualify without sharing ownership, a co-signer is appropriate. If the goal is to share the car and combine resources, a co-borrower is the better fit.
Consider these factors:
- Ownership: Do you want to own the car? If yes, be a co-borrower. If no, co-sign.
- Liability: Are you prepared to pay the full loan if the other party defaults? Both roles require this, but co-borrower liability is immediate.
- Credit impact: Both affect your credit. Co-borrower accounts may have a larger impact on DTI.
- Exit strategy: Co-signers can be removed by refinancing. Co-borrowers must refinance or sell the car.
- Relationship: Co-borrowing requires more trust and communication due to shared ownership.
If you are unsure, consult a financial advisor or attorney. They can review your specific circumstances and help you understand the long-term implications. Never sign a loan agreement without reading the fine print and understanding your obligations.
If you already have a co-signed or co-borrowed loan and want to remove the other party, refinancing may be the answer. Refinancing in your own name, based on your improved credit and income, can release the co-signer from liability and give you sole ownership. CarLoanRefinancing.com offers tools and resources to compare refinance rates and terms from multiple lenders, making it easier to find a solution that fits your budget.
In the end, the co-signer vs co-borrower auto loan difference is not just semantics. It is a legal and financial distinction that affects ownership, liability, credit, and relationships. Choose wisely, communicate openly, and consider alternatives like refinancing or improving your credit before adding another person to your loan.