
Chapter 13 Car Loan Refinance: Rules While Plan Is Active
Refinancing a car loan in an active Chapter 13 plan usually requires court or trustee approval. Learn the rules, paperwork, and timing to avoid plan risks.
By Sarah Mitchell
If you are in an active Chapter 13 bankruptcy and your car loan is weighing on your budget, refinancing might seem like a straightforward fix. But the rules are not simple: any new credit, including a refinanced auto loan, generally requires approval from the bankruptcy court or your Chapter 13 trustee. Missing that step can jeopardize your plan and your discharge. This guide explains the chapter 13 car loan while plan is active refinance rules you need to know, from why approval is required to how a refinance affects your plan payments, what documentation trustees expect, and the timing around confirmation and completion. If you are considering refinancing outside of bankruptcy, our guide on Ally car loan refinance options and rates covers conventional lender options, but inside an active plan the process follows a different set of rules.
Why Court or Trustee Approval Is Usually Required
Chapter 13 is a reorganization bankruptcy. You propose a plan to repay some or all of your debts over three to five years, and the court supervises that plan. Taking on new debt while the plan is active is not a private decision between you and a lender. Under the Bankruptcy Code and standard plan provisions, you generally cannot incur new debt without court approval. A refinance is new debt because it replaces an existing loan with a new obligation, even if the purpose is to lower your payment.
The trustee and the court want to ensure that any new financing does not undermine your ability to complete the plan. If a refinance lowers your monthly payment, that could free up cash for plan payments or necessary expenses. But if the refinance extends the loan term, increases the total cost, or adds fees, it could reduce the funds available to creditors. The approval process exists to evaluate those tradeoffs. Courts also consider whether the new loan is in your best interest and whether it is necessary, for example to avoid a repossession or to afford a reliable vehicle for work.
Some plans include specific language about incurring debt. Many standard plans prohibit new debt above a certain threshold without trustee approval. Even if your plan is silent, the general rule applies: you should not refinance without permission. Ignoring this rule can lead to motions to dismiss your case, loss of the automatic stay, or objections to your discharge. The safest approach is to assume that you need approval and to build that step into your refinance timeline.
How a Refinance Affects Plan Payments and Your Budget
Your Chapter 13 plan is built around your disposable income, which is calculated from your income and necessary expenses. Your car payment is part of that budget. If you refinance and lower your monthly car payment, your disposable income might increase, which could mean higher plan payments to creditors. Conversely, if the refinance reduces your payment enough, you might be able to keep the plan payment the same and use the savings for other necessary expenses, but only if the court approves. The key is that the court and trustee must see how the new loan fits into your budget.
Refinancing can also affect how your car is treated in the plan. If you owe more than the car is worth, the plan might have crammed down the loan to the vehicle's value, with the remaining balance treated as unsecured debt. Refinancing that loan could change that treatment. Some lenders are reluctant to refinance a crammed-down loan because the new loan would be a new obligation. You need to discuss the specific treatment of your car loan with your bankruptcy attorney before applying for a refinance.
Here are the main ways a refinance can interact with your plan budget:
- Lower payment: Frees up cash but may increase your plan payment if your disposable income rises.
- Longer term: Reduces the monthly payment but increases total interest, which the trustee may question.
- Higher payment: Generally not approvable unless you can show a necessary expense increase or other justification.
- Fees and costs: Refinance closing costs must be disclosed and may need to be paid from the plan or your budget.
- Vehicle value: If the new loan exceeds the car's value, the trustee may object that you are taking on unnecessary debt.
After you have a proposed refinance offer, you and your attorney should prepare an updated budget showing the new payment and how it affects your plan. The trustee will want to see that the refinance does not impair your ability to make plan payments or pay necessary living expenses.
Documentation a Trustee Expects With a Request
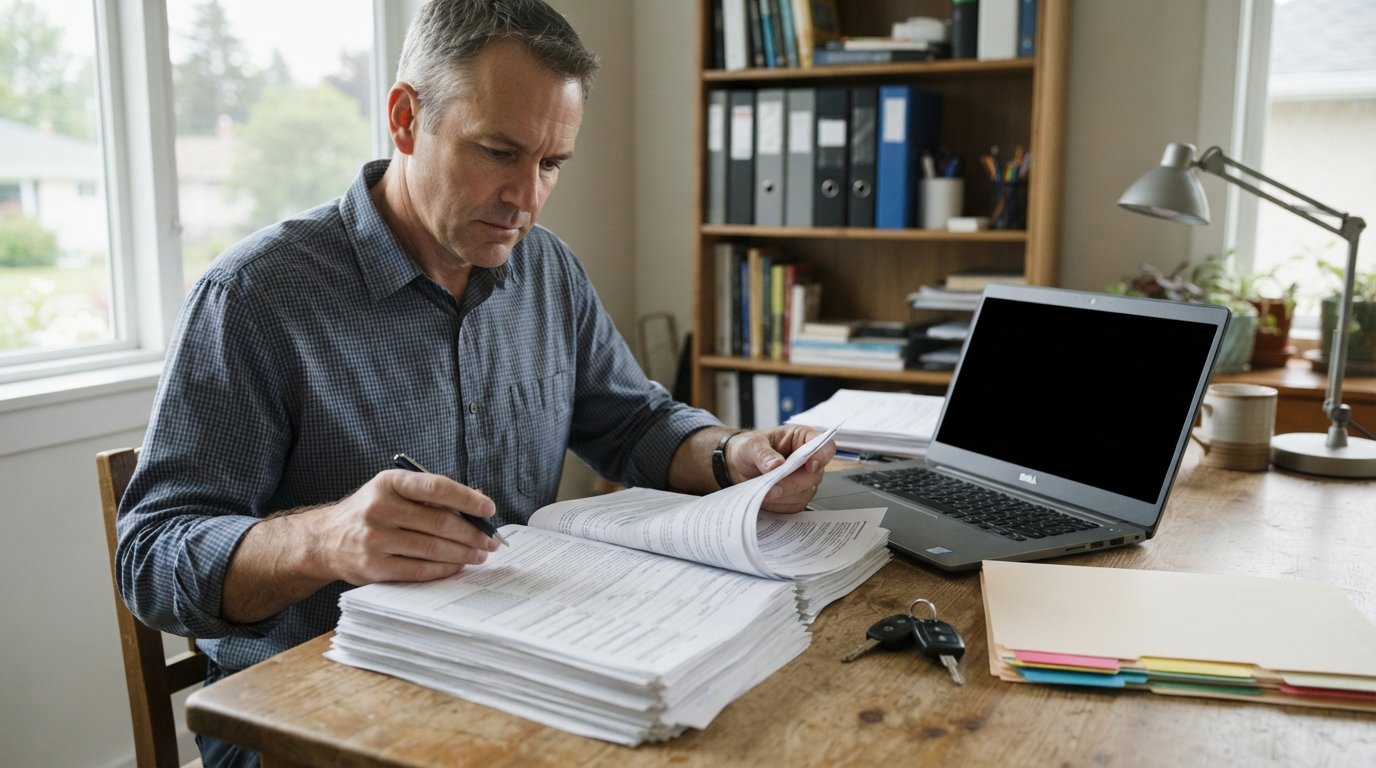
To approve a refinance, the trustee typically requires a written request or motion, often filed by your attorney. The request should explain why the refinance is necessary, what the new terms are, and how it affects your plan. Trustees see many such requests, so a complete and organized package speeds up the process and reduces the chance of objections.
The exact requirements vary by district and trustee, but the following documents are commonly expected:
- Refinance application or offer: A written offer from the lender showing the new loan amount, interest rate, monthly payment, term, and fees.
- Current loan statement: A statement from your existing lender showing the payoff amount and payment history.
- Updated budget: A revised income and expense schedule reflecting the new payment and any change in disposable income.
- Explanation of benefit: A short statement describing why the refinance is in your best interest, such as a lower interest rate or a payment you can afford.
- Vehicle information: The car's make, model, year, mileage, and value, often supported by a valuation guide.
- Proof of insurance: Evidence that the vehicle will remain insured, with the lender named as loss payee if required.
Your attorney will know the local rules and can tailor the request. If you are representing yourself, contact the trustee's office to ask what they require. Keep copies of everything you submit and follow up politely if you do not receive a response within the expected time.
For borrowers who are not in bankruptcy but have faced rejections from traditional lenders, platforms such as AutoTitleLoan connect consumers with financing options, though the bankruptcy approval process described here still applies to anyone in an active Chapter 13 plan.
Timing Around Plan Confirmation or Completion
The timing of your refinance request matters. If your plan has not yet been confirmed, the court may be more willing to approve a refinance that makes the plan feasible. For example, if your current car payment is too high and a refinance would free up money to fund the plan, the trustee might support the request as part of the confirmation process. In that case, the refinance can be included in or approved alongside the plan.
After confirmation, the plan is binding, and changes require a plan modification or a separate motion. Refinancing after confirmation is still possible, but you need to show that the change is consistent with the plan and does not prejudice creditors. Some trustees are more receptive to refinances that lower payments and increase the likelihood of plan completion. Others may object if the refinance primarily benefits you at the expense of creditors.
Near the end of your plan, refinancing may be less necessary. If you are close to completing your plan and receiving a discharge, you might be better off waiting. After discharge, you can refinance without court approval, although you should still compare offers and check your credit. If you need a lower payment urgently to avoid default, a refinance during the plan may be worth pursuing, but you should discuss the timing with your attorney. The court may also consider whether the refinance will extend beyond the plan period and whether that affects your post-discharge obligations.
Risks of Taking on New Debt Inside a Plan
The biggest risk is doing it without approval. Incurring new debt without court permission can be treated as a violation of the plan or the Bankruptcy Code. Consequences can include a motion to dismiss your case, a motion to lift the automatic stay (allowing a lender to repossess), or an objection to your discharge. Even if you had good intentions, the court may view the undisclosed debt as evidence that you cannot manage your finances, which can affect the outcome of your case.
Even with approval, refinancing carries risks. A longer term can reduce your monthly payment but increase the total interest you pay. Fees can be rolled into the new loan, increasing your balance. If you refinance a crammed-down loan, you may lose the benefit of that cramdown. And if your financial situation changes during the plan, a new loan with a higher payment could make it harder to complete your plan. You should also consider the impact on your credit report and your ability to qualify for future financing.
Before you apply, review the proposed terms carefully and compare them to your current loan. Use a calculator to estimate the total cost over the life of the loan, not just the monthly payment. Ask your attorney to review the offer and the approval request. If the refinance does not clearly improve your situation, it may be better to wait until after discharge.
Refinancing a car loan during an active Chapter 13 plan is possible, but it requires court or trustee approval, a clear explanation of how the new loan fits your budget, and the right documentation. By understanding the chapter 13 car loan while plan is active refinance rules and working with your attorney, you can avoid costly mistakes and make a decision that supports your plan and your financial recovery.