
Car Loan for Self Employed Borrowers: Income Verification
Self employed and need a car loan? Learn which documents prove income, how lenders calculate qualifying income, and how to boost approval odds.
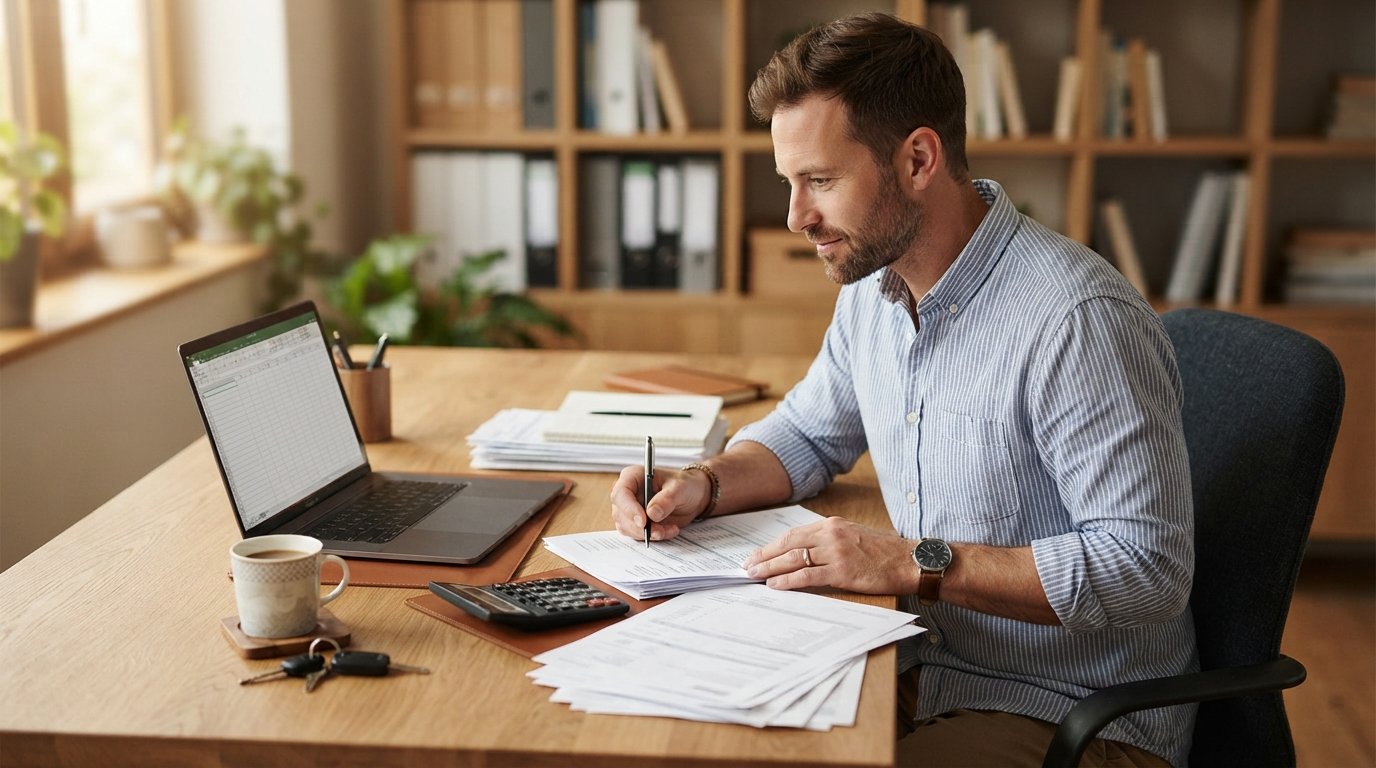
Getting a car loan when you are self employed often feels like a maze of paperwork and shifting rules, especially when a lender asks for income verification and you do not have a traditional pay stub to hand over. The good news is that lenders have adapted. They know that millions of Americans earn their living through freelance work, gig economy jobs, small businesses, and independent contracting. The key is understanding exactly how income verification works for self employed borrowers, what documents you need, and how to present your financial picture in the strongest possible light.
Whether you are buying a new vehicle, refinancing an existing loan, or simply exploring options, the verification process follows a predictable path. Once you know that path, you can prepare ahead of time and avoid the back and forth that delays approvals. This guide walks you through the documents lenders accept, how they calculate qualifying income from tax returns and bank statements, why debt to income ratios matter even more when your earnings fluctuate, and practical steps to improve your approval odds before you apply through a lender network.
Documents Self Employed Borrowers Can Use to Prove Income
The first hurdle for any self employed applicant is proving that the income you report is real, stable, and likely to continue. Traditional employees can rely on recent pay stubs and a W-2, but self employed borrowers need a different toolkit. Most lenders accept a combination of documents that together paint a complete picture of your earnings. The exact list varies by lender, loan type, and how long you have been in business, but the following items are commonly requested.
- Personal tax returns: Typically the last two years of federal returns, including all schedules and attachments. Lenders want to see consistent income and how you report business expenses.
- Business tax returns: If your business files separately, lenders may require the last two years of business returns as well, especially if you take a salary or distributions from the business.
- Bank statements: Three to twelve months of personal and business bank statements can help verify deposits and cash flow, particularly for lenders that offer bank statement loans.
- Profit and loss statement: A year to date profit and loss statement prepared by you or your accountant shows current performance and can bridge the gap between last years tax return and today.
- 1099 forms and invoices: If you work as an independent contractor, 1099s from clients and a sampling of invoices can support your reported income.
It is important to note that not every lender will ask for every document. Some may accept tax returns alone, while others specialize in bank statement loans for borrowers who write off a lot of expenses and therefore show lower taxable income. Your best move is to gather the core documents first (two years of tax returns and recent bank statements) and then ask the lender what else they need. Being organized and responsive can make the difference between a smooth approval and a stalled application.
If you are also shopping for a used vehicle, keep in mind that used car loan interest rates can vary widely based on your credit profile and income documentation. Having your verification documents ready before you start comparing rates will help you move quickly when you find a vehicle you want to finance.
How Lenders Calculate Qualifying Income from Tax Returns and Bank Statements
Lenders do not simply look at the top line of your tax return and call it a day. They dig into the details to determine a stable, qualifying income figure that they can use in their underwriting models. This is where many self employed borrowers get surprised: the income you live on and the income a lender counts are not always the same number.
When lenders review tax returns, they typically start with your adjusted gross income and then add back certain deductions that are not actual cash expenses, such as depreciation. They may also average your income over two years to smooth out fluctuations. If your income has been rising, some lenders will use the most recent year, but many prefer a two year average to ensure consistency. The goal is to arrive at a conservative figure that represents your ability to repay the loan each month.
Bank statement loans take a different approach. Instead of relying on tax returns, lenders analyze your bank statements to calculate average monthly deposits. They may exclude transfers between accounts, one time windfalls, and other non recurring items. Some lenders use a factor, such as 50 percent of gross deposits, to account for business expenses. This method can be helpful for borrowers who have significant write offs that reduce their taxable income but who still have strong cash flow.
Understanding these calculations helps you anticipate what a lender will see. If your tax returns show modest income because you claim many deductions, a bank statement loan might present your finances more favorably. Conversely, if your income is steady and well documented on your returns, a traditional tax return based loan could offer better terms. The key is to discuss your situation with lenders or a referral service that can match you with partners who specialize in self employed borrowers.
Why Debt to Income Ratios Matter More for Variable Income Borrowers
Debt to income ratio, or DTI, is one of the most important metrics lenders use to evaluate loan applications. It compares your total monthly debt payments to your gross monthly income. For self employed borrowers, DTI takes on added significance because your income may fluctuate from month to month or year to year. Lenders want to see that you can comfortably handle a new car payment even in a slower month.
A lower DTI signals to lenders that you have room in your budget to absorb a new obligation. Most lenders look for a DTI below 40 to 50 percent, though the exact threshold varies. If your income is variable, a lender may use a conservative income figure when calculating your DTI, which can push your ratio higher. That is why it is crucial to reduce other debts before applying or to choose a loan amount that keeps your DTI in a comfortable range.
For example, suppose your two year average monthly income is $5,000 and you have $1,500 in existing monthly debt payments. Your current DTI is 30 percent. If you add a $400 car payment, your DTI rises to 38 percent, which is still within many lenders comfort zones. But if the lender only counts $4,200 of your income due to deductions, that same $400 payment pushes your DTI to 45 percent, which could lead to a denial or a higher interest rate. Running these numbers ahead of time helps you set realistic expectations and adjust your strategy.
If your DTI is tight, consider paying down credit card balances or consolidating debt before you apply. Even a small reduction in monthly obligations can improve your ratio and increase your approval odds. And remember, refinancing an existing car loan to a lower payment can also help your DTI if you are applying for other financing later.
Tips for Improving Approval Odds Before Applying Through a Lender Network
Preparation is your best ally when you are self employed and seeking a car loan. Lenders in a network often have different underwriting guidelines, so presenting a clean, well organized financial profile can open doors to multiple offers. Here are practical steps you can take before you apply.
- Organize your documents: Gather two years of personal and business tax returns, recent bank statements, a current profit and loss statement, and any 1099s. Scan them into clearly labeled digital files so you can submit them quickly when requested.
- Check your credit reports: Obtain free copies of your credit reports from AnnualCreditReport.com and dispute any errors. A higher credit score can offset some of the uncertainty lenders feel about self employment income.
- Lower your DTI: Pay down high interest debt and avoid taking on new obligations before you apply. A lower DTI makes you a safer bet in the eyes of lenders.
- Save for a larger down payment: A substantial down payment reduces the amount you need to borrow and signals financial responsibility. It can also help you qualify for better rates.
- Work with a referral service: Platforms like CarLoanRefinancing.com connect you with a nationwide network of lending partners who understand self employed borrowers. You can submit one application and receive multiple offers, which saves time and improves your chances of finding a lender whose guidelines fit your profile.
Beyond these steps, consider timing your application strategically. If you have a strong recent quarter, apply when you can show that uptick in income. If you expect a large tax refund or a seasonal boost, waiting a few weeks might strengthen your bank statements. Small adjustments like these can add up to a meaningful difference in the offers you receive.
Before you commit to a loan, it is also wise to review your insurance options. Lenders typically require full coverage, and comparing quotes can help you budget for the total cost of ownership. You can explore resources for free auto insurance quotes online to understand typical rates and find coverage that fits your needs.
Navigating Income Verification with Confidence
Income verification does not have to be a barrier for self employed borrowers. By understanding the documents lenders accept, how they calculate qualifying income, and why DTI matters, you can approach the process with confidence. Lenders have developed flexible programs, including bank statement loans and tax return based loans, to serve borrowers with variable income. The key is to present a complete and consistent financial picture and to work with a referral service that can match you with the right lending partners.
Take the time to prepare your paperwork, check your credit, and run your DTI numbers before you apply. With a little effort upfront, you can streamline your car loan application and put yourself in the best position to secure favorable terms. Whether you are buying your first car or refinancing an existing loan, the right preparation makes all the difference. FreeAutoInsuranceQuotesOnline