
Budgeting for Unexpected Car Repairs and Maintenance
A practical system for budgeting for unexpected car repairs and maintenance, with monthly targets, smart places to save, and ways to protect your auto loan payment.
By Jonathan Hayes
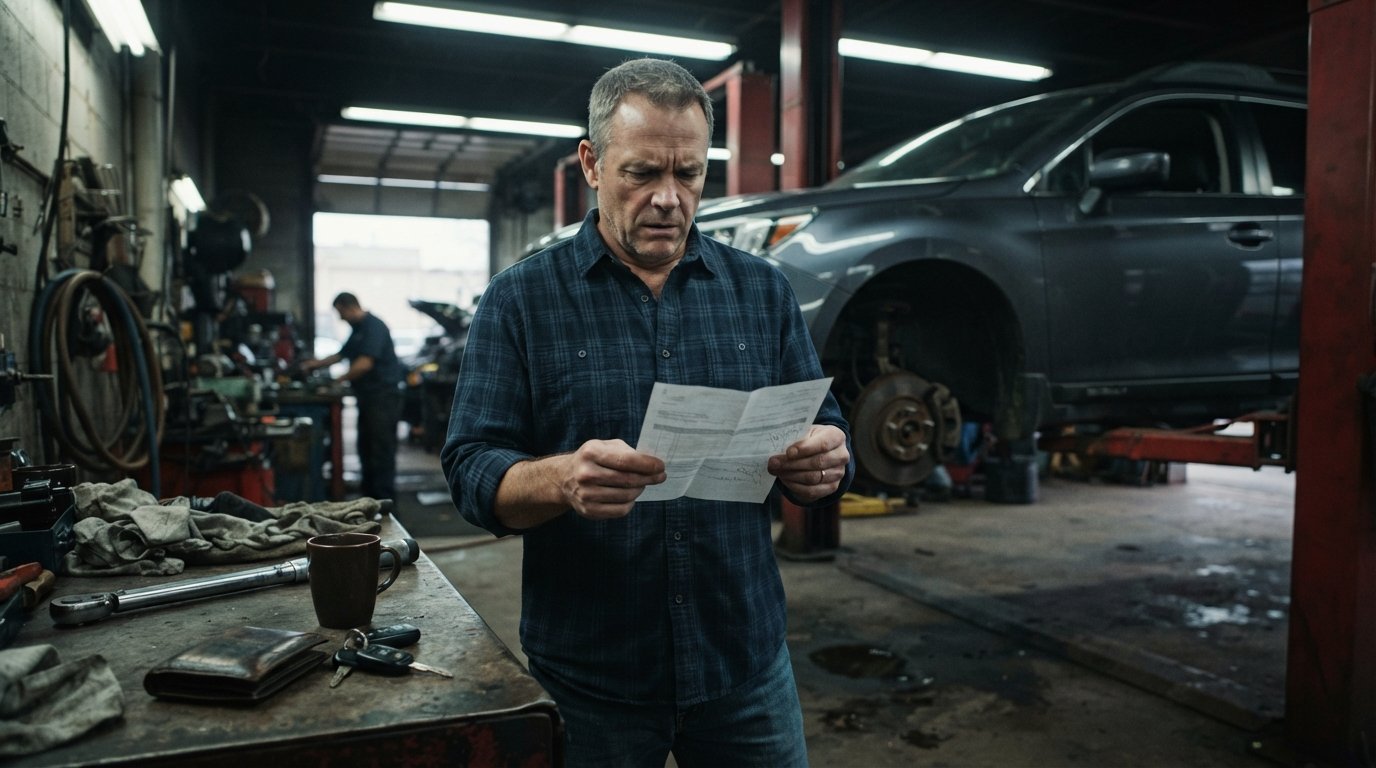
Your car starts making a strange noise on the way to work, and by lunchtime a mechanic is quoting you $1,400 for a repair you did not plan for. For most households, that single event is enough to derail a monthly budget, force a credit card swipe, or push an already tight auto loan payment into dangerous territory. The good news is that unexpected car repairs and maintenance are not truly unexpected. Every vehicle wears down, and every driver eventually faces a bill for brakes, tires, a battery, or a transmission. The difference between a financial setback and a minor inconvenience is whether you prepared for it.
This guide walks through a practical system for budgeting for unexpected car repairs and maintenance. You will learn how much to set aside, where to keep the money, how to protect your auto loan payment when a repair hits, and how to handle the moment when the bill is larger than your emergency fund. The goal is not to predict every failure. The goal is to make sure a repair never forces you into a high-interest loan, a missed payment, or a rushed decision at the dealership.
Why Car Repair Costs Catch So Many Drivers Off Guard
AAA has reported for years that the average annual cost of owning and operating a new vehicle runs well above $10,000 when you add up fuel, insurance, depreciation, and maintenance. Maintenance alone typically accounts for several hundred dollars per year, and that figure assumes nothing major breaks. Once a vehicle passes the five-year mark or crosses 60,000 miles, the probability of a significant repair rises sharply. Components like the timing belt, water pump, alternator, and suspension parts have predictable service lives, and they tend to fail in clusters rather than one at a time.
The core problem is that most drivers budget for car ownership using the loan payment as the anchor. They know the monthly payment, they know the insurance premium, and they assume everything else is small. Repairs do not behave that way. They arrive as lump sums, often at the worst possible moment, and they demand payment immediately. A $1,200 repair bill does not care that you just paid rent or that your emergency fund was already used for a medical copay.
There is also a psychological trap. Drivers tend to treat a repair as a one-time event rather than a recurring category. If you owned your car for ten years, you would almost certainly spend several thousand dollars on maintenance and repairs over that period. Spread across 120 months, that is a manageable monthly number. Compressed into a single stressful week, it feels like a crisis. Reframing repairs as a predictable monthly expense is the first step toward genuine financial control.
How Much Should You Set Aside Each Month
A useful rule of thumb is to budget between $50 and $100 per month for every vehicle you own, with older and higher-mileage cars at the upper end or above it. A newer car under warranty might need only $30 to $50 per month for tires, oil changes, and small wear items. A car with 120,000 miles on it, especially a European model or a truck used for towing, could reasonably require $150 per month or more. The right number depends on the vehicle's age, mileage, reliability record, and the cost of parts in your area.
To find your personal number, review the last three years of repair and maintenance receipts. Add them up, divide by 36, and you have your historical monthly average. Then adjust upward for known upcoming work. If your tires have 20,000 miles left and a set costs $800, you know roughly when that expense lands. If your timing belt is due at 100,000 miles and you drive 15,000 miles per year, you can estimate the year it will hit. This is not fortune telling. It is simply reading the maintenance schedule and doing basic arithmetic.
Here is a simple framework for setting your monthly figure:
- Under 5 years old or under 60,000 miles: $50 to $75 per month
- 5 to 10 years old or 60,000 to 120,000 miles: $100 to $150 per month
- Over 10 years old or over 120,000 miles: $150 to $250 per month
- High-performance, luxury, or heavy-duty vehicles: add 30 to 50 percent
- Vehicles used for rideshare or delivery work: add 50 to 100 percent
These ranges are starting points, not rules. The best budget is the one you can actually sustain. Setting aside $40 per month consistently beats intending to save $200 per month and never doing it. Once the habit is in place, you can increase the amount gradually as your income allows.
Where to Keep Your Car Repair Fund
The money you set aside for repairs should be separate from your everyday checking account and separate from your long-term emergency fund. If it sits in checking, it will get spent on groceries or a streaming subscription renewal. If it sits in a retirement account, you will face taxes and penalties when you withdraw it. The right home is a dedicated savings account, ideally at the same institution where you bank so transfers are instant, but with a label like "Car Repair Fund" so the purpose is clear.
A high-yield savings account works well for this purpose because the money is accessible within a day or two and earns some interest while it waits. Some drivers prefer a separate account at a different bank to add friction against impulse spending. Others use a sub-savings account offered by apps that let you create named buckets. Whichever structure you choose, the key is that the money is liquid, labeled, and not mixed with your general emergency savings.
There is a strong argument for keeping your car repair fund separate from your general emergency fund. A job loss, a medical bill, and a transmission failure are different kinds of emergencies with different timelines and different funding needs. If you have only one pool of money, a car repair can drain the account you were counting on for income replacement. Two smaller, dedicated funds give you more resilience than one large, undefined one.
Building the Fund When Money Is Already Tight
The hardest part of budgeting for unexpected car repairs and maintenance is finding the money in the first place. If your budget is already stretched, adding another savings category can feel impossible. The solution is to start small and to look for savings elsewhere in your car-related spending. One of the most effective moves is to reduce the cost of the loan itself. If you are paying a high interest rate on your auto loan, refinancing to a lower rate can free up $50 to $150 per month, and that difference can go directly into your repair fund.
Our guide on debt management and budgeting for car owners explains how to restructure car-related expenses so that savings from one area fund another. The principle is simple: every dollar you shave off your interest cost is a dollar you can redirect toward future repairs. Over the life of a loan, that redirect can add up to thousands of dollars.
Other ways to fund the account include:
- Deposit a portion of any tax refund directly into the car repair fund
- Redirect a raise or bonus for the first three months into savings
- Cut one subscription or dining expense and automate the difference
- Sell unused items and deposit the proceeds
- Use a cash-back rewards card for gas and deposit the rewards
Automation matters more than amount. A $25 automatic transfer on payday will quietly build a $300 fund in a year, and a $75 transfer will build $900. The goal in the first year is not to cover a transmission replacement. It is to cover the small and medium repairs that otherwise go on a credit card, and to build the habit that makes larger savings possible.
Protecting Your Auto Loan Payment When a Repair Hits
A repair bill and a car payment arriving in the same week is the scenario that pushes people toward payday loans and title loans. The way to avoid that trap is to decide in advance which obligations are untouchable and which are flexible. Your auto loan payment should be treated as untouchable because missing it damages your credit and can lead to repossession. Your repair fund exists precisely so you do not have to choose between the two.
If the repair is larger than your fund, you have several options, and the right one depends on the size of the gap and your credit situation. For smaller gaps, a short-term payment plan with the repair shop is often the cheapest route. Many shops offer no-interest financing for six to twelve months through a third-party provider, though you should read the terms carefully because deferred interest can be retroactive if you miss the payoff deadline. For larger gaps, a personal loan from a credit union or an online lender may be cheaper than a credit card, especially if your credit score has improved since you bought the car.
If you are already considering a change to your auto loan, a repair is actually a reasonable moment to review the whole picture. A refinance can lower your monthly payment, and the savings can be used to rebuild your repair fund. You can explore options through services like StartAutoLoan, which connects drivers with financing options even if their credit history is imperfect. The key is to avoid making a permanent financial decision in a moment of panic. Take a day, compare at least two or three offers, and choose the option with the lowest total cost, not just the lowest monthly payment.
Preventive Maintenance as a Budgeting Strategy
The cheapest repair is the one you never have to make. Preventive maintenance is not just a mechanical strategy, it is a financial one. Replacing a timing belt on schedule costs a fraction of replacing an engine after the belt fails. Changing transmission fluid every 30,000 to 60,000 miles is far cheaper than a transmission rebuild. Rotating tires and keeping them properly inflated extends their life by thousands of miles, which delays a $600 to $1,200 purchase.
The budgeting implication is that preventive maintenance should be a line item in your monthly plan, not an afterthought. If you set aside $100 per month and spend $60 of it on scheduled maintenance, you are still ahead because you avoided the $3,000 failure that was waiting at 100,000 miles. Think of the fund as covering both the routine and the unexpected, because in reality the routine is what prevents most of the unexpected.
A simple preventive maintenance calendar looks like this:
- Every month: check tire pressure, fluid levels, and lights
- Every 5,000 to 7,500 miles: oil and filter change, tire rotation
- Every 30,000 miles: air filter, cabin filter, transmission fluid check
- Every 60,000 miles: brake fluid, coolant, spark plugs, belts and hoses
- Every 90,000 to 100,000 miles: timing belt, water pump, major service
Following the manufacturer's schedule in your owner's manual is the single most reliable way to keep repair costs predictable. Skipping a $120 service to save money today often leads to a $1,200 repair two years later.
When to Repair and When to Replace
At some point, the cost of repairs starts to approach the cost of a different vehicle. The common rule is that if a single repair costs more than the vehicle's market value, or if annual repair costs exceed one year of new car payments, it may be time to replace. A more nuanced approach is to compare the annual cost of repairs plus the remaining loan balance against the cost of a replacement vehicle plus its loan. If the old car costs $3,000 per year in repairs and the new car costs $6,000 per year in payments and insurance, keeping the old car may still be the better financial decision, even if it is inconvenient.
This is where budgeting for unexpected car repairs and maintenance connects directly to your auto loan strategy. If you decide to replace the vehicle, the down payment can come from your repair fund, and the loan terms should be chosen with the same discipline you applied to the repair budget. If you decide to keep the vehicle, the repair fund gives you the cash to pay for the work without borrowing. Either way, the decision is made with numbers rather than emotion.
One more consideration: if you have equity in your current vehicle and your credit has improved, refinancing before you replace can reduce your payment and make the transition easier. A lower payment on the current car gives you more room to save for the next one, and it keeps your credit profile strong for the eventual purchase.
Putting the System Together
Budgeting for unexpected car repairs and maintenance comes down to four habits. First, calculate a realistic monthly amount based on your vehicle's age, mileage, and repair history. Second, keep that money in a separate, liquid savings account labeled for car repairs. Third, automate the transfer so the decision is made once rather than every month. Fourth, review your auto loan annually to make sure you are not paying more interest than necessary, because every dollar saved on interest is a dollar available for repairs.
Drivers who follow this system rarely experience a repair as a crisis. They may still wince at the bill, but they pay it, they move on, and their credit and their budget stay intact. That is the real goal. A car is a machine, and machines break. A budget is what turns a breakdown into an inconvenience instead of a financial emergency.