
Auto Refinance Denied by Multiple Lenders: Next Steps
Denied by multiple lenders? Learn the next steps after an auto refinance application denial, from reading adverse action notices to improving your approval odds.
By Megan Turner
You have applied to refinance your car loan with several lenders, and every single one has turned you down. The rejection letters are piling up, and you are not sure what to do next. This situation is more common than you might think, and it does not mean you are stuck with your current loan forever. In fact, understanding why the denials happened and taking a structured approach to recovery can put you back in control and improve your chances the next time you apply. Whether you are dealing with a high interest rate, a monthly payment that strains your budget, or simply want to change your loan term, the path forward starts with a clear diagnosis of what went wrong and a plan to fix it. This guide walks you through the auto refinance application denied by multiple lenders next steps so you can move from frustration to a concrete strategy.
Start by Reading Your Adverse Action Notices Carefully
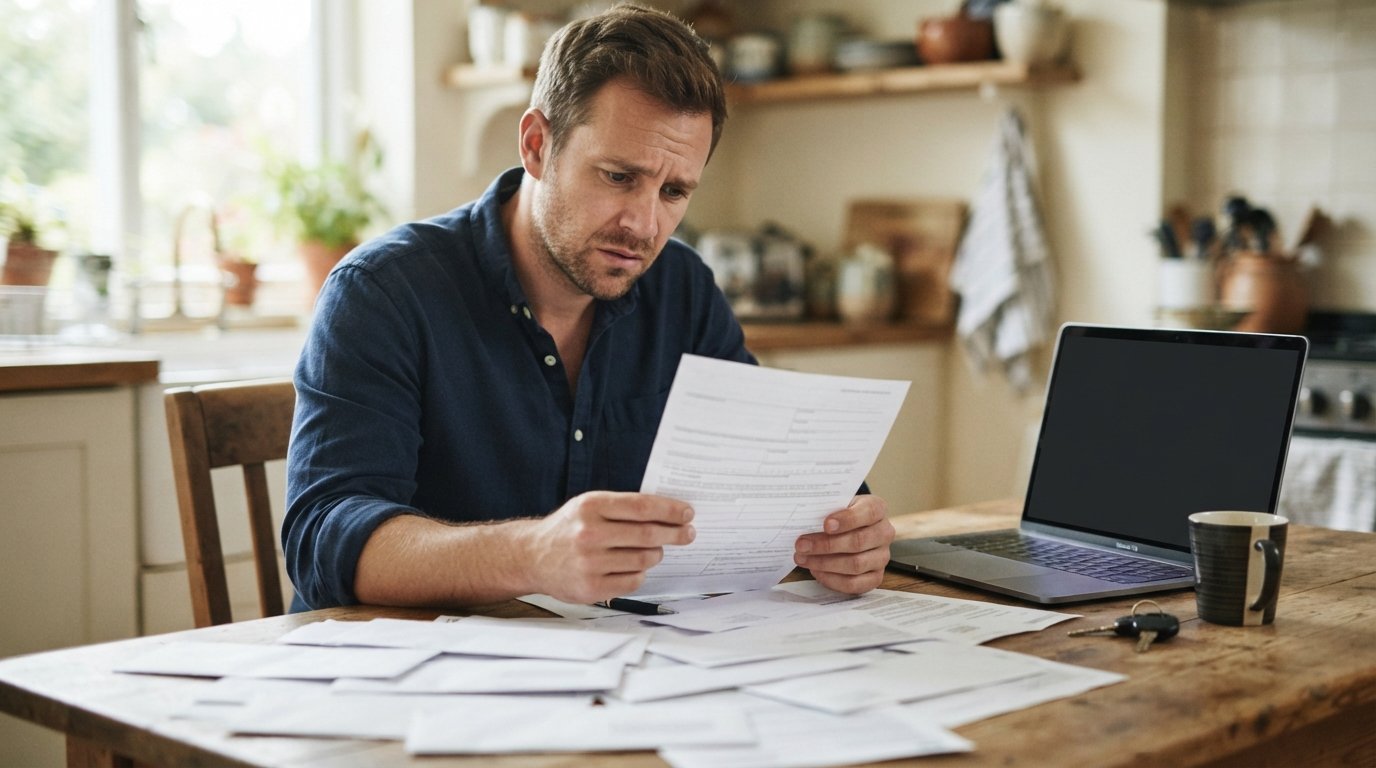
When a lender denies your application, they are required by law to send you an adverse action notice. This document is not just a formality; it contains the specific reasons why the lender decided not to approve your loan. Under the Equal Credit Opportunity Act and the Fair Credit Reporting Act, lenders must disclose the primary factors that influenced their decision. These notices often arrive by mail or email within a few weeks of your application, and they may look generic, but they hold valuable clues.
Common reasons listed on adverse action notices include a low credit score, a high debt-to-income ratio, insufficient income, a loan-to-value ratio that is too high, too many recent credit inquiries, or a short credit history. Some notices may also mention derogatory marks such as late payments, collections, or a previous bankruptcy. Do not skim these documents. Read each one line by line and note which factors appear most frequently across all your denial letters. If three out of four lenders cite your debt-to-income ratio, that is a clear signal that your income relative to your debts is the main obstacle. If credit score is the recurring theme, then credit improvement should be your focus.
If you receive a notice that cites a credit report from a specific bureau, you are entitled to a free copy of that report. Take advantage of this. Review the report for errors, outdated information, or accounts that are not yours. Disputing inaccuracies can sometimes raise your score quickly. Keep all your adverse action notices organized in a folder or digital file; you will refer back to them as you work through the next steps.
Diagnose the Real Reason Behind the Denials
Once you have gathered your notices, it is time to diagnose the root cause. Lenders evaluate refinance applications using a combination of factors, and understanding which ones are holding you back is essential. The three most common culprits are loan-to-value ratio, income and debt-to-income ratio, and credit profile. Each requires a different remedy.
Loan-to-Value Ratio (LTV)
Loan-to-value ratio compares the amount you owe on your car to its current market value. If you owe more than the car is worth, you have negative equity, and many lenders will deny a refinance because the collateral does not adequately secure the loan. This situation is especially common if you purchased the car with little or no down payment, if you rolled negative equity from a previous loan into the current one, or if the vehicle has depreciated faster than expected. To calculate your LTV, divide your remaining loan balance by the car's current private-party value (you can find this on sites like Kelley Blue Book or Edmunds). If the result is above 100 percent, you have negative equity. Even an LTV above 80 or 90 percent can be a red flag for some lenders, depending on their risk tolerance.
Income and Debt-to-Income Ratio (DTI)
Your debt-to-income ratio is your total monthly debt payments divided by your gross monthly income. Lenders use DTI to gauge whether you can comfortably afford the new loan payment. Most refinance lenders prefer a DTI below 40 to 50 percent, though some may accept higher ratios if other factors are strong. If your DTI is too high, it could be because your income is low, your debts are high, or both. The adverse action notice may state "excessive obligations in relation to income" or similar language. This is a signal that you need to either increase your income, reduce your monthly obligations, or both before reapplying.
Credit Profile
Your credit score and credit history play a major role in refinance approvals. Lenders look at your payment history, the age of your accounts, the types of credit you use, and how much of your available credit you are using (credit utilization). If your score is below the lender's minimum threshold, or if you have recent late payments, collections, or a bankruptcy, you may be denied. Even if your score is decent, a thin credit file or a high utilization rate can cause problems. Pull your credit reports from all three major bureaus and your FICO score to see where you stand. Many credit card issuers and banks offer free score access, and you can get free reports from AnnualCreditReport.com.
Strengthen Your Application Before Reapplying
Reapplying immediately without addressing the underlying issues will likely lead to another denial and another hard inquiry on your credit report. Instead, take time to strengthen your application. The specific steps depend on what your diagnosis revealed, but here are the most effective actions you can take.
- Pay down your loan balance or make extra payments. If your LTV is the problem, reducing the principal balance is the most direct solution. Even a few hundred dollars can move you into a more favorable LTV bracket. Consider making biweekly payments or rounding up your monthly payment to chip away at the balance faster.
- Improve your credit score. Focus on making all payments on time, reducing credit card balances, and disputing any errors on your credit reports. Avoid opening new credit accounts or closing old ones, as both can affect your score. A credit score improvement of even 20 to 30 points can make a significant difference in approval odds and interest rates.
- Increase your income or reduce your debts. If your DTI is too high, look for ways to boost your income (overtime, a side job, a raise) or pay down other debts. Paying off a small credit card or personal loan can lower your DTI quickly. Avoid taking on new debt, such as financing a furniture purchase or opening a new credit card, before you reapply.
- Save for a down payment. Some lenders allow you to pay down your loan balance at the time of refinancing, which effectively serves as a down payment and lowers your LTV. If you can set aside some cash, this can be a powerful way to improve your application.
- Wait for negative marks to age. If you have recent late payments or a collection, time is on your side. Most negative information loses its impact after 12 to 24 months, and some lenders have overlays that ignore older derogatory marks. A waiting period of six to twelve months can sometimes make the difference.
As you work on these improvements, keep an eye on your credit reports and scores. You can use free tools to monitor your progress. Set a target date for reapplying, such as six months out, and track your key metrics (credit score, DTI, LTV) along the way. This structured approach prevents you from applying prematurely and accumulating unnecessary hard inquiries.
Explore Alternative Paths to Refinancing
If you have strengthened your application but still face obstacles, consider alternative routes to achieve your goal. Not every borrower fits the standard refinance mold, and there are options that may work for your situation.
One option is to add a cosigner. A cosigner with strong credit and income can help you qualify for a refinance, especially if your own credit or DTI is borderline. However, be aware that the cosigner shares responsibility for the loan, and if you miss payments, their credit will be affected. This is a serious commitment, so discuss it thoroughly with the person before proceeding.
Another path is to work with a credit union or a community bank that specializes in serving members with less-than-perfect credit. These institutions often have more flexible underwriting guidelines than large national lenders and may consider factors like your relationship with the institution or a history of on-time payments with them. If you are not already a member, joining a credit union is often as simple as opening a savings account with a small deposit.
You might also consider waiting and reapplying later. If your denials were due to recent credit inquiries, a high utilization rate, or a short credit history, time can heal these issues. Six to twelve months of responsible credit behavior can significantly improve your profile. Use this time to pay down balances and avoid new credit applications.
Additionally, if your current loan is with a lender that offers a modification program, you might ask about adjusting your terms without a full refinance. Loan modifications can sometimes lower your interest rate or extend your term, though they are not the same as a refinance and may have different eligibility requirements. Finally, if you are struggling with negative equity and cannot refinance, focus on paying down the loan as quickly as possible. Once your LTV drops below 100 percent, more lenders will be willing to work with you. For vehicles that are older or have higher mileage, you may need to target lenders that specialize in those loans; our guide on auto refinance for older cars eligibility explains how to find them.
Manage Hard Inquiries and Protect Your Credit
Every time you apply for a refinance, the lender typically pulls your credit, which results in a hard inquiry. Multiple hard inquiries in a short period can lower your credit score and signal to future lenders that you are desperate for credit. To avoid a cycle of hard inquiries, it is important to manage your applications strategically.
First, avoid applying to multiple lenders on the same day or within a few days of each other. While some rate-shopping windows exist for mortgage and auto loans (usually 14 to 45 days), refinance applications may not always fall under those protections, and each application still counts as a separate inquiry. Instead, use pre-qualification tools that perform soft pulls. Many lenders, including the network partners at CarLoanRefinancing.com, offer pre-qualification with no impact on your credit score. Pre-qualification gives you an estimate of your chances and potential rates without a hard inquiry. You can then choose one or two lenders to formally apply with.
Second, space out your applications. If you are denied, do not immediately apply to another lender. Take at least three to six months to address the issues before trying again. This gives your credit report time to recover from the inquiry and allows you to make meaningful improvements.
Third, monitor your credit reports regularly to ensure that inquiries are being reported accurately. If you see inquiries that you did not authorize, dispute them. Also, be cautious about offers that promise guaranteed approval; these often come with high fees or unfavorable terms and may not be legitimate.
Know When to Pause and Reassess Your Goals
After multiple denials, it may be tempting to keep applying until someone says yes. However, repeated applications without changes to your profile can harm your credit and waste your time. Sometimes the best next step is to pause and reassess whether refinancing is the right goal right now.
Consider whether your current loan is actually unmanageable or whether you simply want a lower rate. If you can comfortably afford your payments, you might decide to focus on paying down the loan faster rather than refinancing. If your goal is to free up cash flow, you could explore other budgeting strategies or look for ways to increase income. If your credit is severely damaged, a refinance may not be feasible for a year or more, and that is okay. Use the time to rebuild your credit and save money for a larger down payment on your next vehicle or for a future refinance.
Also, think about the total cost of refinancing. Closing costs, fees, and the potential for a longer loan term can offset the benefits of a lower rate. Use an auto loan calculator to compare your current loan with potential refinance offers, factoring in all costs. If the savings are marginal, it may not be worth the effort and credit impact.
Finally, remember that your situation is not permanent. Many borrowers who are denied today become approved borrowers in six to twelve months after taking the steps outlined above. Stay patient, stay informed, and keep your financial goals in sight. And if you are also looking to save on other vehicle-related expenses, you can compare free auto insurance quotes online to potentially lower your overall car ownership costs while you work on your refinance strategy.
In the end, an auto refinance application denied by multiple lenders next steps involve a methodical review of the reasons, a commitment to improving your financial profile, and a strategic approach to future applications. By reading your adverse action notices, diagnosing the real issues, strengthening your application, exploring alternatives, and managing your credit wisely, you can turn a string of denials into a successful refinance down the road. The key is to act deliberately rather than react impulsively, and to use the resources available to you, including educational platforms like CarLoanRefinancing.com, to guide your decisions.