
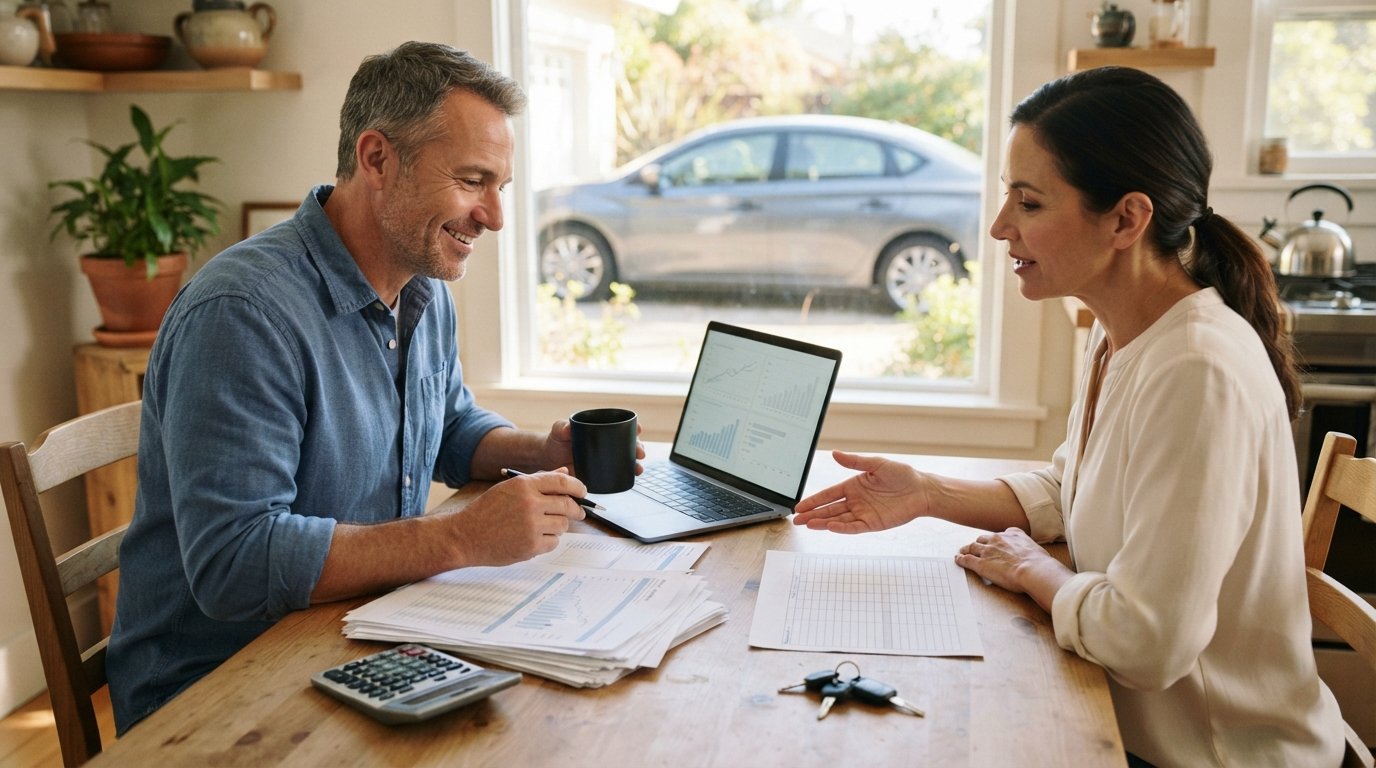
Auto Loan Refinance With No Credit Check Options
Explore auto loan refinance with no credit check options that use payment history and income instead of a score, and learn how to lower your monthly payment.
By Rachel Simmons
Your car payment clears your account every month like clockwork, yet the interest rate attached to that loan may have been set when your credit told a different story. Maybe you had a bankruptcy in your past, a thin file with almost no history, or a stretch of missed payments that still haunts your score. Whatever the reason, the math is simple: a high annual percentage rate on a five or six year loan can cost you thousands of dollars more than the car is worth in interest alone. That is why so many drivers search for an auto loan refinance with no credit check options, hoping to escape an expensive loan without facing another hard inquiry or another rejection letter.
Here is the honest truth up front: a true, large-scale lender that never looks at your credit at all is rare, and the offers that promise one are often expensive or predatory. What does exist is a legitimate middle ground. Many refinance programs use alternative approval methods, soft credit pulls, or manual underwriting that weighs your payment history, income, and down payment history instead of a three-digit score. Understanding how that middle ground works, and how to reach it, is the difference between saving real money and walking into a worse deal than the one you already have.
What No Credit Check Refinancing Really Means
When people say they want an auto refinance with no credit check, they usually mean one of three different things, and lenders treat each one differently. The first is a soft-pull prequalification, where the lender estimates your rate using limited data and does not ding your score. The second is a no-score program, where the lender ignores the numeric score but still reviews your credit report for charge-offs, repossession history, or active bankruptcies. The third is a genuine no-look loan, typically offered by a buy-here-pay-here dealership or a small finance company, and it almost always comes with a much higher rate because the lender is taking on enormous risk.
For most drivers, the second category is the realistic target. A refinance lender that uses manual underwriting can approve you based on twelve months of on-time payments on your current auto loan, a stable income, and proof that the vehicle is worth more than the remaining balance. Your credit score may still be pulled, but it functions as one data point rather than a gate. This distinction matters because it separates programs that can genuinely lower your rate from programs that simply replace one expensive loan with another.
It also helps to understand why lenders care about credit in the first place. Your score is a shorthand for how likely you are to repay, and refinancing is an unsecured risk for the lender in the sense that the collateral (your car) loses value every month. A no credit check refinance shifts that risk calculation. The lender compensates by charging more, requiring a lower loan-to-value ratio, or limiting the states where it operates. Knowing which trade-offs you are willing to accept keeps you in control of the process.
How Refinancing Without a Traditional Credit Check Works
The mechanics of a no credit check refinance are similar to a standard refinance, with a few extra steps built in to replace the missing credit data. You apply, the lender reviews your current loan and vehicle details, and then an underwriter decides whether your payment history and income are strong enough to justify a new loan. If approved, the new lender pays off your existing loan and you begin making payments on the new terms, ideally at a lower rate or a shorter term.
What changes is the evidence you provide. Instead of relying on a FICO score, the lender may ask for bank statements showing consistent income, a payment history from your current auto lender, proof of insurance, and the vehicle identification number so it can verify the car's value. Some lenders also look at how long you have owned the vehicle and how much equity you have built. A borrower with twelve clean payments and 20 percent equity is a very different risk than someone who just bought the car last month with nothing down.
The process typically unfolds in a predictable sequence. Here is what to expect:
- Prequalification with a soft credit pull, which lets you see estimated rates without affecting your score.
- Submission of documents such as pay stubs, bank statements, and your current loan statement.
- Manual underwriting review, where a person evaluates your payment history and income rather than a formula alone.
- Vehicle appraisal or value verification to confirm the loan-to-value ratio.
- Final approval, payoff of the old loan, and setup of your new payment schedule.
Each step gives you a chance to walk away. That is important, because a no credit check refinance should still make financial sense. If the new rate is higher than your current one, or the term stretches so long that you pay more overall, the approval is not actually a win. The goal is a lower total cost, not just a different lender.
It also helps to know that not every state treats these loans the same way. Some states cap interest rates on refinanced auto loans, and others require specific disclosures when a lender uses alternative underwriting. If you want a deeper look at how location affects your options, our guide on state auto loan refinance laws breaks down the key rules by state so you can check what applies to you before you apply.
Who Qualifies for a No Credit Check Auto Refinance
Qualification for these programs is less about a number and more about a pattern. Lenders want to see that you have handled a car loan responsibly, even if your broader credit history is messy. Someone who filed for bankruptcy two years ago but has made every auto payment on time since then is often a strong candidate. Someone with a perfect score but a recent repossession is not. The pattern of repayment on the specific loan being refinanced carries more weight than almost anything else.
Income stability is the second pillar. A lender needs to believe you can absorb the new payment, so it will look at how long you have been with your employer, whether your income is steady or seasonal, and how much of your monthly budget goes toward debt. A borrower earning $4,000 a month with a $600 car payment and no other major obligations looks very different from someone earning the same amount with a $600 payment and three maxed-out credit cards. Documenting your income clearly can offset a weak credit file.
Vehicle equity is the third pillar and often the most overlooked. If your car is worth $18,000 and you owe $14,000, you have $4,000 of equity, which gives the lender a cushion if it ever has to repossess. That cushion can unlock approval even when your credit is poor. If you are upside down, owing more than the car is worth, your options narrow considerably, and you may need to wait until you have paid the balance down before refinancing makes sense.
Other factors that commonly influence approval include:
- A minimum of six to twelve months of payment history on the current loan.
- Proof of continuous insurance coverage on the vehicle.
- A loan-to-value ratio that the lender considers acceptable, often 125 percent or lower.
- No active bankruptcy filing, though discharged bankruptcies are frequently allowed.
- A vehicle that meets age and mileage limits, usually under ten years old and under 150,000 miles.
If you meet most of these criteria, a no credit check refinance is worth exploring. If you meet only one or two, it may be smarter to spend six months improving your payment pattern first, then apply when your profile is stronger and your rate offers are better.
Where to Find Legitimate No Credit Check Refinance Lenders
The safest path to a no credit check refinance is through a referral platform that works with a nationwide network of lending partners rather than a single storefront lender. That structure lets you compare multiple offers with one application, and it reduces the chance that you accept the first expensive deal you see. Independent connection services like StartAutoLoan are built for exactly this situation, connecting borrowers with bad credit, no credit, or past bankruptcies to lenders who specialize in those profiles.
Credit unions are another strong option. Many are willing to do manual underwriting for members, especially if you have a relationship with them through a checking account or direct deposit. Their rates tend to be lower than banks because they are nonprofit, and they are often more flexible about alternative credit data. The trade-off is that membership requirements vary, and not every credit union offers no credit check refinancing.
Online lenders that focus on subprime borrowers occupy the middle of the market. They typically pull credit but weigh it less heavily than a traditional bank, and they often approve borrowers in the 500 to 600 score range. Rates are higher than prime offers, but they can still beat the dealership financing that many people are trying to escape. The key is to compare the new rate against your current one, not against the best rate advertised on television.
What you should avoid are lenders that ask for a large upfront fee before approving you, promise guaranteed approval with no documentation, or pressure you to sign before you have seen the full terms. Legitimate lenders disclose the APR, the total finance charge, and the payoff amount in writing before you commit. If any of that is missing, walk away.
Steps to Refinance Without a Credit Check
Once you have identified a few lenders or a referral platform, the application process itself is straightforward. The work is mostly in the preparation. Gather your documents before you start so you can move quickly when you find an offer worth taking, and be ready to explain any credit blemishes in plain language. Underwriters respond well to context, such as a medical emergency or a layoff that is now behind you.
Here is a practical sequence that keeps you in control:
- Check your current payoff amount and the exact terms of your existing loan, including the APR and remaining months.
- Estimate your vehicle's value using a reputable pricing guide so you know your equity position.
- Gather proof of income, insurance, and identity documents.
- Apply through a comparison platform or two or three lenders to see multiple offers.
- Compare APRs, total finance charges, and loan terms side by side before choosing.
- Review the final contract carefully, then sign and let the new lender pay off the old one.
After the new loan is funded, confirm that the old lender has received the payoff and that your title is being transferred correctly. Set up automatic payments if you can, since consistent on-time payments on the new loan will strengthen your credit profile over time. Within twelve to eighteen months, you may be able to refinance again at an even better rate as your score recovers.
One more consideration: refinancing does not erase the original loan from your credit history, but it does replace the active tradeline with a new one. If your goal is long-term credit repair, the new loan is a fresh opportunity to build a clean payment record. Treat it that way, and the refinance becomes part of a broader financial recovery rather than a one-time fix.
An auto loan refinance with no credit check options can be a genuine lifeline for drivers stuck in expensive loans, but it works best when you understand the trade-offs and choose a lender that uses alternative data rather than simply charging more. Do the preparation, compare more than one offer, and measure success by the total cost of the loan rather than the speed of approval. With the right approach, you can lower your payment, protect your credit, and put yourself in a stronger position for the next vehicle you finance.